An S Corp election is a tax choice that lets an eligible LLC or corporation have its income taxed at the owners' level instead of at the company level. This guide is for owners of US LLCs and corporations who are asking whether an S Corp election is worth pursuing. After reading it, you will know the five checks to run before you file Form 2553, and when to stop and take advice.
Tax outcomes depend on individual circumstances, and a licensed US tax professional should confirm your eligibility before you file. This article is general information, not professional advice, and the rules change, so verify every point on irs.gov.
Key Takeaways
- An S Corp election is a tax classification, not a business type, and it sits on top of your LLC or corporation.
- The five checks are eligibility, timing, reasonable salary, payroll and return changes, and whether it fits at all.
- Nonresident alien shareholders are not allowed, so S Corp eligibility depends on ownership first.
- Owner-employees must be paid reasonable compensation through payroll before taking other distributions.
- A licensed US tax professional should confirm eligibility and the numbers before you file your S Corp election.
In This Article
- What an S Corp Election Actually Is
- Check 1: S Corp Eligibility and Ownership
- Check 2: Timing and Form 2553
- Check 3: A Reasonable Salary
- Check 4: Payroll and Form 1120-S Changes
- Check 5: When an S Corp Election May Not Fit
- How the Process Works Step by Step
- Common Mistakes to Avoid
What an S Corp Election Actually Is
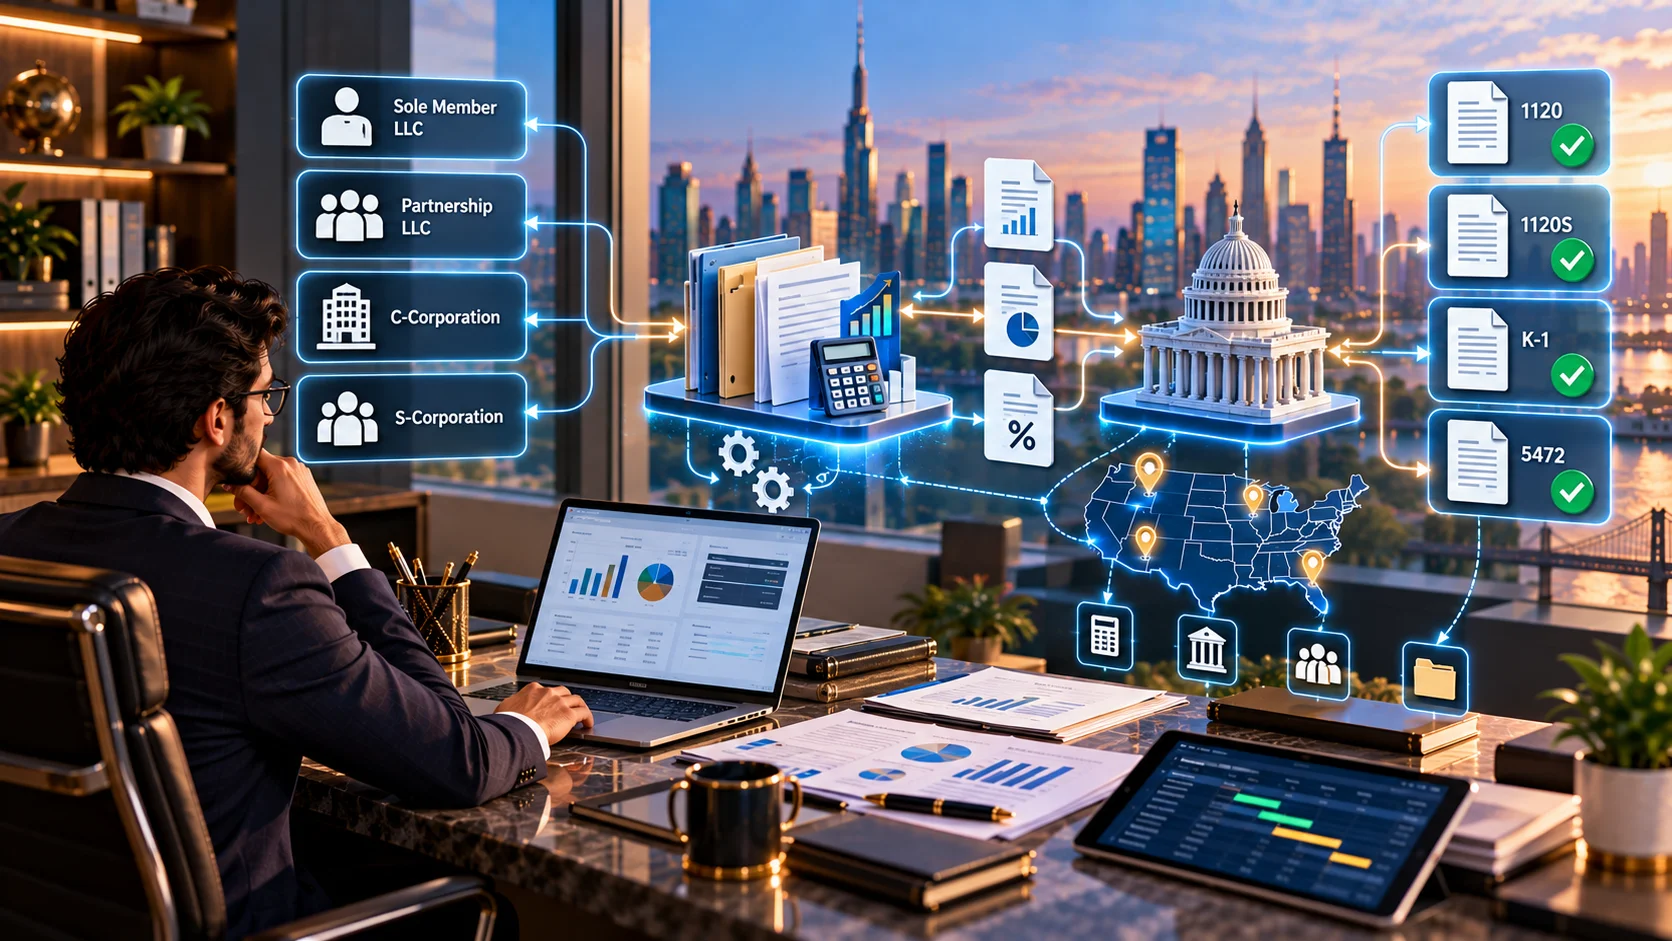
An S Corp election is a federal tax status, not a legal entity. A domestic corporation or an eligible LLC files Form 2553 with the IRS and, if the S Corp election is valid, its income, losses, deductions and credits pass through to the shareholders. Shareholders report them on personal returns. The legal entity itself, and any organization around it, does not change.
The IRS says the aim is to avoid taxing the same income twice. The company can still owe tax on certain items, such as built-in gains and passive income, so pass-through does not mean tax-free.
Entity Type and Tax Classification Are Different Things
The entity type comes from your state. The tax classification comes from the IRS. According to the IRS, a single-member LLC is disregarded as separate from its owner by default, and a multi-member LLC is treated as a partnership by default.
An LLC can choose a different classification. The IRS says an LLC can file Form 8832 to elect corporate treatment. For an eligible entity that wants S status, the Form 2553 instructions say it generally does not need to file Form 8832 separately, because the Form 2553 election also treats it as a corporation.
Why Owners Look at It
The usual reason for an S Corp election is payroll tax. The IRS compensation page says wage payments are subject to employment taxes, while non-wage distributions are not. That difference is why the IRS watches how owners split their pay, which we cover in Check 3.
An S Corp election is not a guaranteed saving. It adds cost and rules. Our team starts with that question before we file anything, through our US S-Corp election service.
Check 1: S Corp Eligibility and Ownership
S Corp eligibility is the first gate. The IRS says the corporation must be domestic, have no more than 100 shareholders and have only one class of stock. Shareholders can be individuals, certain trusts and estates. Partnerships, corporations and nonresident alien shareholders are not permitted. If any of these fail, the election can be invalid.
The table below summarises the rules on the IRS S corporations page and the Form 2553 instructions.
| Requirement | What the IRS says |
|---|---|
| Entity | Domestic corporation or eligible entity |
| Shareholders | No more than 100 |
| Allowed holders | Individuals, certain trusts, estates |
| Not allowed | Partnerships, corporations, nonresident aliens |
| Stock | One class only |
The Non-Resident Alien Shareholder Restriction
This is the rule that catches founders who live abroad. The IRS S corporations page lists nonresident alien shareholders as not allowed. The Form 2553 instructions repeat the point and note a narrow exception for a nonresident alien who is a potential current beneficiary of an electing small business trust.
For a founder based outside the US, the practical result is simple. If you are a nonresident alien for US tax purposes and you hold shares directly, the corporation is not eligible. Residency for tax purposes is a technical test, so do not guess. Our guide to a US LLC for non-US founders explains how foreign ownership changes the filings, and a US tax professional should confirm the status of every owner.
One Class of Stock
One class of stock means all shares carry the same rights to profits and assets. The instructions say differences in voting rights are disregarded. Trouble arises when an operating agreement or shareholder agreement gives some owners a different share of distributions. A clean, written ownership structure avoids that.
The instructions also exclude some banks and insurance companies. If you work in a regulated industry, ask before assuming you qualify.
An Illustrative Scenario
Consider a US LLC considering an S Corp election, with two owners who both live in the US and are individuals. Neither owner is a corporation or partnership, and the operating agreement gives each the same rights per unit. On the facts alone, this looks like a candidate. Now change one detail: one owner moves abroad and becomes a nonresident alien for tax purposes. The structure may no longer qualify. This scenario is invented for illustration and is not a real client case.
If you need to set up or adjust the entity first, see US LLC formation and US corporation formation. Your entity also needs an EIN, which our US EIN registration page covers.
Check 2: Timing and Form 2553
The IRS form for an S Corp election is Form 2553. The IRS says it is used to make an election under section 1362(a) to be an S corporation. The instructions say it must be filed no more than 2 months and 15 days after the beginning of the tax year the election is to take effect, or at any time during the preceding tax year.
Anything more specific depends on your facts, so confirm it on irs.gov or with a tax professional.
What the Instructions Add About Timing
The instructions also explain that, for a new corporation's first tax year, the window runs from the start of that year through the end of the 2-month-and-15-day period. An S Corp election made before the year starts is not valid. That detail matters for newly formed companies.
Plan the election before the tax year you want it to apply to, not at the end of it.
Who Signs
The instructions say an authorised corporate officer must sign and date the form, and an unsigned form is not treated as timely filed. Each required shareholder consents by signing in the shareholder column or on a separate consent statement. A missing signature can sink the S Corp election, so collect every consent before you send the form.
Where to File
The instructions say to send the original form, or fax it, to the IRS service center for your principal business location. They list the Kansas City and Ogden service centers and direct readers to the IRS page for Form 2553 filing addresses for current details. The IRS also notes that filing addresses can change, so check the page on the day you file. See the IRS Form 2553 page.
If You Miss the Window
The IRS has a page on late election relief. It says relief under Rev. Proc. 2013-30 can be available if the entity intended S status, is eligible, failed to qualify only because the S Corp election was late, and has reasonable cause. The page also states conditions, including consistent reporting by the entity and all shareholders.
Relief is not automatic and has its own time limits, which the IRS page sets out. Treat it as a rescue option, not a plan.
Check 3: A Reasonable Salary
Once the S Corp election is in place, an owner who works in the business is a shareholder-employee. The IRS says an S corporation must pay a shareholder-employee reasonable compensation for services before making non-wage distributions. This reasonable salary is the most scrutinised part of an S Corp election, and it is where owners most often go wrong.
What the IRS Looks At
The IRS compensation page does not set a number or a percentage. Instead it lists factors it considers, including:
- Training and experience
- Duties and responsibilities
- Time and effort devoted to the business
- Dividend history
- Payments to non-shareholder employees
- Pay at comparable businesses for similar services
- Compensation agreements and any formula used to set pay
The page says the key question is what the shareholder-employee did for the company. Payments tied to the owner's own personal services should be wages. The IRS can reclassify payments from non-wage distributions to wages, which are subject to employment taxes.
Why a Documented Basis Helps
A salary that is easy to explain is easier to defend. Write down the role, the hours, the market comparison and the date you set it, and review it as duties change. In the filings we handle, we often see owners pick a figure without any written basis, so we record the reasoning at the time.
Wages Versus Distributions
Wages go through payroll with withholding. Distributions are payments of profit to shareholders and do not carry employment tax. Keep the two apart in the books, or it becomes hard to show that pay was reasonable.
Health Insurance for Larger Shareholders
The IRS compensation page has a section on shareholders who own more than 2% of the company. It says their health premiums are generally reported as wages in Box 1 of Form W-2, and that special rules affect the deduction if the shareholder pays personally. If you or a co-owner hold more than 2%, raise this with your tax professional before the first payroll run.
Check 4: Payroll and Form 1120-S Changes
After an S Corp election, the company runs formal payroll for owner-employees and files its own annual return. Form 1120-S replaces the return you used before, and each shareholder receives a Schedule K-1. Payroll tax filings continue on a regular schedule. Expect more bookkeeping, more deadlines and a cleaner split between salary and profit.
The Company-Level Return
The IRS says Form 1120-S is the return used to report the income, gains, losses, deductions and credits of a domestic corporation or other entity covered by an S corporation election. The S corporation sends the IRS a copy of Schedule K-1, which reports each shareholder's share of income, deductions and credits.
The IRS also says S corporations that must file 10 or more returns in a calendar year, counting all return types together, must e-file Forms 1120-S, effective for returns required to be filed on or after January 1, 2024. We do not state return due dates here, so use the current IRS instructions for Form 1120-S. Our US business tax filing service covers the annual return side.
Payroll Obligations
The IRS lists the employment tax items for an S corporation: Social Security, Medicare and income tax withholding, federal unemployment tax, and depositing employment taxes. The forms it names include Form 941 and Form 940. This is the same payroll machinery any employer runs, now applied to the owner.
For a business that has never run payroll, that is a real change. In the filings we handle, the most common delay is owner payroll not being ready when the S Corp election takes effect, which leaves salary and distributions mixed together in the books.
What Shareholders Do Differently
Shareholders report their share of the S corporation's items on personal returns. The IRS lists Form 1040 or 1040-SR with Schedule E, plus Form 1040-ES for estimated tax. Plan cash for tax on passed-through profit, even when the profit stays in the company.
State Rules
States treat S corporations in their own ways. This article covers federal rules only, so check your state tax agency.
Check 5: When an S Corp Election May Not Fit
An S Corp election does not suit every business. It may not fit if profits are low, if payroll adds more cost than it saves, if the ownership structure fails the eligibility rules, or if you plan to bring in investors that the rules do not allow. The right answer depends on your numbers and plans.
Low or Uneven Profits
Because the S Corp election requires reasonable pay and payroll, the benefit depends on profit above a fair salary. If the business earns little, the extra payroll cost and return preparation can outweigh any tax difference. Uneven profits also make the salary question harder to answer.
Ownership That Does Not Qualify
The rules on shareholder type and number can rule you out or limit you later. A foreign shareholder, a corporate or partnership investor, or a second class of shares can all create problems. Check S Corp eligibility at each ownership change, not only when you file.
Plans for Investors or a Sale
If you may raise outside money or sell the business, ask how an S Corp election affects those plans. Investors often want share rights that the one-class rule does not allow.
Ongoing Compliance Burden
An S Corp election is not a one-off form. Payroll, books, the annual return and eligibility need attention every year. If you cannot commit to that, a simpler structure may serve you better.
How a Default LLC Compares
A default LLC has fewer formalities. There is no separate corporate return and no required owner payroll by default. You give up the possible payroll tax difference and gain simplicity.
How the Process Works Step by Step
The steps below are a general process, not a promise of an outcome.
-
Confirm the entity and EIN. Check that the LLC or corporation exists and has an EIN.
-
Review every owner. Confirm each shareholder is an eligible type and not a nonresident alien.
-
Check the stock structure. Make sure there is only one class of stock.
-
Choose the effective date. Pick the tax year, then check it against the Form 2553 timing wording.
-
Model the numbers. Compare salary, payroll and return costs with the possible saving.
-
Prepare and sign Form 2553. Collect officer and shareholder signatures and send it to the right service center.
-
Set up payroll and books. Have owner payroll ready for the effective date.
-
Plan the annual routine. Calendar payroll filings, the annual return and a yearly salary review.
An Illustrative Walkthrough
Consider a profitable US corporation owned by one US-resident individual that has been taxed as a regular corporation. The owner works full time in the business. After confirming eligibility and timing, the owner and adviser benchmark a salary, set up payroll before the effective date and agree the annual return will be Form 1120-S. This example is invented for illustration only and is not a real client story.
Common Mistakes to Avoid
Most problems with an S Corp election come from skipped checks, not from the form itself.
-
Ignoring owner residency. A nonresident alien shareholder can make the corporation ineligible.
-
Missing the timing window. The S Corp election wording on 2 months and 15 days is easy to overlook.
-
Missing signatures. An unsigned form is not treated as timely filed, and all required shareholders must consent.
-
Paying no salary. The IRS says reasonable compensation comes before non-wage distributions.
-
Setting pay with no basis. An undocumented figure is hard to defend.
-
Not ready for payroll. Salary and distributions mixed in the books create avoidable problems.
-
Creating a second class of stock by accident. Unequal distribution rights can break the one-class rule.
-
Treating it as a one-time filing. An S Corp election needs eligibility and salary review every year.
Based on our experience, a short review before you file costs far less than fixing an invalid election later. We recommend checking each item above against the current IRS pages, such as the IRS S corporations page.
Summary
An S Corp election is a federal tax classification that an eligible LLC or corporation can choose by filing Form 2553. The S Corp election can change how owner income is taxed, but only when eligibility, timing, reasonable salary and payroll are all handled properly. It adds compliance work, including Form 1120-S, and it does not suit every business. Confirm your facts with a licensed US tax professional first.
Conclusion
An S Corp election can be a sound choice for the right owner-operated business, but only after five checks: eligibility, timing, a reasonable salary, payroll and return changes, and honest fit. Check each one against current IRS pages before you file, and revisit them each year. If you want help assessing your position, talk to Livida about your S Corp election.
Talk to Livida
If you want to know whether an S Corp election makes sense for your LLC or corporation, we can review it with you. Use our US contact page, email info@livida.in or call +91 94860 33194. Livida is based in India and supports US clients remotely. We do not have a US office, we do not give individual tax outcomes or guarantee IRS decisions, and a licensed US tax professional should confirm eligibility.
References
- IRS: S corporations
- IRS: About Form 2553, Election by a Small Business Corporation
- IRS: Instructions for Form 2553
- IRS: S corporation compensation and medical insurance issues
- IRS: Late election relief
- IRS: About Form 1120-S
- IRS: Limited liability company (LLC)
Reviewed for accuracy in November 2026.
Related Reading
- US S-Corp election service, for eligibility review, Form 2553 and payroll setup
- US LLC formation, for the entity many owners elect from
- US corporation formation, if you are comparing corporate structures
- US business tax filing, for the annual federal return after the election
- US EIN registration, if your entity does not yet have an EIN
- US LLC for Non-US Founders: 9 Essential Steps, No Costly Mistakes, to check how foreign ownership affects eligibility