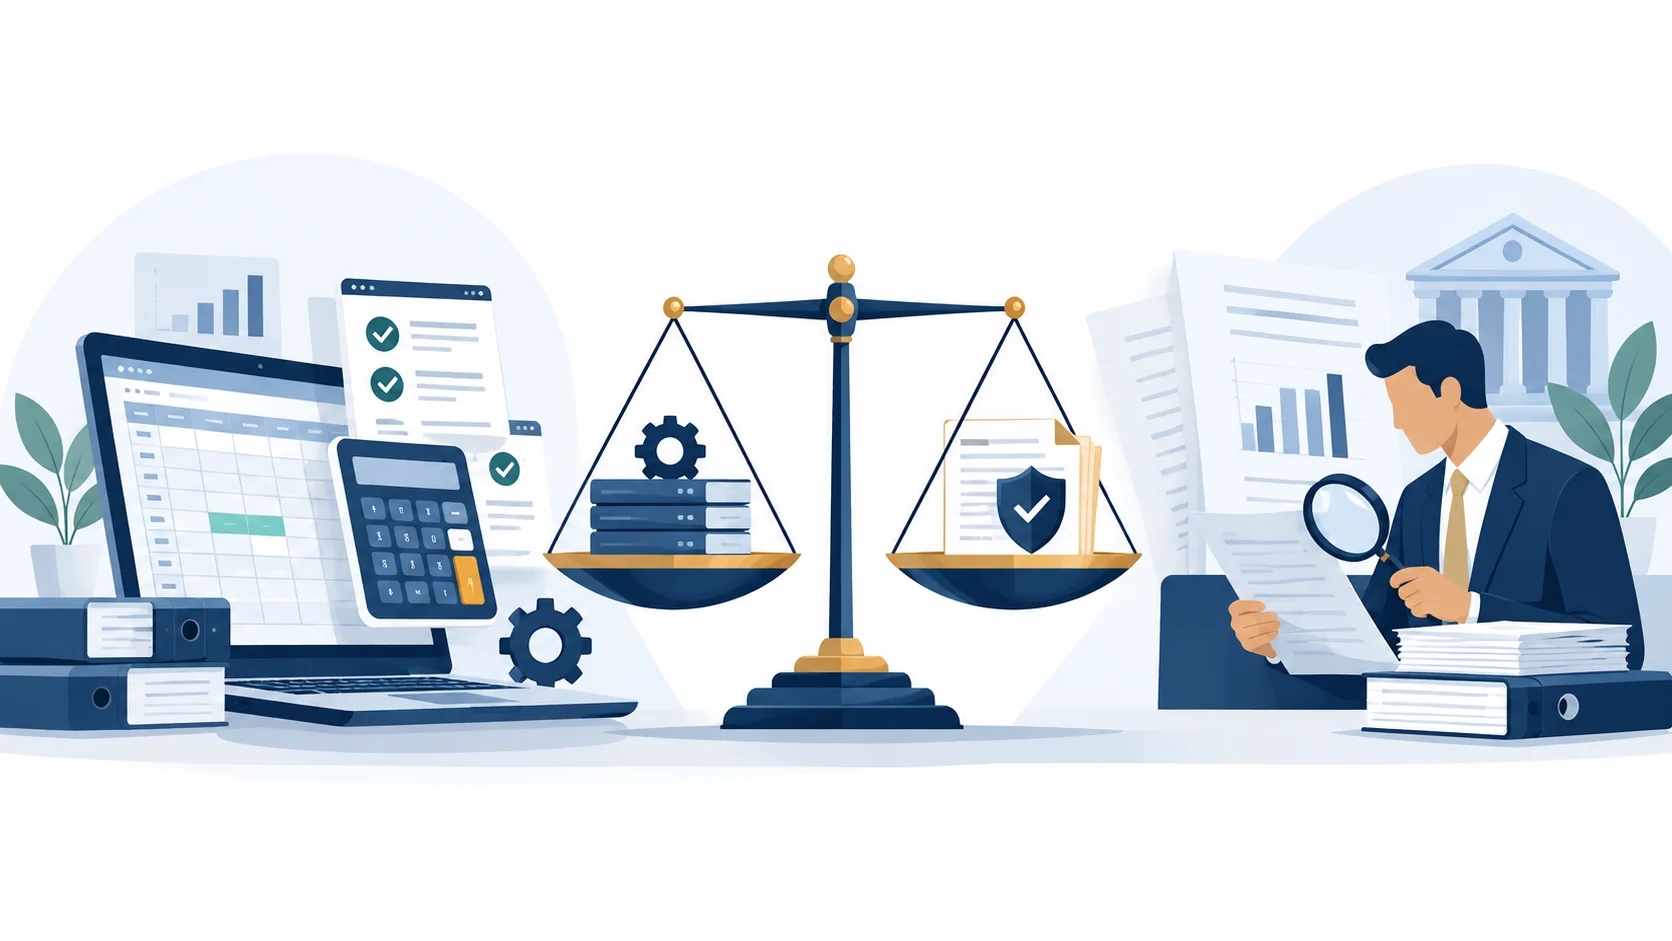
Corporate tax software has become a standard tool for finance teams preparing annual tax computations, automating arithmetic that used to be done manually across spreadsheets and paper working papers. These tools can apply standard adjustments, calculate capital allowances once asset details are entered, and format a computation ready for submission to the tax authority. What they generally cannot do is determine, independently, which adjustments actually apply to a specific company's circumstances, which is where corporate tax advisory continues to play a decisive role in whether a filed computation is not just calculated correctly, but substantively accurate.

| Corporate Tax Software | Corporate Tax Advisory | |
|---|---|---|
| Handles | Arithmetic, formatting, carrying forward prior-year balances | Judgment on deductibility, relief eligibility, non-routine transactions |
| Verifies | Completeness and internal consistency | Whether classifications actually reflect the company's real circumstances |
| Risk if used alone | Compliance-ready but not necessarily compliant | Slower without software support for the mechanical work |
| Best used as | The computation and filing engine | The judgment layer reviewing what feeds into it |
Key Takeaways
- Corporate tax software is reliable at arithmetic, formatting and carrying balances forward.
- It cannot decide which adjustments, allowances or reliefs apply to your company.
- Errors in the accounts or in a classification repeat in every later computation.
- Advisory input is most useful during the year, not only at the filing deadline.
- A filing that passes software checks is compliance-ready, but not always compliant.
How Corporate Tax Computation Actually Works
Corporate tax is not simply a percentage applied to accounting profit. It starts from a company's accounting profit and then requires a series of adjustments: adding back expenses that are not tax-deductible, deducting income that is not taxable, applying capital allowances in place of accounting depreciation, and accounting for any available reliefs or incentives the company qualifies for. The result of these adjustments is chargeable income, to which the applicable tax rate is then applied to determine the company's tax liability.
Why the Starting Point Matters as Much as the Adjustments
Because the computation starts from accounting profit, any error or inconsistency in the underlying financial statements carries directly into the tax computation. A misclassified expense, an incorrectly recognized item of income, or an incomplete set of accounts will produce a materially wrong tax computation even if every subsequent adjustment is applied with perfect arithmetic accuracy, which is why the quality of the underlying bookkeeping and accounts matters just as much as the tax-specific rules applied on top of them.
What Corporate Tax Software Handles Well
Once the relevant figures and classifications have been entered correctly, corporate tax software is very good at performing the arithmetic reliably and consistently, applying standard adjustment templates, calculating capital allowances according to prescribed formulas, and generating a formatted computation and supporting schedules ready for filing. This significantly reduces the manual effort and transcription errors that used to be common when computations were built from scratch in general-purpose spreadsheets each year.
Consistency Across Filing Periods
Tax software also tends to carry forward relevant figures from prior periods, such as unabsorbed capital allowances or losses available for carry-forward, reducing the risk that these balances are lost or miscalculated from one year to the next. This continuity is a genuine advantage over manual processes, where prior-year balances sometimes get overlooked or recalculated inconsistently by different preparers.
Built-In Checks for Completeness
Most tax software includes checks confirming that mandatory fields have been completed and that a computation is internally consistent, catching missing information before a filing is submitted. These checks improve the mechanical reliability of a filing, but they do not verify that the categorization decisions behind the numbers were correct in the first place.
Where Corporate Tax Advisory Remains Essential
The judgment calls that software cannot make on its own include:
- Determining whether a specific expense is tax-deductible under the relevant rules
- Identifying which fixed assets qualify for capital allowances, and at what rate
- Assessing whether a company genuinely qualifies for a specific tax incentive or relief scheme
- Interpreting how a company's particular transactions or structure interact with current tax rules
These decisions require someone who understands both the tax rules and the substance of the company's actual business activities. For related reading on where automation still needs a professional review layer, see our comparisons of e-invoicing mandates versus manual invoicing support and digital tax authority portals: global trends.
Classifying Expenses Correctly
Not every expense a company incurs is automatically deductible for tax purposes, and the line between deductible and non-deductible expenses can be nuanced, depending on the nature and purpose of the expenditure. Software will apply whatever classification a user enters without independently verifying it, meaning a systematic misclassification, once entered, will repeat across every subsequent computation until someone with tax expertise reviews and corrects it.
Assessing Eligibility for Reliefs and Incentives
Tax relief schemes and incentives typically come with specific eligibility criteria tied to a company's activities, structure, or investment. Determining whether a company genuinely qualifies, and ensuring the relevant conditions continue to be met over time, requires an ongoing understanding of both the company's operations and the scheme's requirements, since software has no independent way of confirming eligibility beyond what a user tells it.
Interpreting Non-Routine Transactions
Transactions such as asset disposals, restructurings, related-party dealings, or one-off gains and losses often carry tax treatment that depends heavily on the specific facts involved. These are exactly the kinds of transactions where generic software templates are least reliable, since they are, by definition, not the routine, recurring transactions the software's standard workflows are built around.
Group Structures and Related-Party Considerations
Companies that are part of a larger group face additional layers of complexity in their tax computations, including the treatment of intercompany transactions, transfer pricing considerations for related-party dealings, and, in some cases, group relief mechanisms that allow losses or allowances to be shared among group companies under specific conditions. These are areas where the interaction between accounting entries and tax rules is particularly intricate, and software applied without a clear understanding of the group's structure is likely to miss opportunities or misapply available relief mechanisms.
Transfer Pricing Documentation
Related-party transactions, such as intercompany loans, service charges, or the sale of goods between group entities, generally need to be priced and documented in a manner consistent with applicable transfer pricing principles. Preparing this documentation, and ensuring the pricing used in the accounts aligns with what the documentation supports, is a specialized task that sits outside what standard corporate tax computation software is designed to handle, since it depends on comparative analysis and judgment rather than a standard formula.
Group Relief and Loss Utilization
Where a group qualifies for a mechanism that allows current-year losses or unabsorbed allowances to be transferred between related companies, correctly identifying which entities are eligible, calculating the amount available for transfer, and documenting the arrangement appropriately requires coordinated advisory input across multiple entities rather than a single company's computation being handled in isolation.
How Tax Computation Interacts With Financial Statements
A company's tax computation and its financial statements are closely linked but not identical, since accounting profit and taxable income are calculated under different sets of rules. Deferred tax, which reflects the future tax consequences of temporary differences between accounting and tax treatment, needs to be calculated and presented correctly in the financial statements, and this calculation depends directly on the same classification decisions that feed into the tax computation itself.
Deferred Tax Calculations Require Coordinated Judgment
Because deferred tax balances arise from timing differences between when income or expenses are recognized for accounting purposes versus tax purposes, an error in the tax computation's classification of an item will typically also produce an inconsistent or incorrect deferred tax figure in the financial statements. Coordinating these two workstreams, rather than treating tax computation and financial statement preparation as entirely separate exercises handled by different tools without cross-checking, helps ensure the two sets of figures remain internally consistent.
Preparing for Queries From the Tax Authority
Even a carefully prepared corporate tax filing can attract a query from the tax authority, particularly where a claimed deduction, relief, or unusual transaction stands out compared to typical filings in the same industry. Responding to such a query effectively requires being able to explain the reasoning behind specific classification decisions with reference to the applicable rules, not simply pointing to what the software calculated.
Documentation Supporting Judgment Calls
Companies that maintain clear documentation of why a particular expense was treated as deductible, why a specific capital allowance rate was applied, or why a relief was claimed, are in a far stronger position to respond to a tax authority query than those that can only point to a software-generated computation without any record of the underlying reasoning. This kind of documentation is a natural byproduct of a properly conducted advisory review, since the reasoning behind each judgment call is typically recorded as part of that review process.
Common Pitfalls of Relying Solely on Tax Software
A recurring pattern is treating a computation that runs through the software without error as evidence that it is substantively correct. Software validation confirms completeness and internal consistency, not that the underlying classifications and judgment calls were the right ones for the company's specific circumstances. This gap becomes more consequential the more complex or unusual a company's activities are.
Carrying Forward Errors Across Years
Because tax software often carries forward prior-year balances and classifications automatically, an error introduced in one year, whether in an expense classification or a capital allowance calculation, can persist silently across multiple subsequent filings until someone independently reviews the computation history rather than simply trusting the carried-forward figures.
Missing Opportunities for Legitimate Relief
Just as software cannot flag an ineligible relief being claimed incorrectly, it also cannot proactively identify a relief or incentive a company may be entitled to but has not claimed, since it only applies what a user tells it to apply. Companies relying purely on software without periodic advisory review risk both overpaying tax by missing legitimate reliefs and underpaying tax by misapplying rules they do not fully understand.
The Value of Periodic Advisory Review Beyond Annual Filing
Corporate tax advisory is often most valuable not just at the point of filing, but throughout the year, as decisions are made about transactions, investments, and structuring that will eventually flow into the annual computation. Involving advisory input earlier, rather than only at the filing deadline, allows a company to structure transactions in a tax-efficient and compliant way from the outset, rather than discovering after the fact that a different approach would have produced a better or more defensible outcome.
Planning Ahead of Major Transactions
Significant transactions, such as an asset sale, a restructuring, or a new investment, often have tax consequences that are far easier to manage well when advisory input is sought before the transaction is finalized, rather than after it has already occurred and the tax treatment is effectively locked in by the facts. This proactive use of advisory support is a meaningfully different engagement than simply preparing a computation once a year from historical data.
Technology Choices and the Scale of a Business
The right balance between software and advisory input often shifts as a business grows. A small, straightforward company with few transaction types may find that basic software, paired with periodic advisory checks, is entirely adequate. A larger company with multiple revenue streams, related-party transactions, or evolving business activities generally needs more continuous advisory involvement, since the variety and complexity of its transactions increases the number of judgment calls that need to be made correctly each year.
Signs a Business Has Outgrown a Software-Only Approach
Signs that a business has outgrown a purely software-driven approach to tax computation include an increasing frequency of one-off or unusual transactions, expansion into new revenue streams or jurisdictions, or growing group complexity through new subsidiaries or related entities. Businesses that continue relying solely on generic software templates well past this point often find that the computations, while mechanically complete, are increasingly disconnected from the substantive judgment their actual situation requires.
Common Misconceptions About What Software Guarantees
A widespread misconception is that using well-known, reputable tax software guarantees regulatory compliance on its own. Software is a tool for applying rules consistently once those rules have been correctly identified as applicable, it is not a substitute for someone with tax expertise determining which rules apply in the first place. Reputable software reduces the risk of arithmetic and formatting errors, but it does not reduce the risk of misclassification, missed reliefs, or incorrect treatment of non-routine transactions, since those risks depend entirely on the judgment of whoever configures and operates the software.
The Gap Between Compliance-Ready and Compliant
There is a meaningful difference between a filing that is compliance-ready, meaning it is complete, well-formatted, and passes all software validation checks, and one that is actually compliant, meaning every classification and judgment call embedded in it correctly reflects the applicable tax rules as they apply to the company's real circumstances. Software reliably delivers the first outcome; only informed professional review can reliably deliver the second, which is the outcome that actually matters if the filing is ever examined closely by the tax authority.
How Livida Supports Corporate Tax Filing in Singapore
Livida's Corporate Tax service in Singapore is built around the understanding that accurate computation depends on correct classification and judgment applied before the numbers ever reach the software stage. Livida works with a company's underlying accounting records, prepared through its general accounting, bookkeeping, and audit compilation services, to ensure the figures feeding into the tax computation are accurate and properly classified from the outset.
Reviewing Computations for Substance, Not Just Format
Beyond generating a properly formatted computation, Livida reviews the substantive classification decisions behind it, checking that expense treatment, capital allowance claims, and any relief or incentive claims genuinely reflect the company's actual circumstances and current tax rules. This reduces the risk of both under-claimed reliefs and misapplied deductions that a purely software-driven process might not catch. Further detail on corporate tax filing requirements is available directly from the Inland Revenue Authority of Singapore at iras.gov.sg.
Coordinating Tax Filing With Broader Compliance
Because corporate tax computation depends on the same underlying financial statements used for audit compilation and XBRL filing, Livida coordinates its tax advisory work with these related services, reducing the risk of inconsistencies between what is reported to the regulator in financial statements and what is filed with the tax authority.
Using Corporate Tax Software Well
Corporate tax software works best when the inputs are clean and the decisions behind them are documented. Our experience is that most computation problems come from the inputs, not the formulas. In the filings we handle, the most common delay is a classification question that nobody settled before the deadline.
Four habits make corporate tax software far more useful:
- Reconcile the accounts before you start the computation.
- Record why each judgment call was made.
- Review prior-year balances instead of trusting them blindly.
- Ask for advisory input before a major transaction, not after.
Livida supports this through corporate tax filing in Singapore, ACRA annual return filing and virtual CFO advisory. The related post on XBRL automation versus professional XBRL filing covers the filing step that follows.
Building a Sustainable Annual Process
A sustainable approach to corporate tax compliance generally involves establishing a clear division of labor between software and advisory input from the start of the financial year, rather than reserving advisory involvement for a rushed review immediately before the filing deadline. This means flagging non-routine transactions for advisory review as they occur throughout the year, maintaining organized documentation supporting key classification decisions, and scheduling a substantive review of the computation well before the deadline so there is time to investigate and resolve any issues that surface.
Avoiding the Deadline Rush
Companies that leave all tax computation and advisory review to the final weeks before a filing deadline are more likely to accept software defaults under time pressure rather than genuinely investigating an ambiguous classification or an unusual transaction. Spreading advisory input across the year, rather than compressing it into a single pre-deadline review, tends to produce both a more accurate filing and a less stressful process for the finance team involved.
Bringing Software and Advisory Judgment Together
Corporate tax software has made the mechanical side of computing and formatting a company's tax liability considerably faster and more consistent than manual preparation ever was. It has not replaced the professional judgment required to classify expenses correctly, assess eligibility for reliefs, and interpret how non-routine transactions should be treated under current tax rules. Companies that combine efficient software tools with genuine advisory review tend to file more accurate computations and are better positioned to identify legitimate tax planning opportunities along the way.
Businesses weighing this trade-off more generally may also find our framework for choosing between software and managed services useful. Companies looking to review their current corporate tax preparation approach are welcome to reach out to Livida for guidance.
Conclusion
Corporate tax software is a strong engine for computation and filing. Advisory is the judgment layer that decides what goes into it. Used together, they give you a computation that is both complete and defensible.
References
- Corporate Income Tax Filing Season 2026, IRAS
- Preparing a Tax Computation, IRAS
- Basic Guide to Corporate Income Tax for Companies, IRAS
Talk to Livida
If you want a second opinion on how you use corporate tax software, visit our contact page, email info@livida.in or call +91 94860 33194. Our team will review your current computation approach and flag where judgment is needed.
This article is general information, not professional advice. Tax rules, rates, reliefs and deadlines change, so confirm current requirements with IRAS or a qualified adviser before you act.