TDS return filing India is a quarterly duty for every business that deducts tax at source from salaries, rent, contractor bills or professional fees. This guide is for founders, finance heads and accountants who want to know exactly what to file, when to file it and which errors cause notices, mismatched credit and avoidable cost.
By the end you will be able to map each payment to the right statement, follow the deduct, pay, report and certify cycle, and spot eight common mistakes before they reach the Income Tax Department. It is general information drawn from the official sources listed below, not professional advice, and rules change, so confirm current details on incometax.gov.in before you act.
Key Takeaways
- TDS return filing India covers a cycle: deduct, deposit through a challan, report quarterly and issue certificates.
- You need a valid TAN registered on the e-Filing portal before you can file.
- The same four quarterly dates apply to salary and non-salary statements: 31 July, 31 October, 31 January and 31 May.
- From 1 April 2026 the Income-tax Act, 2025 applies, with new section and form numbers but unchanged rates.
- A TDS return correction needs a correction file with a matching RRR number.
In This Article
- What TDS return filing India means
- Who must deduct tax and hold a TAN
- How the TDS cycle works step by step
- Forms and due dates at a glance
- A worked example for a growing business
- TDS challan payment and interest rules
- TDS return correction
- Common mistakes to avoid
- Summary and conclusion
What TDS Return Filing India Means
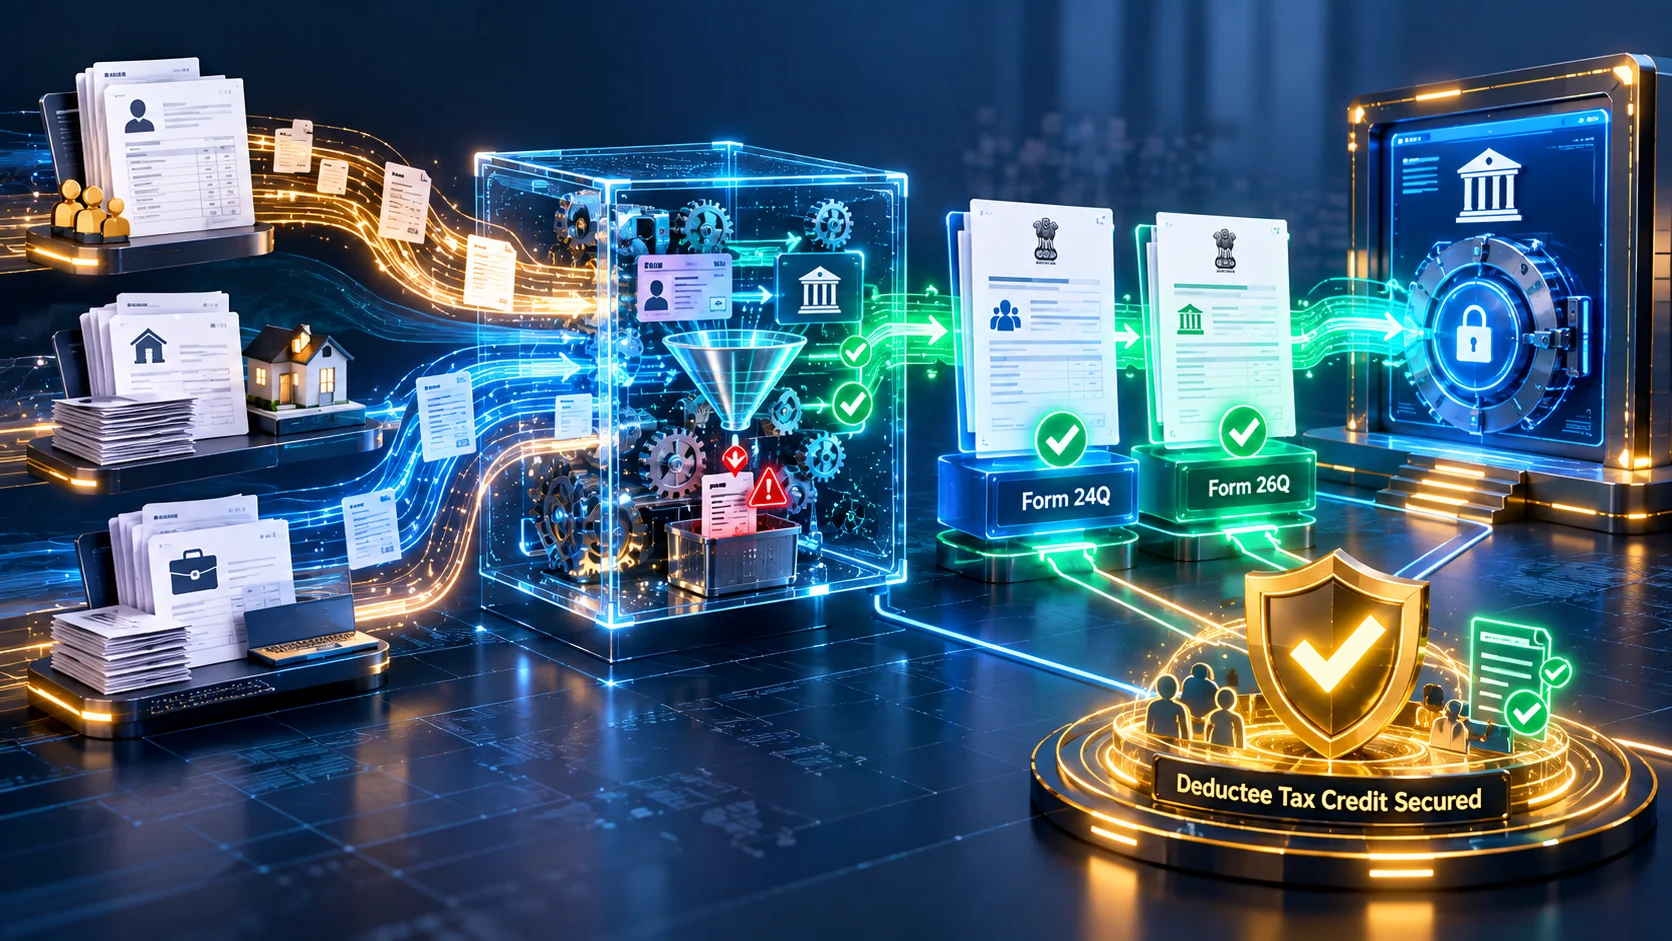
TDS return filing India means reporting to the Income Tax Department, every quarter, the tax you deducted at source on payments such as salary, rent, contractor charges and professional fees. The report is called a quarterly TDS statement. It lists each deduction, each deductee's PAN and the challan used to deposit the tax.
TDS stands for tax deducted at source. The person who pays is the deductor, and the person who receives the payment is the deductee. The deductor withholds a portion of the payment, deposits it with the government, and reports it in a statement. The deductee then claims credit for that tax when filing their own income tax return.
The Income Tax Department runs the system for TDS return filing India wide. TRACES, the TDS Reconciliation Analysis and Correction Enabling System, is the portal where statements are processed and deductees' credits are reconciled. The e-Filing portal at incometax.gov.in accepts the statement files for the newer forms, and the free Return Preparation Utility from NSDL (Protean) prepares and validates them.
In the filings we handle, the most common source of rework is not the filing itself but the data that feeds it, for example a missing PAN or a challan entered against the wrong deductee. That is why this guide spends more time on inputs than on upload steps.
Who Must Deduct Tax and Hold a TAN
A business must deduct tax when it makes a payment that the law lists as subject to TDS, and it must hold a Tax Deduction and Collection Account Number (TAN) to report it. The common triggers are salary, rent, contractor payments, professional fees, commission, interest and payments to non-residents.
A TAN is a ten-character alphanumeric number issued to a deductor. It is different from a PAN. The Income Tax Department lists a valid TAN registered on the e-Filing portal as a prerequisite for filing Forms 138, 140 and 144. Without it you cannot upload a statement or give your deductees credit.
Here is how common payments map to the statement you file:
| Payment type | Who receives it | Statement (earlier name) |
|---|---|---|
| Salary, pension | Employees, pensioners | Form 138 (Form 24Q) |
| Rent, contractor and professional payments | Resident vendors and landlords | Form 140 (Form 26Q) |
| Interest, fees and similar payments | Non-residents | Form 144 (Form 27Q) |
Two points need care in TDS compliance India. First, the thresholds and rates for each type of payment sit in the law and are not repeated here, because they are set by statute and can be amended. The Department's transition FAQ confirms that rates and thresholds are unchanged under the Income-tax Act, 2025, but the sections are now presented in a tabular format. Second, some transactions, such as property purchases or rent paid by individuals, have a separate challan-cum-statement route, which the Department describes under Form 141 for transactions from 1 April 2026.
How TDS Return Filing India Works Step by Step
The TDS cycle has five steps: deduct, deposit, prepare the statement, upload it and issue certificates. Each step has its own deadline and its own failure points. Following them in order is the simplest way to keep your TDS compliance India record clean and your TDS return filing India work on time.
The process runs like this:
- Deduct at the right time. The governing Act depends on the earlier of credit or payment, per the Department's FAQ.
- Deposit the tax. Complete your TDS challan payment and keep the challan details for the statement.
- Prepare the statement. Use the latest Return Preparation Utility from NSDL (Protean), then validate and generate the FVU file.
- Upload and e-verify. Log in with your TAN, choose the form under Deduction and Collection at Source, upload the zipped FVU file and verify.
- Track status and certify. Check View Filed Forms, refile if rejected, then issue certificates to deductees.
FVU stands for File Validation Utility, which checks the file format before upload. The upload steps follow the Department's user manual for Form 140. An accepted form moves to TRACES, and a rejected form carries a reason.
A digital signature certificate (DSC) is needed only if you verify with a DSC, according to the same manual.
TDS Return Filing India: Forms and Due Dates
The quarterly TDS statement has four due dates and three main forms. The Income Tax Department's pages for Forms 138, 140 and 144 list the same dates for each form, so one calendar covers all of them.
| Quarter | Period covered | Due date |
|---|---|---|
| Q1 | April to June | 31 July |
| Q2 | July to September | 31 October |
| Q3 | October to December | 31 January |
| Q4 | January to March | 31 May of the next year |
The forms differ by the payments they cover, not by the dates. Form 138 covers tax deducted on salary, pension or specified interest. Form 140 covers non-salary payments to residents. Form 144 covers non-salary payments to non-residents, such as interest or fees.
Remember the transition for TDS return filing India. The Department's FAQ explains that events on or before 31 March 2026 fall under the Income-tax Act, 1961, while events on or after 1 April 2026 fall under the 2025 Act. The return preparation utilities and TRACES are meant to support both formats during the transition. So a deductor may file a statement in the earlier format for an older quarter and in the new format for a recent one.
A Worked Example for a Growing Business
Consider a software services company, an illustrative case rather than a real client, that pays monthly salaries, rent for its office, fees to a freelance consultant and a licence fee to a non-resident vendor. Each payment belongs to a different statement.
The salaries belong in Form 138, where each employee's deduction, PAN and challan are reported. The office rent and the consultant's fees belong in Form 140, because both are non-salary payments to residents. The licence fee to the overseas vendor belongs in Form 144.
The company's finance team follows a simple monthly routine. It marks each invoice with the section and the deductee's PAN at booking, deducts at payment, deposits the tax, and files the challan reference in a tracker. At quarter end, for its quarterly TDS statement, it exports the tracker into the preparation utility, validates the file and uploads it before the due date.
The same company can go wrong in TDS return filing India in four predictable ways. A new consultant joins without a PAN, so the deduction cannot be matched. The accountant keys an old section number after 1 April 2026. A deposit is made a month late. A challan is reported against the wrong quarter. Each of these problems is described in detail in the mistakes section below.
TDS Challan Payment, Interest and Disallowance
TDS challan payment is the deposit of deducted tax to the government account, and it comes before the statement. The quarterly TDS statement only reports what you have already paid, so late or missing deposits cannot be fixed by filing the return on time.
The Income Tax Department's transition FAQ describes the cost of delay in plain terms. Interest for failure to deduct is 1% per month, and interest for failure to deposit is 1.5% per month, with the deposit interest running from the date of deduction to the date of payment. The FAQ gives an example in which tax deducted in March 2026 was due by 30 April 2026, and a deposit made in May attracted the higher interest.
Under the 2025 Act, the FAQ also notes a disallowance in business income where tax was not deducted or deposited. It cites section 35(b), which disallows 30% of the payable sum in those cases. For payments under the earlier Act, it cites section 271C, a penalty equal to the tax not deducted, along with recovery and interest.
Three practical consequences follow:
- Treat the TDS challan payment date as the real deadline, not the statement date.
- Reconcile each challan to the deductions it covers before preparing the statement.
- Budget for interest, because it accrues monthly from the date of deduction.
For exact due dates for deposits, use the Department's current instructions. We have not quoted a deposit calendar here, because it depends on the type of payment and the month.
TDS Return Correction: How to Fix an Error
A TDS return correction is a statement that amends a statement already accepted by the Department. You file it when a PAN, section, amount or challan detail was wrong in the original. It is not a substitute for a missing statement, and it must be linked to the original.
The Department's user manual for Form 140 gives the mechanics. Choose the Correction upload type, upload a correction FVU file, and make sure the RRR number in the file matches the one entered on the landing screen. The manual lists mixing regular and correction files, and mismatched versions, as common causes of rejection.
A TDS return correction matters beyond tidiness. The transition FAQ says that quoting an old section number after 1 April 2026 may lead to processing errors, and that a correction statement may then be needed. It also says that when a deductee's credit does not match, the deductee should tell the deductor, and the deductor should file a revised statement. Early reconciliation is advised.
The FAQ also states that corrections for older periods continue under the older framework, even if filed after 1 April 2026, and that time limits apply. Because time limits and procedures differ by period, we suggest you review corrections each quarter rather than letting them pile up.
If a credit is missing in a deductee's Annual Information Statement, check the original statement first. Then check the challan, then the PAN. Our TDS return filing service handles this kind of reconciliation and correction work for businesses that do not want to run it in-house.
Common Mistakes to Avoid
These eight mistakes account for most of the notices and credit mismatches in TDS return filing India. Each one has a simple fix, and most can be prevented with a short monthly checklist rather than a year-end scramble.
1. Filing Without a Valid, Registered TAN
The Department's pages for Forms 138, 140 and 144 list a TAN registered on the e-Filing portal as a prerequisite. A business that deducts tax before it has a TAN, or that has not registered it on the portal, cannot upload a statement. Fix: apply for or update the TAN before the first deduction, and register it on the e-Filing portal.
2. Using the Wrong Section or Old Section Numbers
For payments on or after 1 April 2026, the 2025 Act applies. The FAQ maps salary to section 392(1) and consolidates other deductions under section 393, and it warns that old numbers may lead to processing errors. Fix: update your ERP and payroll codes, and review the section for each vendor at the start of each quarter.
3. Deducting but Not Depositing
Deduction without deposit is the most serious error, because interest runs at 1.5% per month from the date of deduction. The FAQ also mentions prosecution risk under the new Act for tax deducted but not deposited. Fix: schedule TDS challan payment as soon as the deduction is booked, and reconcile the ledger every month.
4. Missing or Incorrect PAN of the Deductee
A statement with a wrong PAN cannot give the right person credit. The deductee's own return then shows less tax paid than expected, and the notice comes to both of you. Fix: collect PAN at onboarding, verify it before the first payment and keep it in the vendor master.
5. Challan Details That Do Not Match the Statement
The statement must quote the challan accurately. The FAQ lists a wrong assessment or tax year on the challan or return as a cause of mismatch. Fix: compare challan serial, amount and period against the deduction register before you generate the file.
6. Missing the Quarterly TDS Statement Date
Each quarter has a fixed date. Missing it can bring a per-day late fee under the Act and, in some cases, a separate penalty. We have not quoted the current amounts, because they changed with the Income-tax Act, 2025, and should be checked on the portal. Fix: file at least a week before the date, and never wait for the last evening.
7. Uploading the Wrong File for a Correction
A TDS return correction needs the Correction upload type and a correction FVU, and the RRR number must match. A regular file uploaded in place of a correction is rejected. Fix: keep the original provisional receipt number with the working file, and use the latest utility version.
8. Not Reconciling Credit and Certificates
Filing is not the end. The FAQ notes that a deductee's credit depends on the deductor filing the Q4 statement correctly, and that the earlier Act allows a per-day penalty for failing to issue Form 16A. Fix: review your deductees' credit each quarter, download or issue certificates as the Department instructs, and respond to deductee queries quickly.
Form 16 and Form 16A are the salary and non-salary TDS certificates under the earlier Act. The Department has renumbered many forms under the 2025 Act, so check which certificate name your TRACES login shows.
Choosing How to Handle TDS Compliance India
Most businesses handle TDS compliance India in one of three ways: in-house with spreadsheets, with software, or with a professional filing partner. The right choice depends on how many deductees you have and how much your team can review.
- In-house TDS return filing India: Works when you have a small number of deductees and a trained accountant. The risk is key-person dependence.
- Software: Helps with calculation and file generation. It does not decide which section applies or fix a bad PAN.
- Professional support: Adds review, reconciliation and corrections. It suits growing businesses and those with many vendors.
Our comparison of AI TDS calculators and professional TDS filing sets out where each approach works and where it does not.
TDS rarely stands alone. Salary deductions sit beside provident fund and insurance contributions, so many employers pair this work with PF return filing and ESI return filing. Deductees also need correct credit when they file their own returns, which is why we suggest reading about income tax return filing in India from the receiver's point of view.
Summary
TDS return filing India is a cycle that starts with the right TAN and ends with reconciled credit for every deductee. Deduct under the correct section, deposit on time, report accurately in the quarterly statement and correct errors early with a proper correction file. The new forms and section numbers under the Income-tax Act, 2025 change the labels, not the discipline. Most problems in TDS compliance India come from data entry and timing, so fix the inputs first.
Conclusion
Good TDS return filing India practice is a monthly habit, not a quarterly rush. Confirm your TAN, map each payment to the right form, deposit the tax on time and keep your challan and PAN records clean. When a mistake slips through, file a proper correction promptly.
If you want a second pair of eyes on your deductions, statements or corrections, speak to our team. We can review your last few quarters and tell you where the gaps are.
Talk to Livida
If you want help with TDS return filing India, from reviewing deductions to preparing quarterly statements and corrections, reach us through our contact page, by email at info@livida.in, or by phone at +91 94860 33194. We will look at your situation and explain the options. We do not guarantee outcomes, since assessments and credits are decisions of the tax authorities.
References
- Form 140 user manual: quarterly TDS statement (Income Tax Department)
- Form 138 user manual: TDS statement on salary (Income Tax Department)
- Form 144 user manual: TDS statement on payments to non-residents (Income Tax Department)
- TDS compliance transition FAQs (Income Tax Department)
- TRACES: forms and downloads for TDS deductors (TDS CPC)
- Income Tax Department e-Filing portal
Reviewed for accuracy in November 2026.