Blockchain audit trail technology is often described as a way to make financial records tamper-proof, and for the specific problem it solves, that description is largely accurate. What gets lost in the more enthusiastic pitches is that recording transactions immutably is a different problem from preparing statutory accounts, which requires interpreting those transactions correctly, applying accounting standards, and presenting the results in a format regulators, lenders, and shareholders can rely on. A tamper-proof record of a mistake is still a mistake.

Key Takeaways
- A blockchain audit trail shows that a record has not been changed since it was created. It does not show that the record was right.
- Statutory account preparation applies accounting standards, estimates and disclosures that no ledger can automate.
- A tamper-proof record of a mistake is still a mistake.
- If ledgers became common, a financial statement audit would shift in emphasis. It would not disappear.
- For most growing businesses, accurate bookkeeping and professional review matter more than adopting new ledger technology.
At a Glance: Blockchain Audit Trail vs. Statutory Accounts
| Dimension | Blockchain audit trail | Statutory account preparation |
|---|---|---|
| What it guarantees | A record has not been altered after creation | The statements fairly represent the business under applicable standards |
| Judgment on estimates and disclosures | Not addressed | Central to the process |
| Catches an error made at the point of entry | No | Yes, through professional review |
| Mainstream adoption today | Limited to specific niches | Standard practice for every business |
What a Blockchain Audit Trail Actually Provides
A blockchain audit trail works by recording each transaction as a block that is cryptographically linked to the block before it, using a distributed network of computers to validate and store the chain rather than a single central database. Once a block is added and confirmed by the network, altering it retroactively would require rewriting every subsequent block across a majority of the network's participants, which is computationally impractical at scale.
This structure gives a strong guarantee against retroactive tampering. That is genuinely valuable where trust between parties is limited, or where a shared, verifiable record needs to exist across organizations that do not trust each other's internal systems. A blockchain audit trail is a meaningful advance in record integrity, and it deserves to be evaluated on that basis rather than dismissed as hype or oversold as a complete accounting solution.
Where This Technology Is Actually Being Used
Distributed ledger technology has found real traction in specific niches: cross-border payment settlement, supply chain provenance tracking where multiple unrelated parties need to agree on a shared record, and some specialized trade finance applications. These are cases where the core problem is establishing trust between parties with no existing relationship, which is exactly what a distributed, tamper-evident ledger is built to solve.
Mainstream small and mid-sized business accounting has not seen anywhere near the same level of adoption, largely because most businesses do not have a trust problem between untrusted external parties. They have an internal process problem: making sure their own bookkeeping is accurate and their own statements are properly prepared.
What a Blockchain Ledger Does Not Solve
Immutability Is Not the Same as Accuracy
The most important limitation of blockchain accounting technology is that it guarantees a record has not been changed after it was created, not that the record was correct when it was created. If a transaction is entered with the wrong amount, posted to the wrong account, or reflects a mischaracterized arrangement between related parties, a blockchain ledger will faithfully preserve that error forever, in exactly the same tamper-proof way it preserves a correct entry. Immutability protects against a specific kind of fraud, retroactive alteration, but it does nothing to catch the far more common problem of an honest mistake or a misapplied accounting judgment made at the point of entry.
Judgment Cannot Be Encoded Into a Ledger
Statutory account preparation involves a long list of judgment calls that have no purely mechanical answer: how to value inventory, when to recognize revenue on a long-term contract, how to estimate a provision for doubtful debts, and how to disclose a contingent liability that may or may not materialize. None of these questions can be resolved by a distributed ledger, because they are not disputes about whether a transaction happened. They are questions about how to interpret and present a transaction under a specific accounting framework, and that interpretation is exactly the kind of professional work a blockchain cannot automate.
Five Limits of a Blockchain Audit Trail
A blockchain audit trail is useful, but five limits matter most for statutory reporting:
- It cannot confirm that an entry was correct when it was first recorded.
- It cannot decide how to value, classify or disclose a transaction.
- It does not produce statements in the format regulators and lenders expect.
- It does not settle differences in accounting standards between countries.
- It still needs governance, because someone must approve what is written to the chain.
None of these limits makes the technology useless. They simply show where a blockchain audit trail ends and where professional preparation begins.
Why Businesses Get Excited About This Technology Anyway
It is worth acknowledging why blockchain audit trail concepts generate so much interest despite the practical limits described above. Financial fraud involving altered or backdated records is a real and recurring problem, and the idea of a ledger that makes retroactive tampering computationally impractical is genuinely appealing to anyone who has dealt with a dispute over what a record originally said. Vendors selling blockchain-based accounting tools understandably lean into this appeal, sometimes implying a broader guarantee of accuracy and compliance than the technology can actually deliver on its own.
The honest version of the pitch is narrower but still valuable: if a business's core problem is proving that a record has not been altered after the fact, distributed ledger technology addresses that problem well. If the business's core problem is making sure its bookkeeping was accurate in the first place, applying the right accounting treatment, and preparing statements that satisfy regulators and stakeholders, then a blockchain ledger is, at best, a data source feeding into a process that still requires professional expertise to complete correctly.
Comparing the Two Directly
Placed side by side, a blockchain audit trail and traditional statutory account preparation are answering different questions entirely. The ledger answers, has this record been changed since it was created. Statutory account preparation answers, does this set of financial statements fairly and correctly represent the business's financial position according to the applicable accounting standards, with appropriate classification, estimates, and disclosures. A business can have a perfectly tamper-proof record of transactions and still produce statutory accounts that are materially wrong, because the wrongness was baked in at the point of initial classification, not introduced through later alteration.
This is why framing the comparison as blockchain versus professional preparation is somewhat misleading. It is closer to comparing a bank vault to an accountant. The vault protects what is inside it from being tampered with. It has no opinion on whether what was placed inside was correct to begin with, and it certainly cannot organize that contents into a statement that satisfies a regulator's disclosure requirements. Both have value, but they are not substitutes for each other, and treating the vault as a replacement for the accountant misunderstands what each one actually does.
Statutory Account Preparation in Practice
Statutory account preparation involves compiling a business's financial data into the specific format required by the relevant regulatory or corporate framework, applying consistent accounting policies, and ensuring the statements include the disclosures stakeholders are entitled to see. This is detailed, standards-driven work that depends on understanding both the client's business and the applicable accounting framework, whether that follows local generally accepted accounting principles or an international standard such as those published by the IFRS Foundation.
In our experience, the problems that cause the most rework in statutory accounts are ordinary ones. They include misclassified entries, missing accruals and incomplete disclosures. A tamper-proof ledger would not have prevented any of them.
Livida's preparation of general and special purpose statutory accounts, along with annual financial statement preparation and our statutory audit readiness review service, follows this standards-based approach regardless of what underlying transaction system a client uses. For a wider view of how records and reporting fit together, see our Virtual CFO Advisory service.
Preparing statutory accounts, whatever the source system, generally involves:
- Compiling the general ledger, trial balance, and supporting schedules into primary statements
- Applying consistent accounting policies across the reporting period
- Exercising judgment on estimates, provisions, and disclosures where standards allow interpretation
- Reviewing the underlying data for accuracy before it is presented in a formatted set of statements
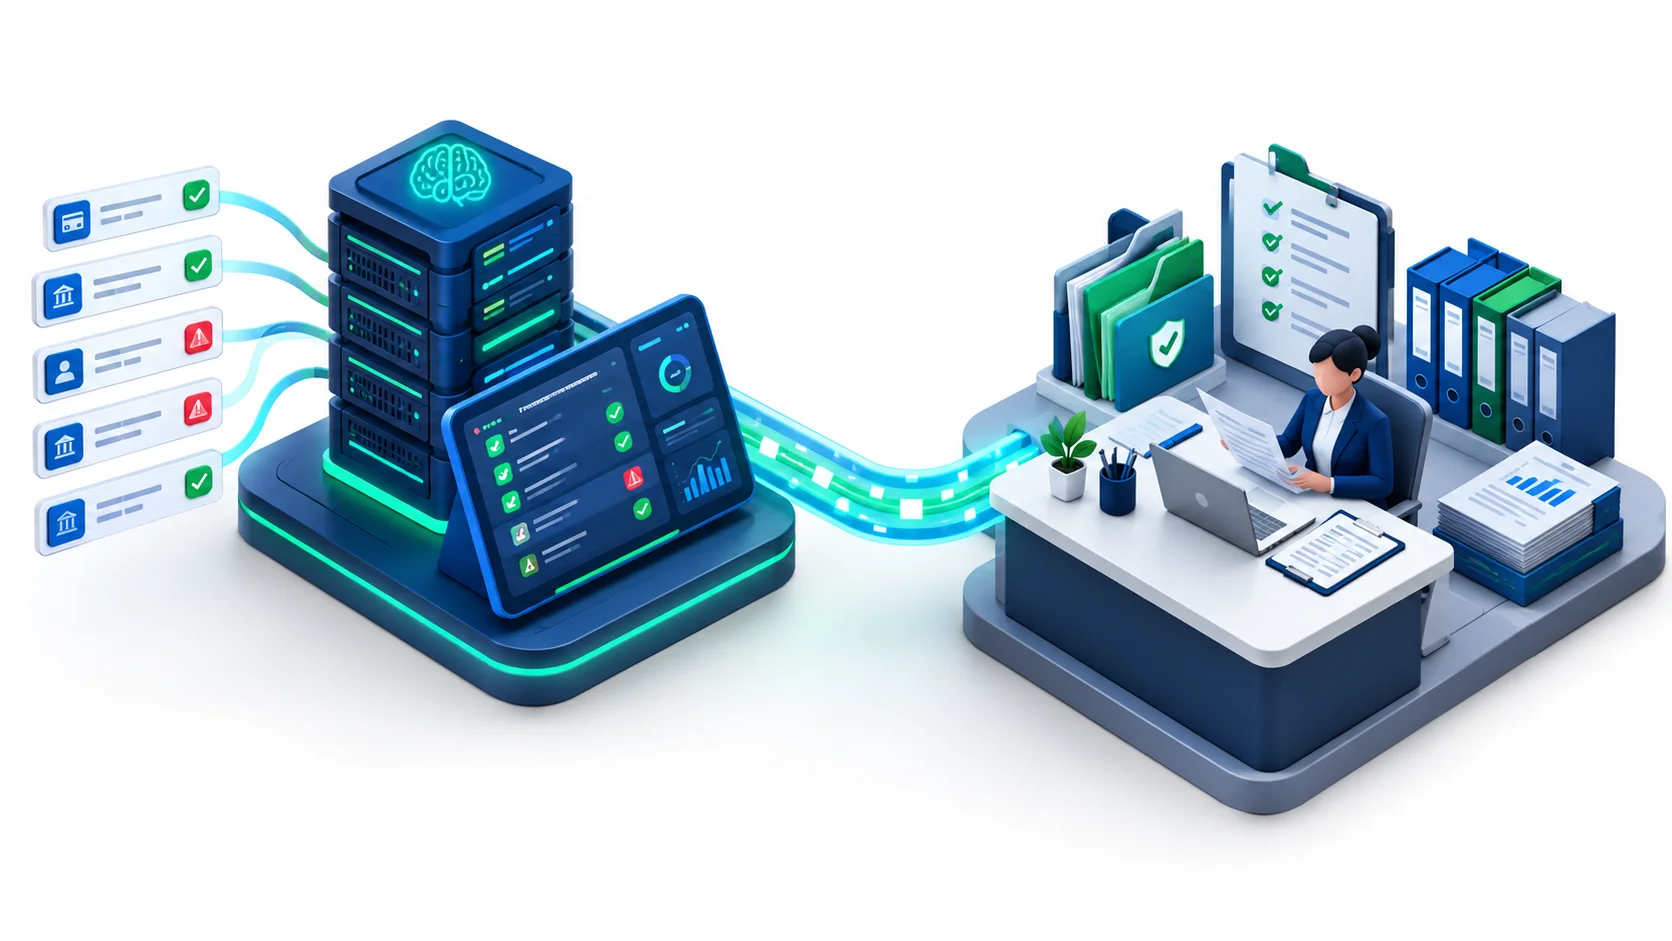
Whether the source data comes from a conventional cloud accounting platform or, in principle, from a distributed ledger, the professional work of classifying, presenting, and disclosing that data according to accounting standards remains the same.
The ledger technology changes how the raw data is stored and verified. It does not change what needs to happen to turn that data into a compliant set of statutory accounts.
How a Financial Statement Audit Would Actually Change
If blockchain-based record keeping became mainstream, it would likely change the emphasis of a financial statement audit rather than eliminate it. Auditors currently spend meaningful effort verifying that recorded transactions actually occurred and have not been altered, work that a reliable blockchain audit trail could genuinely streamline. But an audit is not only a search for tampering. It also evaluates whether management's estimates are reasonable, whether transactions have been classified consistently with accounting standards, and whether the financial statements as a whole present a fair view of the business's position.
None of that evaluative work goes away simply because the underlying transaction data is stored on an immutable ledger. If anything, a verified and complete transaction history could let auditors spend proportionally more time on the judgment-heavy parts of an audit, since less effort would go toward confirming that records have not been altered after the fact. That would be a meaningful efficiency gain, but it is an evolution of audit practice, not a replacement for it.
Practical Barriers to Wider Adoption
Beyond the conceptual limits, there are practical reasons distributed ledger technology has not become a standard tool for everyday business accounting. Implementation requires technical expertise most small and mid-sized businesses do not have in-house, and the accounting profession, standard setters, and tax authorities have been cautious about how blockchain-recorded transactions map onto existing reporting and audit frameworks. There is also a real cost consideration: maintaining or participating in a distributed ledger network is not free, and for most businesses the trust problem it solves does not exist in a form that justifies that cost over simply using established, well-audited cloud accounting software.
Regulatory clarity also lags the technology. Tax authorities and standard setters are still working through how transactions recorded on a distributed ledger should be treated for reporting and audit purposes, and businesses adopting the technology ahead of that clarity take on a degree of interpretive risk that a conventional accounting setup does not carry. This regulatory caution is a reasonable reason for most businesses to wait rather than an indictment of the technology itself.
Cross-Border Reporting and Consolidation Complexity
Businesses operating across multiple jurisdictions face an added layer of complexity that neither a blockchain ledger nor any single piece of software resolves on its own: different countries apply different accounting standards, disclosure requirements, and statutory formats. A consolidation of accounts across entities in different regions requires translating figures into a common framework, applying consistent policies across all entities, and eliminating intercompany transactions correctly, all of which depend on professional judgment about how each jurisdiction's rules interact with the group's overall reporting.
A tamper-evident ledger recording the underlying transactions in each entity does nothing to resolve these cross-border presentation questions. If anything, the more distributed and international a business's operations become, the more the value shifts toward the professional layer that can navigate multiple regulatory frameworks consistently, rather than toward any single record-keeping technology, however secure. This is one of the clearer illustrations of why immutability and compliance are separate problems that happen to both involve financial data.
Governance and the Human Layer Around Any Ledger
Even in the specific use cases where distributed ledger technology has found real adoption, human governance remains essential. Someone still has to decide what counts as a valid transaction before it is written to the chain, someone has to manage access to whichever systems interact with the ledger, and someone has to interpret what a recorded transaction means for financial reporting purposes. A ledger without governance around it is not inherently safer than a conventional database; it simply moves the point of vulnerability from "can the record be altered after the fact" to "was the record correct and appropriately authorized when it was first created."
This is a subtle but important distinction. Businesses sometimes treat "blockchain-based" as shorthand for "more trustworthy" without examining what specific problem the technology solves in their particular context. A conventional, well-controlled accounting system with strong access controls, regular reconciliation, and professional review can be just as trustworthy in practice as a distributed ledger, because the trust in either case ultimately depends on the governance and expertise applied around the technology, not on the technology alone. Our look at cloud document management versus statutory records covers the same point for stored records.
Where a Blockchain Audit Trail and Statutory Accounts Meet
The realistic picture is not blockchain versus statutory account preparation as competing alternatives. It is blockchain as a potential future data source feeding into the same professional preparation process that exists today.
A business using distributed ledger technology for a specific use case, such as verifying a supply chain transaction, still needs that transaction properly classified and reflected in its statutory accounts, and still needs a professional to make the judgment calls the ledger cannot make on its own. The technology changes how confidently a business can trust that a recorded transaction has not been altered; it does not change what needs to happen to that transaction on its way into a compliant financial statement.
This means the practical advice for most growing businesses today is straightforward: focus on getting the fundamentals of accurate bookkeeping and disciplined statutory account preparation right, using well-established cloud accounting tools, rather than adopting blockchain infrastructure in search of a trust guarantee most businesses do not actually need yet.
If and when distributed ledger technology becomes a mainstream part of business record keeping, the professional layer of interpretation, classification, and disclosure will still be necessary on top of it.
What This Means for Growing Businesses Today
For now, the sensible approach is to treat blockchain audit trail technology as an interesting and, in specific contexts, genuinely useful tool for establishing trust in transaction records between parties, while recognizing that it does not replace the professional judgment required to prepare compliant statutory accounts, a theme also explored in our comparisons of audit compilation software against professionally managed audit compilation and AI versus human judgment in accounting.
Businesses should be skeptical of any pitch suggesting that adopting a distributed ledger removes the need for professional accounting oversight, since that claim conflates two different problems: verifying that a record has not changed, and correctly interpreting what that record means under accounting standards.
A more productive question for most growing businesses to ask is not whether to adopt blockchain accounting technology, but whether their current bookkeeping, reconciliation, and statutory reporting processes are as accurate and well-controlled as they need to be. For the overwhelming majority of businesses, the biggest source of risk in their financial statements today has nothing to do with retroactive tampering and everything to do with ordinary classification errors, missed estimates, or incomplete disclosures, which is precisely the risk that professional review, not ledger technology, is designed to address.
Conclusion
Blockchain accounting technology solves a real problem, tamper-evident record keeping, and it does so well in the specific contexts where trust between unrelated parties is the central issue. It does not solve the separate problem of correctly classifying transactions, applying accounting judgment, and preparing statutory accounts and financial statements that meet regulatory and stakeholder expectations. That work remains squarely professional, regardless of what underlying technology stores the transaction history, and no amount of cryptographic verification changes what accounting standards require of the people preparing and reviewing the final statements.
Livida's approach to statutory account preparation and annual financial statements is built on established accounting standards and professional review, which means it applies consistently whether a client's data comes from conventional cloud accounting software or from any future ledger-based system. If your business is evaluating new record-keeping technology, it is worth having a conversation about how that technology fits alongside, rather than instead of, the professional preparation your statutory accounts still require.
It is also worth remembering that regulators, lenders, and shareholders are not asking whether a business's transaction history is technically tamper-evident. They are asking whether the financial statements in front of them fairly represent the business, whether the estimates and judgments behind those statements are reasonable, and whether the disclosures give a complete picture of the risks and obligations involved. Those are the questions statutory account preparation exists to answer, and no ledger technology, however secure, changes what it takes to answer them properly. A business that gets this balance right treats new technology as an input to a well-run professional process, not as a shortcut around it.
We recommend judging any blockchain audit trail proposal against one question: which specific accounting problem does it solve for us? If the answer is only "tampering", check whether tampering is a real risk in your business before paying for a solution.
References
- NIST: Blockchain, an overview of blockchain as a tamper-resistant distributed ledger and NIST's related publications.
- IFRS Foundation, the body that develops international accounting standards.
- Institute of Chartered Accountants of India, the statutory body for the accounting profession in India, which publishes accounting and auditing standards.
Talk to Livida
If you are weighing new record-keeping technology against your statutory reporting needs, our team can help you think it through. Use the contact page, email info@livida.in or call +91 94860 33194.
This article is general information, not professional advice. Accounting standards and regulations change, so confirm current requirements before you act.