Audit compilation software has changed how many accounting teams approach the task of turning raw bookkeeping records into a formatted, standards-compliant set of financial statements, automating templates, standard note disclosures, and basic consistency checks that used to be built manually from scratch each year. For companies preparing for a statutory audit or an exemption-based filing, this raises a practical question: once software can generate a professional-looking set of financial statements quickly, how much value does professionally managed audit compilation still add on top of what the software already produces?

Key Takeaways
- Audit compilation software speeds up formatting, templates and standard notes. It does not check that the figures are right.
- Professional audit compilation starts by verifying the trial balance before any statements are built.
- Judgment areas such as leases, provisions and revenue recognition need a person who knows the company's facts.
- Disclosures should reflect the real circumstances of the company, not generic template wording.
- Start early, so there is time for a genuine review before an audit or filing deadline.
This article is general information, not professional advice. Accounting standards and filing rules change, so confirm the current position for your own company.
| Dimension | Audit compilation software | Professionally managed audit compilation |
|---|---|---|
| Formatting and templates | Fast, consistent, automated | Same efficiency, applied by the reviewer |
| Verifying the trial balance is accurate | Not performed | Core part of the review |
| Judgment-intensive items (leases, provisions, revenue recognition) | Cannot determine the correct treatment | Assessed against the company's actual facts |
| Disclosures | Generic template wording | Tailored to the company's real circumstances |
What Audit Compilation Actually Involves
Audit compilation software is only one part of the picture. Compilation itself is a larger task than formatting.
Compilation is the process of taking a company's underlying accounting records, its general ledger, trial balance, and supporting schedules, and presenting them as a complete set of financial statements: a statement of financial position, a statement of comprehensive income, a statement of changes in equity, a cash flow statement, and the accompanying notes required under applicable accounting standards. This is distinct from an audit, which involves independent testing and verification of those records, though compiled statements are typically the starting point that an auditor then examines.
Why Compilation Matters Even Without a Full Audit
Companies that qualify for audit exemption based on their size or structure still generally need properly compiled financial statements, since these statements support tax computations, inform decisions made by directors and shareholders, and are often requested by banks, landlords, or other stakeholders assessing the company's financial position. The absence of a statutory audit requirement does not remove the need for the underlying statements to be accurate and properly presented.
How Audit Compilation Software Works
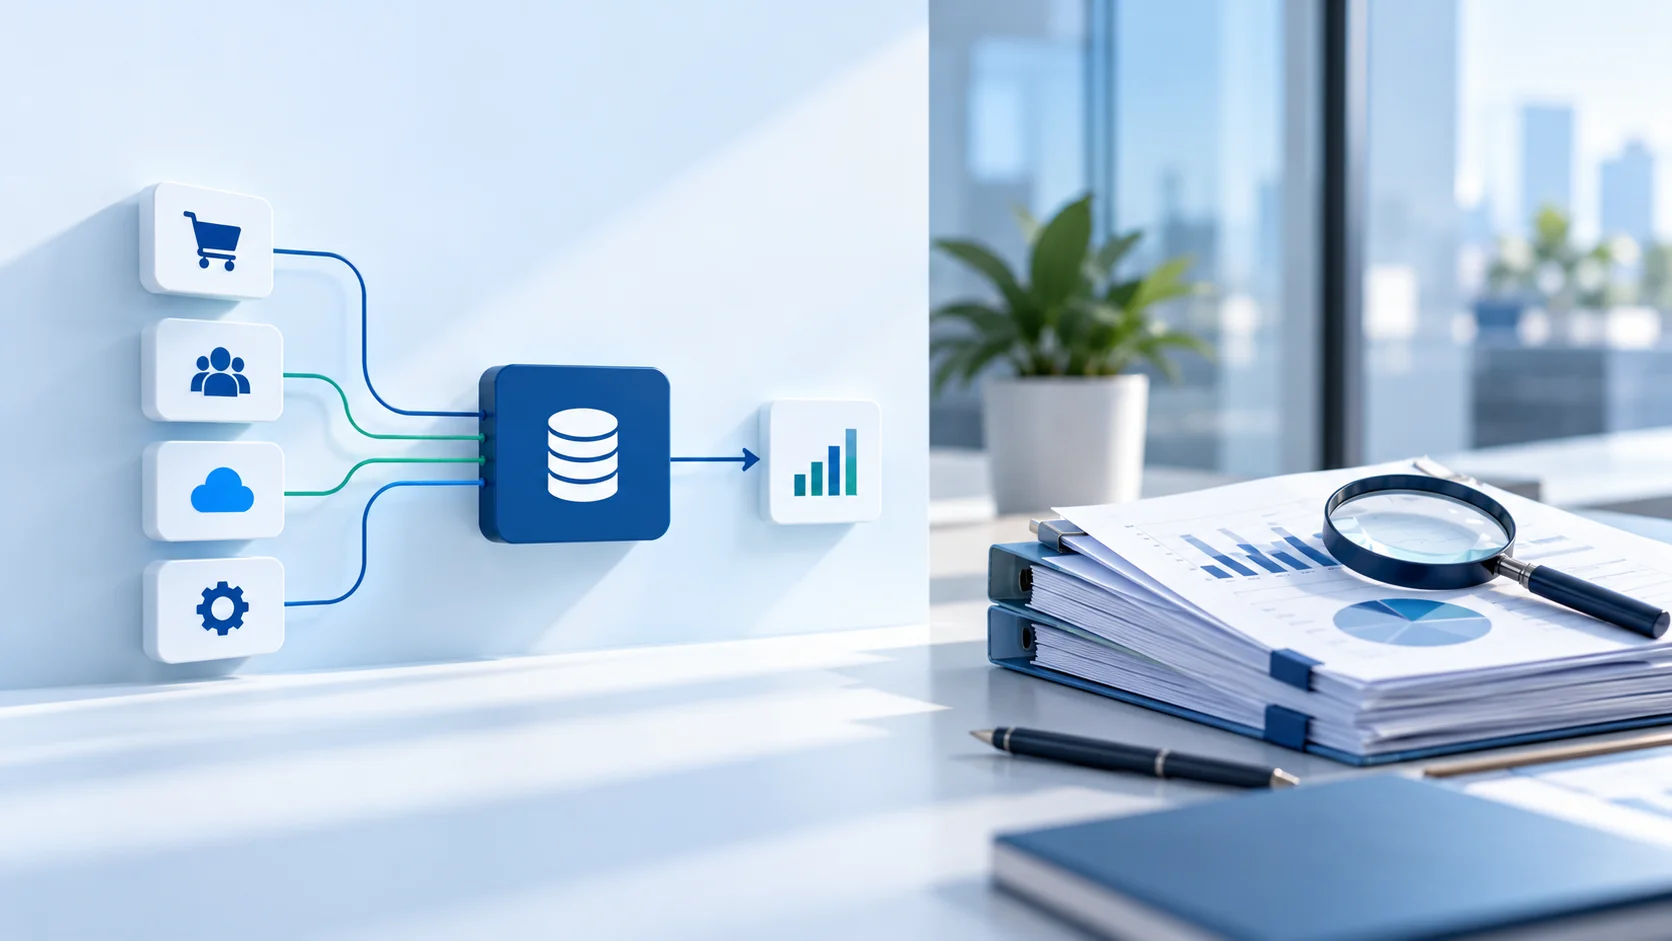
Compilation software typically imports a trial balance or general ledger export from a company's accounting system, maps account balances to standard financial statement line items, and applies templates for the required primary statements and common note disclosures. Many tools include libraries of standard disclosure wording that can be selected and adapted, reducing the time spent drafting notes from scratch each year.
Automated Consistency and Formatting Checks
These tools generally check that the statement of financial position balances, that figures are consistently presented across primary statements and supporting notes, and that mandatory disclosures have not been omitted based on the template selected. This catches a meaningful category of presentation errors that used to slip through when statements were built manually in general-purpose spreadsheet software without built-in cross-referencing.
What the Software Cannot Verify
Compilation software has no independent way of confirming that the trial balance it has been given is itself accurate, that account balances have been classified correctly, or that unusual transactions have been presented in a manner consistent with applicable accounting standards. It processes whatever data and classifications it receives, formatting them consistently, without judging whether the substance of that data is correct. That is the central limit of audit compilation software.
What Compilation Software Genuinely Improves
For companies with straightforward, well-organized accounting records, compilation software has made the process of generating a formatted set of financial statements considerably faster than building them manually. Standard templates reduce formatting inconsistencies, built-in disclosure libraries reduce the risk of omitting a commonly required note, and automated balancing checks catch transcription errors that used to be common when statements were assembled by hand.
Time Savings on Repetitive Elements
Much of financial statement preparation involves repetitive elements that do not change significantly from year to year, such as standard accounting policy disclosures or the basic structure of the primary statements. Automating these repetitive elements frees up time that can be redirected toward reviewing the more judgment-intensive aspects of the statements, provided that time is actually used for review rather than treated as time saved overall. Audit compilation software saves effort. It does not save the need for review.
Where Professional Judgment Remains Essential
The parts of compilation that require professional judgment include:
- Verifying that the underlying trial balance is accurate and complete
- Classifying unusual or non-standard transactions correctly
- Determining appropriate accounting treatment for leases, provisions, or revenue recognition where standards allow for interpretation
- Ensuring disclosures genuinely reflect the company's specific circumstances rather than generic template language
This starts with verifying that the underlying trial balance is accurate and complete, a task that depends on understanding the company's specific transactions and business activities well enough to recognize when something looks wrong. Similar judgment questions come up in our comparison of blockchain-based audit trails against traditional statutory account preparation, where the same distinction between mechanical record-keeping and professional interpretation applies.
Verifying the Underlying Trial Balance
A trial balance that has been generated from a poorly maintained set of books, with unreconciled accounts, misclassified transactions, or incomplete records, will produce compiled financial statements that are formatted correctly but substantively wrong. Professional review at this stage, checking the trial balance itself before compilation proceeds, is one of the most important safeguards against presenting inaccurate statements in a polished, professional-looking format.
Judgment-Intensive Accounting Areas
Certain accounting areas, including revenue recognition for complex contracts, lease classification, provisions and contingencies, and the valuation of certain assets, involve applying professional judgment within a range permitted by accounting standards, rather than a single mechanical calculation. Software can apply a chosen treatment consistently once it is specified, but it cannot determine which treatment is actually appropriate for a company's specific facts and circumstances.
Tailoring Disclosures to Reflect Real Circumstances
Generic disclosure templates cover common scenarios well, but a company with unusual financing arrangements, related-party transactions, or subsequent events occurring after the year-end needs disclosures that are specifically tailored to those circumstances rather than adapted loosely from a standard template. Getting these disclosures right requires someone who understands both the applicable standards and the specific facts of the company's situation during the relevant period.
Group Companies and the Added Layer of Consolidation
Companies that are part of a group generally need consolidated financial statements in addition to standalone statements for each entity, and consolidation introduces its own set of judgment-intensive tasks: eliminating intercompany balances and transactions, adjusting for any non-controlling interests, and ensuring that accounting policies are applied consistently across all entities being consolidated. Compilation software can mechanically combine figures once told how entities relate to one another, but it cannot independently identify which intercompany transactions need to be eliminated or verify that each subsidiary's figures have been prepared on a consistent basis before consolidation begins.
Aligning Accounting Policies Across Entities
A common issue in group consolidation is that different subsidiaries, particularly those acquired at different times or operating in different jurisdictions, may have historically applied slightly different accounting policies or estimates. Before consolidation can produce a meaningful, accurate set of group financial statements, these policies need to be aligned, which is a substantive accounting exercise rather than a data-merging task that software can perform on its own without guidance on what needs to be adjusted.
Subsequent Events and Their Impact on Compiled Statements
Financial statements need to reflect material events occurring between the year-end date and the date the statements are finalized, where those events provide additional evidence about conditions that existed at year-end or indicate a significant new development. Identifying which subsequent events are material enough to warrant disclosure or adjustment, and determining the correct treatment, requires judgment that depends on understanding the nature of the event and its relationship to the company's financial position, not something a compilation tool can assess independently from a trial balance alone.
Why This Is Easy to Overlook
Because subsequent events by definition occur after the accounting records for the year have already been finalized, they are easy to overlook if the compilation process is treated purely as a mechanical exercise of formatting existing trial balance data. A professional compiler actively asks about developments since year-end as part of the compilation process, rather than relying solely on what happens to already be reflected in the accounting system.
Related-Party Transactions and Disclosure Accuracy
Transactions with related parties, such as shareholders, directors, or affiliated companies, typically require specific disclosure under applicable accounting standards, including the nature of the relationship and the terms of the transactions involved. Identifying which transactions actually qualify as related-party transactions, particularly where relationships are indirect or not clearly flagged in the underlying accounting records, requires an understanding of the company's ownership and management structure that goes beyond what a compilation tool can infer from account codes alone.
The Risk of Incomplete Related-Party Disclosure
Incomplete or inaccurate related-party disclosures are a common finding during audits and can raise questions about the broader reliability of a company's financial statements, even where the core figures themselves are accurate. Ensuring these disclosures are complete and correctly described is a detail-oriented task that benefits significantly from professional familiarity with the company's structure and history, rather than being left to whichever related-party transactions happen to be flagged automatically in the accounting system.
Common Pitfalls in Software-Only Compilation
A frequent issue is treating a compiled set of statements that balances correctly and includes all standard disclosures as evidence that the statements are substantively accurate. Balancing and completeness checks confirm internal consistency and template compliance, not that the classifications and judgment calls behind the numbers were correct for the company's actual circumstances.
Carrying Forward Prior-Year Templates Without Review
Because compilation software often carries forward the prior year's template and disclosure choices, an outdated or slightly incorrect classification from a previous period can persist across multiple years of statements if nobody independently reviews whether the company's circumstances have changed enough to warrant a different treatment.
Missing Changes in Applicable Standards
Accounting standards are periodically updated, and a company relying on software templates that have not been refreshed to reflect a recent standard update risks presenting financial statements that no longer comply with current requirements, even though the software itself continues to function and produce a balanced, complete-looking set of statements.
Accounting System Reviews and Compilation Quality
An accounting system review examines the processes, controls, and data quality that ultimately feed into the compilation process, and weaknesses identified during such a review, such as inconsistent transaction classification, unreconciled accounts, or gaps in supporting documentation, often explain why the same compilation issues recur year after year despite using the same software. Addressing these underlying process issues tends to improve compilation quality more durably than simply reviewing each year's statements in isolation after the fact.
Breaking the Cycle of Recurring Errors
Companies that experience the same type of compilation issue repeatedly, such as a recurring reconciliation gap in a particular account, often benefit more from a targeted accounting system review addressing the root cause than from an increasingly detailed annual review of the symptom each year. This is a case where investing in the underlying process pays off more than repeatedly correcting the same downstream error.
Comparing Compilation Quality Across Different Tools and Providers
Two companies using the same compilation software, starting from similarly structured accounting records, can still end up with meaningfully different quality outcomes depending on how carefully the compilation was reviewed by the person or team responsible for it. This is because the software provides structure and consistency, but the substantive accuracy of the result depends on the reviewer's diligence in checking the underlying figures, applying judgment to ambiguous items, and tailoring disclosures appropriately, none of which the software itself can guarantee regardless of which vendor's tool is used. Audit compilation software gives structure, not assurance.
Why Vendor Choice Is Not the Deciding Factor
Businesses sometimes assume that switching to a more sophisticated or expensive compilation software package will automatically improve the quality of their financial statements. In practice, the software mainly affects the efficiency and consistency of formatting and template application, while the accuracy of the substantive content depends primarily on the expertise and diligence of whoever reviews the compiled output before it is finalized, which is a separate consideration from which software tool happens to be used. Better audit compilation software helps with speed. People provide the accuracy.
First-Time Compilation for Newly Established Companies
A newly incorporated company preparing its first set of financial statements faces a distinct set of considerations, including establishing an appropriate accounting policy framework from the outset, ensuring opening balances are correctly stated, and setting up a chart of accounts that will support clean compilation in future years. Decisions made at this early stage tend to have a lasting effect on how smoothly subsequent years' compilations proceed, making professional input particularly valuable during a company's first compilation cycle.
Avoiding Structural Problems That Compound Over Time
A poorly structured chart of accounts or an inconsistent approach to classifying transactions from a company's earliest days can create structural problems that become progressively more difficult and costly to correct as the company grows and accumulates several years of financial history built on that same inconsistent foundation. Addressing this early, with professional guidance on how to structure the underlying records, is considerably more efficient than attempting a large-scale correction years later once problems have compounded across multiple reporting periods.
How Livida Supports Audit Compilation in Singapore
Livida's Audit Compilation service in Singapore, which sits alongside the use of audit compilation software, combines the efficiency of standard compilation tools with professional review of the underlying trial balance, judgment-intensive accounting treatments, and disclosure accuracy. Rather than treating compilation as a purely mechanical formatting exercise, Livida's approach starts by confirming that the accounting records feeding into the compilation are reliable, drawing on its broader general accounting and bookkeeping services where those records originate from Livida's own work. This coordinates closely with a company's ACRA annual return and corporate tax filing obligations, since all three draw on the same underlying financial statements.
Coordinating Compilation With Consolidation and XBRL Filing
Since compiled financial statements often need to be consolidated for group reporting and subsequently tagged for XBRL filing, Livida coordinates its compilation work with these related services to ensure consistency across the full reporting chain, from the underlying trial balance through to the final filed statements. Guidance on statutory financial reporting expectations in Singapore is available from the Accounting and Corporate Regulatory Authority at acra.gov.sg.
Preparing Statements That Hold Up Under Audit Scrutiny
Because compiled statements often form the starting point for a statutory audit, Livida's review process is designed to anticipate the kinds of questions an auditor is likely to raise, addressing potential issues during compilation rather than leaving them to surface, and potentially delay the audit, once fieldwork has already begun.
Timing Considerations Ahead of an Audit or Filing Deadline
Compiling financial statements too close to a filing or audit deadline leaves little room to investigate unusual items, resolve reconciliation gaps, or seek clarification on ambiguous transactions before the deadline arrives. Starting the compilation process earlier in the reporting cycle, with the underlying trial balance reviewed well before the statements need to be finalized, gives professional reviewers the time needed to catch and resolve issues properly rather than making rushed judgment calls under deadline pressure. Audit compilation software does not change that timetable.
Building in Time for a Genuine Review
A compilation timeline that only accounts for how quickly the software can generate a formatted output, without allowing separate time for a substantive professional review of that output, tends to produce statements that look complete but have not actually been checked as carefully as they should be. Building a realistic buffer into the compilation schedule, informed by how long a proper review genuinely takes rather than just the software's processing speed, is a simple but often overlooked way to improve overall statement quality. Teams that rely on audit compilation software should plan for this review from the start.
Conclusion
Audit compilation software is a useful tool for formatting and consistency. Professional audit compilation is what makes the numbers dependable. Use both, and plan time for the review.
What We See in Practice
In the compilation work we support, the most common delay is an unreconciled trial balance. Our team finds that fixing the books first saves more time than any template does.
We recommend a first read of the trial balance before any statements are generated. Audit compilation software then does what it is good at, with fewer surprises later.
Balancing Efficient Tools With Professional Oversight
Audit compilation software has genuinely improved the speed and formatting consistency of preparing financial statements, and there is no reason for companies to give up these efficiency gains. What the software cannot replace is the professional judgment needed to verify that underlying records are accurate, apply the right treatment to judgment-intensive accounting areas, and tailor disclosures to a company's actual circumstances rather than generic templates. Companies that pair efficient compilation tools with genuine professional review tend to produce financial statements that are not just well-formatted, but substantively reliable. Companies preparing their next set of financial statements are welcome to reach out to Livida to discuss how this combined approach could support their compilation process.
References
Official sources for Singapore financial statement requirements:
- ACRA: Audit exemptions and the small company concept
- ACRA: Financial statements filing requirements and exemptions
Exemption criteria and filing formats can change, so check ACRA's current pages before relying on them.
Talk to Livida
If you want a second pair of eyes on your trial balance before compilation, our team is ready to help. Visit the contact page, email info@livida.in or call +91 94860 33194. You may also like our related guides on XBRL automation vs professional XBRL filing and consolidation software vs professional consolidation of accounts.