Consolidation of accounts software has become the default starting point for groups trying to bring together the financial statements of multiple entities into one coherent picture. It promises to automate currency translation, combine trial balances, and speed up a process that used to take weeks of spreadsheet work.
For a business with subsidiaries, joint ventures, or entities in more than one country, the appeal is obvious. There is less manual data wrangling and faster turnaround on group reporting. The harder question is whether that software alone produces consolidated financial statements a board, lender, or auditor can actually rely on. Or does it need a professional layer of review sitting on top of it?
This article is general information, not professional advice, and accounting and regulatory rules change, so check the current position for your own group.

| Consolidation of Accounts Software | Professionally Managed Consolidation | |
|---|---|---|
| Handles | Currency translation, combining trial balances, draft eliminations | Judgment calls, intercompany investigation, policy consistency |
| Cannot do alone | Determine why an intercompany balance doesn't match | Process high transaction volume as fast as software |
| Best used as | Infrastructure for the mechanical work | The review layer that makes the output defensible |
| Risk if used alone | Clean-looking statements with buried unresolved differences | Slower, harder to scale without software support |
Key Takeaways
- Consolidation of accounts software automates the mechanics well, including currency translation and combining trial balances.
- It cannot explain why an intercompany balance does not match.
- Judgment calls on joint ventures, acquisitions and goodwill stay with people.
- A group is only as reliable as its weakest entity's books.
- Most groups do best with software as infrastructure and a professional team reviewing the exceptions.
What Is Consolidation of Accounts Software?
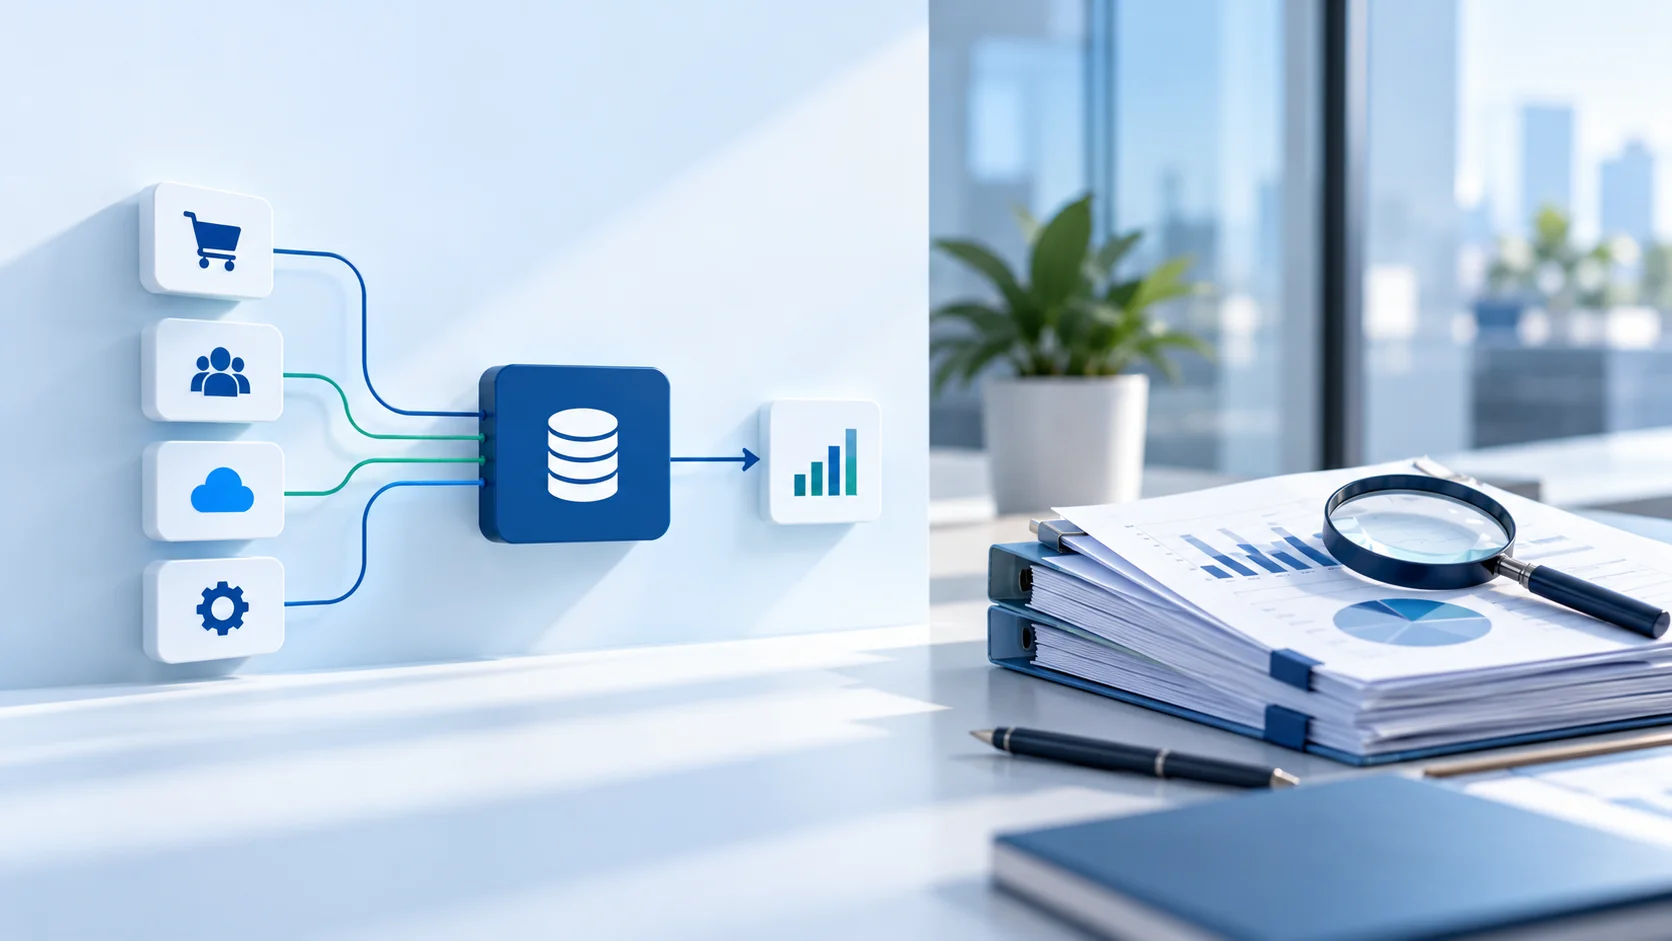
At its core, consolidation of accounts software pulls trial balances or general ledger data from each entity in a group, converts foreign currency balances at appropriate exchange rates, and combines the results into a single set of group figures. Most platforms also include built-in workflows for identifying and eliminating intercompany transactions. They apply standard chart-of-account mappings across entities that may use slightly different local structures. They also generate the consolidated statements themselves, including a group balance sheet, income statement, and cash flow statement.
The more capable platforms extend further, offering audit trails that show exactly which entity-level figures rolled up into each consolidated line, and scenario tools that let a finance team model what a consolidated result would look like under different ownership or currency assumptions. This is meaningfully useful infrastructure. It has replaced a lot of the manual spreadsheet linking that used to make group consolidation such a slow, error-prone exercise every reporting period.
Common Features Across Modern Platforms
Most consolidation of accounts software shares a similar core feature set:
- Automated currency translation using period-end or average rates
- Intercompany matching tools that flag balances that do not agree
- Ownership and minority interest calculations for partial-ownership groups
- Reporting templates aligned to common accounting frameworks
- Drill-down functionality tracing a consolidated figure back to its source
This is valuable both for internal review and for satisfying an external auditor's questions. For related reading, our comparisons of cloud ERP platforms versus professional bookkeeping and audit compilation software versus professional audit compilation cover similar software-versus-oversight trade-offs.
None of these features are conceptually new. Group consolidation as an accounting exercise has existed for as long as groups of related companies have needed combined financial statements. What software has changed is the speed and consistency of the mechanical steps. That is a genuine improvement. But, as with most financial automation, it is an improvement in execution rather than in judgment.
How Group Financial Consolidation Works in Practice
Combining Entity Data and Applying Consistent Policies
The starting point for any group financial consolidation is getting clean, comparable data out of every entity, which sounds simple but rarely is. Entities acquired at different times, operating in different countries, or historically run somewhat independently often use different account structures, different depreciation policies, or different revenue recognition approaches. Software can enforce a standard chart-of-account mapping. But someone still needs to confirm that each entity's local accounting policy is either consistent with group policy or has been properly adjusted before consolidation. That step is more judgment than mechanics.
Currency Translation and Its Hidden Complexity
Currency translation looks like a simple mathematical exercise, applying an exchange rate to convert one currency into another, but the rules around which rate to use for which account, and how to handle the resulting translation adjustment, are genuinely technical. Getting this wrong does not usually produce an obviously implausible number. It produces a plausible-looking number that is quietly incorrect. That is exactly the kind of error that survives until an auditor or a careful review catches it.
Where Consolidation Software Falls Short
The Intercompany Reconciliation Problem
Intercompany reconciliation is where consolidation of accounts software tends to reveal its limits most clearly. The software can flag that two related entities recorded a balance that does not match. It cannot on its own determine why the mismatch exists. The cause might be a timing difference, a currency translation issue, or a genuine posting error at one of the entities. Resolving that question requires someone who understands both entities' books well enough to trace the discrepancy back to its source. That task remains stubbornly manual even inside the most sophisticated platforms.
Judgment Calls the Software Cannot Make
Beyond intercompany reconciliation, consolidation involves judgment calls that no software can fully automate: whether a joint venture should be consolidated fully, proportionally, or accounted for using the equity method; how to treat a mid-year acquisition or disposal; and how to allocate goodwill and purchase price adjustments correctly following an acquisition. These are accounting policy decisions with real consequences for the consolidated statements. Getting them wrong does not show up as an error message in the software. It shows up as a misstated group financial position that surfaces later, often during an audit.
Data Quality Depends on the Weakest Entity
A consolidation is only as reliable as its least reliable input, and multi-entity financial reporting is particularly exposed to this risk because one poorly maintained subsidiary's books can distort the entire group's consolidated figures. Consolidation software has no way of independently verifying that an entity's underlying bookkeeping is accurate. It simply combines whatever data it is given. A group relying purely on software without a review layer at each entity level can end up with clean-looking consolidated statements. Those statements may rest on at least one set of unreliable underlying books.
What Professionally Managed Consolidation Adds
Entity-Level Review Before Consolidation
A professionally managed consolidation of accounts process starts before the group-level work even begins, with a review of each entity's underlying bookkeeping and trial balance to confirm it is complete and accurately categorized. This is the same discipline behind Livida's general accounting services and accounting system reviews. It is applied at the entity level so that what feeds into the group consolidation is already reliable. In our experience, the most common delay in group closes is an entity whose trial balance arrives late or unreconciled. Our team therefore reviews each entity first.
Resolving Intercompany Differences
Where software flags an intercompany mismatch, a managed process supplies the person who actually investigates it: contacting the relevant entity's finance contact, tracing the underlying transactions, and determining the correct treatment before the elimination entry is finalized. This intercompany reconciliation work is genuinely time-consuming. It is also exactly the kind of task that produces materially different consolidated results, depending on whether it is done carefully or rushed through at period end.
Applying Consistent Accounting Policy Across the Group
A managed consolidation service also takes ownership of ensuring every entity applies consistent accounting policy, or that legitimate local differences are properly adjusted for at the consolidation stage. This includes decisions about revenue recognition timing, asset capitalization thresholds, and how non-controlling interests are presented, all of which require someone with enough seniority and cross-entity visibility to make a consistent call rather than letting each entity's local preference flow through unchecked.
Producing Statements That Hold Up to Scrutiny
Beyond the mechanics, a managed process is what stands behind the final consolidated financial statements when a board, lender, or auditor asks questions about how a particular figure was derived. Livida's approach to consolidation of accounts, alongside annual financial report preparation and audit compilation, is built around producing statements the group can defend, not just numbers that reconcile mathematically inside a piece of software.
Data Security, Access, and System Continuity
A less discussed but genuinely practical concern with consolidation of accounts software is what happens to years of consolidated history if a group needs to switch platforms, or if a vendor changes its pricing, support model, or functionality in ways that no longer fit. Consolidation software stores not just current-period data but the historical mappings, elimination rules, and ownership structures built up over many reporting cycles. Migrating that cleanly to a new system is rarely a simple export-and-import exercise. Groups that build their entire consolidation process around a single vendor's platform can find themselves with limited leverage if that vendor's roadmap or terms change unexpectedly.
A professionally managed consolidation relationship tends to be more portable, because the accounting expertise and the documented process, not the specific software license, are the foundation of the service. The underlying platform can be replaced or upgraded. A competent team adapts the workflow around the new tool without disrupting the group's reporting cadence. It also keeps institutional knowledge about why certain elimination entries or policy adjustments exist. This matters more than it might initially seem, particularly for groups that have been consolidating the same set of entities for several years and have accumulated a fair amount of entity-specific nuance in how figures get treated.
There is also an access and control dimension worth considering. Consolidation software typically requires broad access to sensitive financial data across every entity in a group, which raises questions about who can see what, how permissions are managed as staff change, and how audit trails are preserved if someone needs to review who made a particular adjustment. A managed process brings governance discipline to these questions, ensuring that access is reviewed periodically and that changes to consolidation entries are properly documented and attributable, rather than leaving those controls entirely to whatever the software's default settings happen to provide.
Integration Challenges Between Entity Systems and Group Consolidation
In principle, consolidation of accounts software should connect cleanly to whatever accounting system each entity uses locally. It should pull trial balances automatically without manual intervention. In practice, these integrations are uneven. This is especially true where entities were acquired at different times or run on different local platforms for regulatory reasons. A subsidiary using a locally mandated accounting system in one country may not integrate directly with the group's chosen consolidation software, requiring a manual export and import step that reintroduces exactly the kind of manual error the software was meant to eliminate.
Even where integrations exist, chart-of-account mappings can drift out of alignment as either side updates its accounts over time. Figures may then be silently misdirected into the wrong consolidated line. Someone needs to check the mapping against actual results periodically. This is precisely the kind of gap a periodic accounting system review is designed to catch, comparing a sample of entity-level figures against where they landed in the consolidated statements to confirm the mapping is still working as intended rather than assuming it is.
For groups adding a new entity, whether through acquisition or a new market entry, the integration challenge repeats itself from scratch, since a newly added entity has no existing mapping history and needs its chart of accounts reconciled against group standards before its first consolidated close. This onboarding work is easy to underestimate. It is one of the more common reasons a group's first post-acquisition consolidation takes noticeably longer than a routine period.
Consolidation of Accounts Software vs. Professional Management
For most groups, the realistic answer is not software instead of professional oversight but software as the infrastructure a professional team uses to work faster and more consistently. Consolidation of accounts software handles the mechanical heavy lifting: currency translation, combining trial balances, generating draft eliminations, and producing templated reports. A professionally managed process then applies the review, judgment, and investigation that keeps those mechanical outputs accurate, particularly around intercompany reconciliation and accounting policy consistency.
This combination consistently outperforms either extreme. Software alone, without review, produces consolidated statements that look complete but may carry unresolved intercompany differences or inconsistent policy treatment buried inside them. A fully manual process without any consolidation software is slow, difficult to scale as the group adds entities, and more prone to simple mechanical errors like a currency conversion mistake. The middle path, software for volume and consistency with a professional team reviewing and resolving the exceptions, produces group financial consolidation that is both fast and defensible.
What This Looks Like Each Reporting Period
Five checks keep a consolidation of accounts software workflow dependable:
- Close and review each entity's books locally before they feed the group.
- Confirm the chart-of-account mapping still lands figures in the right consolidated line.
- Investigate every flagged intercompany difference before posting eliminations.
- Check that local accounting policies match group policy or are adjusted.
- Review the final statements before they go to the board or auditors.
In practice, a well-run setup has each entity's books reviewed and closed locally first, feeding clean trial balances into the consolidation software. The software then handles currency translation and produces draft eliminations, flagging any intercompany balances that do not match. A managed consolidation team investigates and resolves those flags, applies any policy adjustments needed, and reviews the resulting consolidated statements before they go to the board or external auditors. This is the same principle behind proper audit preparation at the entity level: the cleaner the process feeding into consolidation, the less friction there is when the group statements face outside scrutiny.
How This Plays Out Across Different Business Types
The demands on group financial consolidation shift depending on where a group's entities are located and how they are structured. A group with a Singapore holding entity consolidating subsidiaries needs statements that satisfy local audit compilation and annual financial report preparation requirements, which is a more specific bar than simply combining numbers that look reasonable. A group with entities across India, the United States, and Canada needs consolidation software and processes flexible enough to absorb each jurisdiction's local accounting quirks, from GST and TDS considerations in India to sales tax and Form 1099 reporting in the United States, without those local requirements distorting the group-level picture.
Groups with a UAE entity focused purely on bookkeeping, alongside operating entities elsewhere, need to make sure that entity's records are just as clean as any other before they roll into consolidation, since a consolidation process is only as strong as its weakest contributing entity. The common thread across all of these structures is that consolidation software handles the combining mechanics well, but someone with visibility across the whole group needs to own the accuracy and consistency of what goes into it.
Choosing the Right Approach for Your Group
The right approach depends on how many entities are involved, how much intercompany activity happens between them, and how much scrutiny the consolidated statements will face from lenders, investors, or regulators. Before committing budget to a new consolidation of accounts software platform, it is worth mapping out exactly which of these mechanical and judgment tasks the tool will actually handle, since the marketing around any given product tends to blur that line. A group with two or three entities and minimal intercompany activity might manage with lighter oversight for a while.
A group with frequent intercompany transactions, multiple currencies, or entities in different regulatory environments accumulates exactly the kind of complexity that software alone handles unevenly, and the cost of an unresolved reconciliation issue surfacing during an audit usually far outweighs the cost of proper review throughout the year.
Frameworks published by standards bodies such as the IFRS Foundation provide the accounting basis most group consolidations are built on, and staying aligned with that guidance is considerably easier when a qualified team is interpreting it consistently across every entity rather than leaving each subsidiary to apply its own reading. Software helps a group move faster through the mechanics. A managed process is what keeps the result accurate enough to stand behind.
Conclusion
Consolidation of accounts software is not a passing trend, and the efficiency gains it offers for combining entity data and handling currency translation are real and worth using. What it has not changed is the need for a qualified team to review each entity's underlying books, investigate intercompany differences properly, and apply consistent accounting policy across a group before the consolidated statements go out the door.
Livida's consolidation of accounts services are built around that combination: modern tools for the mechanical work, paired with the professional review that catches what the software alone would miss. Groups weighing this decision more broadly may also find our framework for choosing between software and managed services useful. If your group is weighing how much of its consolidation process to automate and how much to keep under managed review, that is worth mapping out before your next reporting deadline rather than during it. We also cover related automation questions in our comparison of XBRL automation versus professional XBRL filing.
References
- IFRS 10 Consolidated Financial Statements, IFRS Foundation
- Accounting and Corporate Regulatory Authority (ACRA), Singapore
Talk to Livida
To discuss how your group could split work between software and review, contact Livida in Singapore, email info@livida.in or call +91 94860 33194. Our Singapore corporate secretarial and Singapore ACRA annual return services often sit alongside group reporting work.