Low-code ERP integration has become one of the fastest ways for growing businesses to connect their enterprise resource planning system with the other software running their operations, from accounting platforms to customer relationship tools. The appeal is obvious: less developer time, faster deployment, and a visual interface that lets operations or finance staff build connections themselves. What gets less attention is what a low-code integration cannot do, which is evaluate whether the financial processes and controls behind those connected systems are actually sound. That is a different job entirely, and it belongs to a professional accounting system review.

Key Takeaways
- Low-code ERP integration moves data quickly. It does not judge whether the financial logic is sound.
- An accounting system review checks controls, structure and reporting accuracy.
- Automated errors repeat on every transaction, so they can stay hidden for months.
- Document, test in parallel and assign an owner for every integration.
- Schedule a review after any significant integration project.
What Is a Low-Code ERP Integration, Exactly?
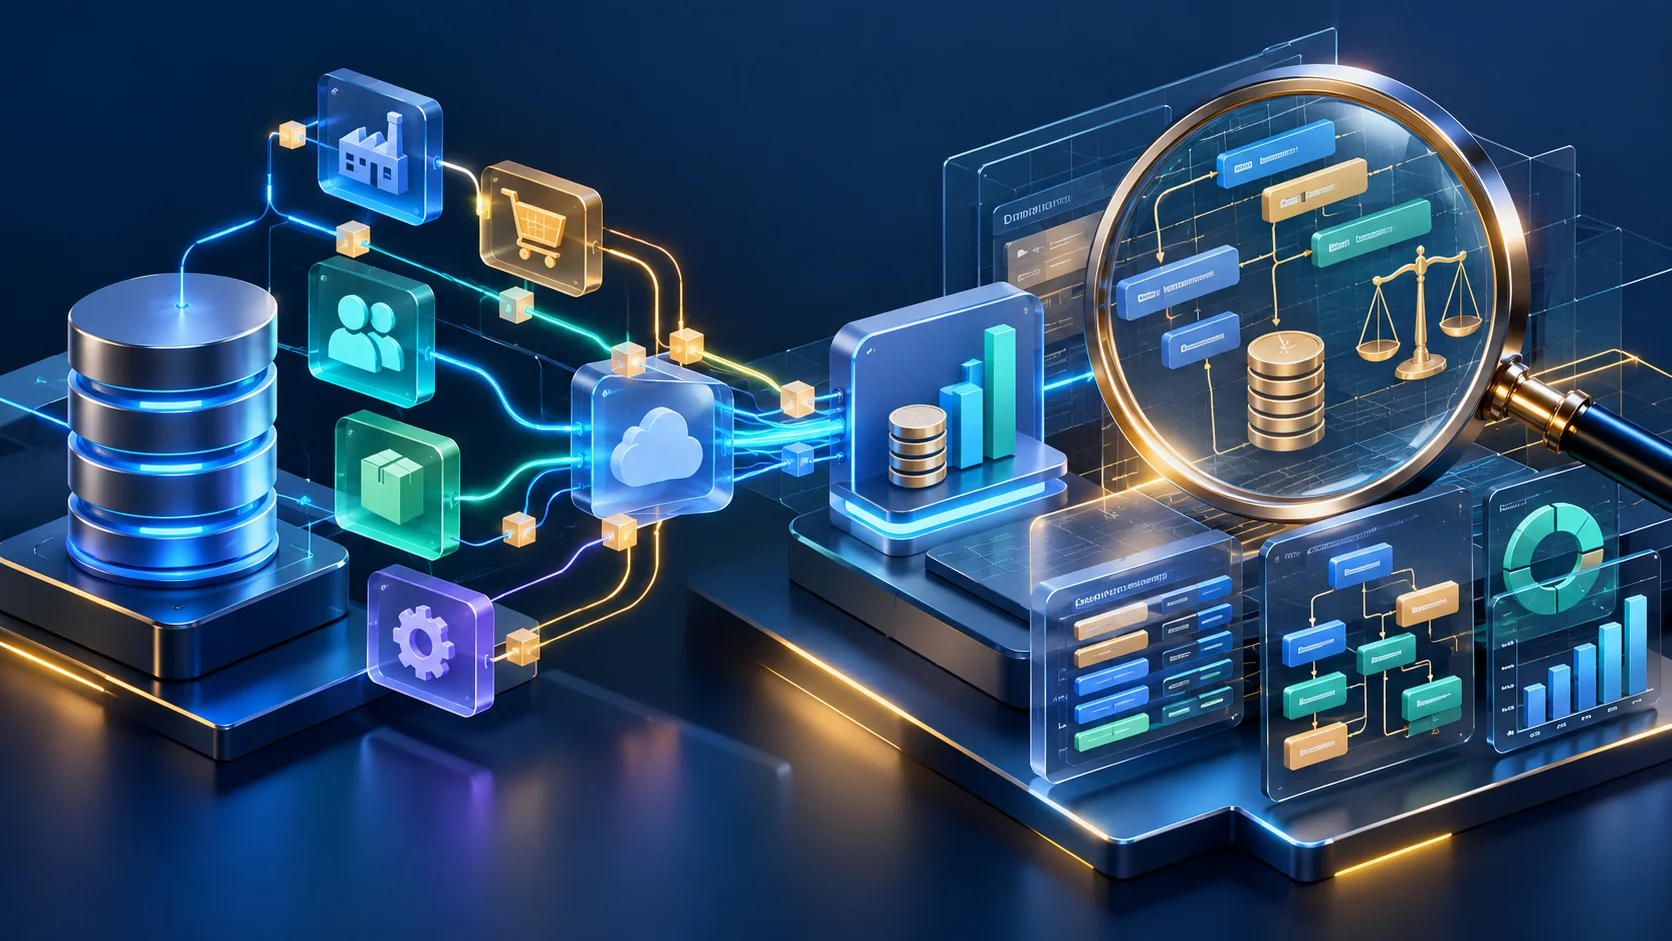
A low-code ERP integration platform provides a visual, often drag-and-drop interface for connecting an ERP system to other software without writing extensive custom code. Instead of a developer building a bespoke connector from scratch, a business user configures pre-built connectors, maps fields between systems, and sets rules for when and how data should flow, such as syncing a new sales order into the accounting ledger automatically. The technology has matured considerably, and platforms now support fairly sophisticated logic, conditional triggers, and error handling within that same visual framework.
Why Businesses Are Drawn to Low-Code Platforms
The appeal is straightforward: speed and accessibility. A finance or operations team can prototype and deploy an integration in days rather than waiting weeks for a development team to become available. This matters enormously for growing businesses juggling limited technical resources against a growing list of software tools that all need to talk to each other. Reduced dependency on scarce developer time also means integrations can be adjusted quickly as business needs change, rather than requiring a formal development cycle for every small modification.
The Learning Curve Is Real, Just Lower
It would be a mistake to assume low-code means no expertise required. Building a reliable integration still requires understanding how data flows between systems, what happens when a record fails validation, and how to prevent duplicate or orphaned records. The barrier to entry is lower, not eliminated, and businesses that treat these platforms as entirely self-service without any oversight tend to discover the gaps later, usually when a report does not reconcile.
How the Technology Has Evolved
Early integration platforms were often rigid, offering only a handful of pre-built connectors and limited ability to handle exceptions gracefully. Modern low-code ERP integration tools have moved well beyond that, supporting conditional logic, multi-step workflows, and increasingly sophisticated error handling within the same visual interface. This evolution is part of why adoption has accelerated so quickly among growing businesses that previously would have needed a custom development project to achieve the same result. The convenience is real, but so is the temptation to build faster than the underlying financial logic is actually understood.
What an Accounting System Review Actually Examines
An accounting system review is a fundamentally different exercise from an ERP integration. Rather than connecting two systems, a professional accounting system review evaluates whether the chart of accounts is structured logically, whether internal controls prevent or catch errors, whether reporting processes produce accurate and timely output, and whether the overall system supports the business's current size and complexity. It looks at the financial logic underneath the software, not just the software itself.
The Scope of a Professional Review
A thorough accounting system review typically covers account structure and coding consistency, the strength of approval workflows for transactions, how well reconciliations are performed and documented, whether reporting outputs match what management and stakeholders actually need, and how the system handles the specific complexities of the business, such as multiple entities, currencies, or revenue types. This scope goes well beyond what any integration tool, however capable, is designed to assess.
Why This Matters More as Systems Get More Connected
As businesses connect more systems together through integrations of any kind, the accounting system sits at the center of an increasingly complex web of data flowing in from sales, inventory, payroll, and other sources. A periodic accounting system review becomes more valuable, not less, in this environment, because it is the mechanism that confirms all of that incoming data is landing correctly and being reported accurately, regardless of how many different tools fed into it.
Who Typically Performs This Kind of Review
An accounting system review is generally carried out by a qualified accounting professional rather than an internal IT resource, precisely because the assessment centers on financial logic, controls, and reporting accuracy rather than technical connectivity. This does not mean IT has no role; understanding how systems technically connect is often relevant context for the review. But the judgment calls at the center of the exercise, such as whether an approval workflow provides adequate segregation of duties, sit squarely within accounting and financial control expertise.
Where Low-Code ERP Integration Genuinely Shines
To be fair to the technology, low-code ERP integration solves real problems well. It is genuinely effective at eliminating manual double-entry between systems, reducing the delay between an event happening in one system and being reflected in another, and giving non-technical staff the ability to adjust simple business logic without submitting a ticket and waiting. For straightforward, well-defined data flows, such as syncing customer records or basic sales transactions, these platforms perform admirably and free up staff time for higher-value work.
Businesses that adopt low-code integration thoughtfully, with proper testing and a clear owner for maintaining the connections, tend to see real efficiency gains. The technology is not the problem; the problem arises when speed and convenience are mistaken for a substitute for financial oversight, which is a distinct and equally necessary function.
A Practical Scenario: How the Two Approaches Play Out
Consider a hypothetical growing business that has just connected its ERP system to its accounting platform using a low-code integration, automating what used to be a manual weekly data entry task. The integration works well from a technical standpoint: orders sync, invoices generate, and staff save several hours a week that used to go into re-keying the same information twice. On the surface, everything looks like a clear win.
Several months later, during a routine accounting system review, a professional review uncovers that a subset of transactions involving partial refunds were being mapped incorrectly, understating revenue in one reporting category and overstating it in another. The totals still reconciled at a high level, which is why nobody had noticed, but the underlying detail was wrong in a way that would have mattered for tax reporting and for any lender examining the business's financials closely. The integration had done exactly what it was built to do; it simply had not been built to catch this category of exception, and nothing about the automation would have surfaced the problem without a separate review of the financial logic behind the numbers.
This kind of scenario illustrates the core argument of this piece without needing to invent statistics or specific outcomes: automation and review solve different problems, and skipping one in favor of the other leaves a real gap regardless of how well the other one performs.
Where Low-Code Integrations Fall Short
Data Integrity Risks
Automated data flows are only as good as the mapping and validation rules behind them. A field mapped incorrectly, a currency conversion handled inconsistently, or a status update that fails silently can introduce errors that compound over time, since the integration keeps repeating the same mistake on every transaction until someone notices. Because the process is automated, these errors often go undetected far longer than a manual entry mistake would, precisely because nobody is manually reviewing each transaction as it passes through.
Compliance and Audit Trail Gaps
Integrations built quickly through a low-code interface do not always preserve a clear, auditable trail of how and when data moved between systems. For a business preparing statutory accounts, undergoing an external audit, or responding to a regulator, gaps in that trail can create real problems, even when the underlying transactions themselves were accurate. A financial systems audit conducted after a significant integration project often surfaces exactly this kind of documentation gap.
The Illusion of Completeness
Perhaps the subtlest risk is psychological rather than technical. Once data flows automatically between systems, it can create a false sense that everything is being handled correctly, simply because nobody has to touch it manually anymore. That sense of completeness is not the same as verified accuracy, and businesses that stop periodically checking their numbers because "the integration handles it" are taking on risk they may not have consciously chosen.
Low-Code ERP Integration vs Accounting System Review: Different Jobs
It helps to be explicit about what each approach is actually for. A low-code ERP integration moves and synchronizes data between systems efficiently. An accounting system review evaluates whether the financial processes, controls, and outputs built on top of that data are structurally sound. Neither one substitutes for the other, and treating them as competing choices misses the point: they address different layers of the same overall financial infrastructure, and a mature, well-run business generally needs both operating well.
A useful way to think about it is that ERP integration is about plumbing, getting data from one place to another reliably, while an accounting system review is about the structural inspection of the building the plumbing runs through. Good plumbing does not mean the building's foundation and wiring are also sound, and a solid foundation does not fix leaking pipes. Both need separate attention.
| Low-Code ERP Integration | Accounting System Review | |
|---|---|---|
| What it does | Moves and syncs data between systems | Evaluates controls, structure, and reporting accuracy |
| Who typically performs it | Operations or finance staff using a visual platform | A qualified accounting professional |
| Primary output | Faster, automated data flow | Findings on control gaps and reporting integrity |
| When it's needed | Whenever systems need to talk to each other | Periodically, and after any significant system change |
Financial Systems Audit Considerations When Adopting New Tools
Whenever a business adopts a significant new ERP integration, it is worth stepping back and considering the broader financial systems audit implications rather than only focusing on whether the connection technically works. Questions worth asking include whether the integration changes how transactions are approved or reviewed, whether it affects the segregation of duties that controls typically rely on, and whether reporting outputs still tie back cleanly to source documents. These questions matter regardless of how well the integration performs its narrow technical function.
Standards bodies and professional accounting organizations publish frameworks that address exactly these kinds of internal control and financial reporting considerations as systems evolve. Reviewing published guidance from a body such as the International Financial Reporting Standards Foundation can be a useful reference point for businesses thinking through how system changes should be reflected in their broader financial reporting approach, particularly for businesses operating across multiple jurisdictions with varying reporting requirements.
A financial systems audit conducted after a significant integration is also a natural moment to revisit whether existing controls still make sense. A control designed around a manual data entry step, for instance, may become irrelevant once that step is automated, but a new control addressing the automation's specific failure modes may be needed in its place. Simply carrying old controls forward unchanged into a newly automated process often leaves exactly the gap that automation was supposed to close, just in a different location within the workflow.
Accounting Software Integration Best Practices
A handful of practices consistently separate integrations that work well from ones that create quiet, compounding problems:
- Map every field explicitly rather than relying on default assumptions, and document the mapping somewhere accessible.
- Run a parallel testing period where the integration operates alongside existing manual processes before fully switching over.
- Build in validation rules that flag rather than silently accept records that fail expected checks.
- Assign clear ownership for monitoring the integration after launch, since connections can break quietly when source systems change.
- Schedule a follow-up accounting system review after any significant accounting software integration project, rather than assuming the initial testing covered everything permanently.
These steps do not eliminate the value of speed and automation; they simply ensure that speed does not come at the cost of accuracy or oversight.
Common Pitfalls to Avoid
A few patterns show up repeatedly in businesses that run into trouble after adopting new integration technology. Rushing the rollout without a parallel testing period is probably the most common, since it removes the opportunity to catch mapping errors before they compound across hundreds or thousands of transactions. Assuming that because an integration was built by a knowledgeable staff member, no further review is needed, is another, since even a well-built integration reflects a moment-in-time understanding of the business that may not hold as operations evolve.
Failing to document the integration's logic is a quieter but equally damaging pattern. When the person who built the connection leaves or moves to a different role, an undocumented integration becomes a black box that nobody fully understands, which makes both troubleshooting and any future accounting system review considerably harder. A simple written record of what the integration does, which fields it touches, and what exceptions it is designed to handle pays for itself many times over the first time something needs to be debugged.
When to Combine Both Approaches
The businesses that get the most value from modern ERP integration tend to be the ones that also invest in periodic accounting system reviews, treating the two as complementary rather than sequential or optional. A new integration project is a natural trigger for a review: it is precisely the moment when data flows, controls, and reporting logic are all changing at once, and a professional set of eyes confirming everything still adds up correctly is worth far more than the modest cost of the review itself.
Livida's accounting system review service is built for exactly this kind of moment, examining chart of accounts structure, control effectiveness, and reporting accuracy regardless of which software or integration tools sit underneath. Pairing that review with the operational efficiency of a well-built low-code ERP integration gives a growing business the best of both: faster, less manual data flow, and continued confidence that what ends up in the financial statements is accurate and properly controlled.
Five Essential Checks for Low-Code ERP Integration
Our team uses this short list when a client connects a new system:
- Document every field mapping and the exceptions it handles.
- Run the integration in parallel with the old process for a full cycle.
- Add validation rules that flag bad records instead of accepting them silently.
- Name an owner who monitors the connection after launch.
- Book an accounting system review after the project goes live.
Cost Considerations Worth Weighing
Budgeting for a low-code ERP integration project often focuses heavily on the platform's subscription cost and any implementation time, while underestimating the ongoing cost of maintaining and periodically validating the connection. A cheap, fast integration that quietly produces reporting errors for a year before anyone notices is rarely actually cheaper than a slightly slower rollout paired with proper testing and a follow-up accounting system review. Framing the review as part of the total cost of the integration project, rather than a separate, optional expense, tends to lead to more realistic budgeting and better outcomes.
It is also worth remembering that the cost of a review scales with complexity, not with the sophistication of the integration technology itself. A simple, well-scoped integration touching a handful of predictable transaction types generally requires a lighter review than one spanning multiple entities, currencies, or revenue recognition scenarios. Scoping the review to match the actual complexity of what changed keeps the exercise proportionate and cost-effective rather than treating every system change as requiring the same level of scrutiny.
If you are weighing similar tradeoffs elsewhere in your finance stack, related comparisons on machine learning fraud detection versus human-led audit preparation and choosing between software and managed services work through the same underlying question. Businesses that want a professional set of eyes on their broader financial oversight, not just a single integration project, can also look at Livida's Virtual CFO Advisory service.
Final Thoughts
Low-code ERP integration is a genuinely useful tool for reducing manual work and connecting the growing list of systems a business relies on day to day. It is not, however, a substitute for the structural, judgment-based work of a professional accounting system review, and businesses that treat the two as interchangeable risk discovering the difference at an inconvenient moment, such as during an audit or a lender's due diligence process. Used together, thoughtfully, they support a financial operation that is both efficient and genuinely reliable. If a recent or upcoming system change has you wondering whether your accounting setup still holds up, Livida's team is happy to talk through what a review would look like for your business.
In our experience, the most common finding after a quick integration is an exception the mapping never covered, such as partial refunds or foreign currency items. We recommend testing those cases before go-live. Our team also checks that tax and GST reporting still ties back to source documents, because compliance questions usually surface there first. Bookkeeping and accounting records are only as reliable as the data feeding them.
Conclusion
Low-code ERP integration saves time. A professional review protects accuracy. Use both, and give each a clear owner.
This article is general information, not professional advice, and software, standards and rules change. Confirm current requirements for your own business.
References
- IFRS Foundation for international financial reporting standards
- ICAI, the Institute of Chartered Accountants of India, for accounting and audit guidance
- NIST Cybersecurity Framework for managing the security risks of connected systems
Talk to Livida
To arrange a review of your accounting setup, visit our India contact page, email info@livida.in, or call +91 94860 33194.