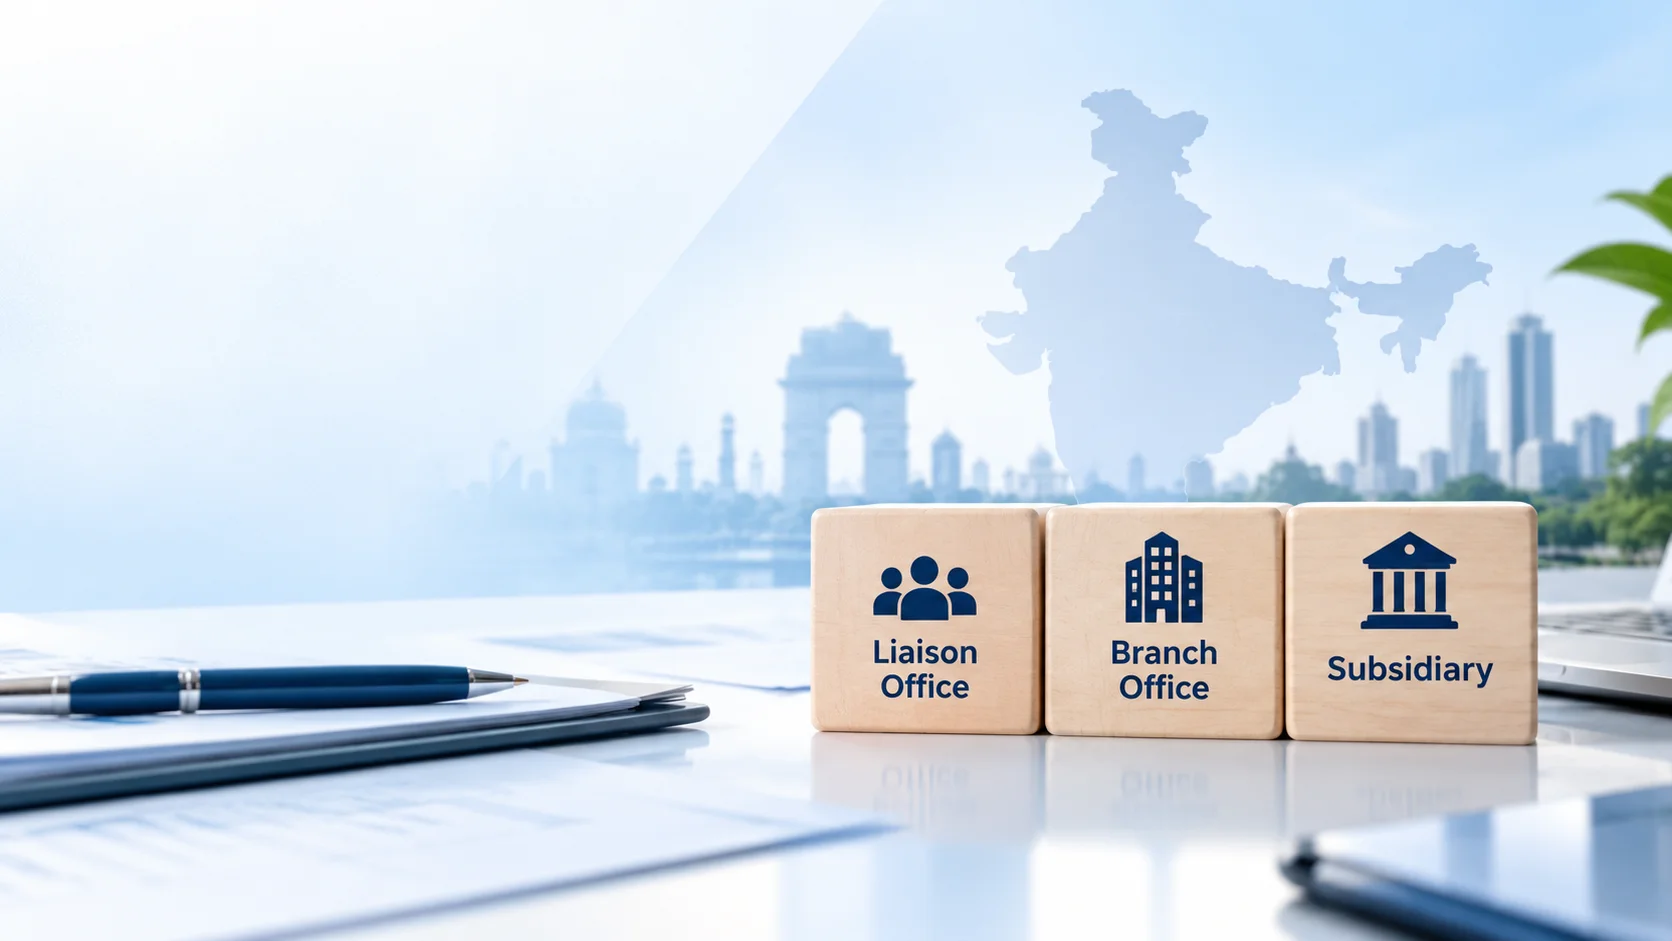
Choosing between a branch office vs liaison office vs subsidiary India is the first structural decision most foreign companies make when they look at the Indian market, and it shapes everything that follows: what you are allowed to do, how you are taxed, who approves you, and how easily you can move profits out. The wrong choice rarely fails dramatically. It usually shows up a year later as an activity you cannot carry out, a tax cost you did not model, or a compliance calendar nobody planned for.
This guide compares the branch office vs liaison office vs subsidiary India options in plain terms, covering approval routes under FEMA and RBI rules, permitted activities, taxation in general terms, and repatriation. It is general information, not professional advice, and rules change, so confirm every point on the RBI, MCA, and Income Tax Department portals before you act.

The Four Ways a Foreign Company Can Enter India
A foreign company without an Indian presence has four common ways to operate on the ground:
- Liaison office (LO): a representative presence that cannot earn income
- Branch office (BO): an extension of the foreign parent that can carry out permitted commercial activities
- Project office (PO): a temporary presence tied to a specific contract
- Wholly owned subsidiary (WOS): a separate Indian company, usually a private limited company, owned by the foreign parent
The first three are extensions of the foreign company, regulated mainly under the Foreign Exchange Management Act (FEMA) and RBI directions. The fourth is a new Indian legal entity, regulated under the Companies Act, 2013 and the foreign direct investment (FDI) policy. That difference between "extension of the parent" and "separate Indian company" drives most of the practical differences below.
Branch Office vs Liaison Office vs Subsidiary India: Quick Comparison
Start with the activity and approval picture. The table reflects RBI's Master Direction on branch, liaison and project offices and the FDI policy as we last reviewed them.
| Feature | Liaison office | Branch office | Subsidiary |
|---|---|---|---|
| Legal status | Part of parent | Part of parent | Separate Indian company |
| Can earn income | No | Yes, permitted activities | Yes, subject to FDI policy |
| Typical approval | Authorised dealer bank, RBI UIN | Authorised dealer bank, RBI UIN | Automatic route in most sectors |
| Manufacturing | No | Not directly, SEZ exceptions | Yes, where sector allows |
| Retail trading | No | No | Sector rules apply |
Now the cost and compliance picture, in general terms only.
| Feature | Liaison office | Branch office | Subsidiary |
|---|---|---|---|
| Tax position | No business income, PAN needed | Taxed as foreign company | Taxed as domestic company |
| Annual RBI reporting | Activity certificate | Activity certificate | Foreign investment reporting |
| Companies Act load | Light | Foreign company filings | Full company compliance |
| Profit repatriation | Not applicable | Subject to tax and certificates | Dividends after tax |
What Each Structure Is Allowed to Do
In the branch office vs liaison office vs subsidiary India decision, the activity limits are where most foreign companies find their answer quickly, so we start there.
Liaison Office
RBI's Master Direction describes a liaison office as a communication channel only. Permitted activities include representing the parent or group companies in India, promoting exports and imports, promoting technical or financial collaborations, and acting as a communication channel between the parent and Indian companies. It cannot undertake business activity or earn income, and its expenses must be met through inward remittances.
That makes an LO a sensible choice for market research, supplier visits, relationship building, and quality oversight before you commit capital. It is not suited to invoicing, signing sales contracts, or running a team that generates revenue.
Branch Office
A branch office can carry out a wider set of activities. The Master Direction lists export and import of goods, professional or consultancy services, research work, promoting technical or financial collaborations, representing the parent as a buying or selling agent, IT services and software development, technical support for products supplied by the parent, and foreign airline or shipping operations. It cannot undertake retail trading of any nature, or manufacturing or processing directly or indirectly. RBI has given general permission for foreign companies to set up branches or units in Special Economic Zones for manufacturing and service activities.
A branch suits a foreign company that wants to provide services or support in India as the same legal entity, without creating a new company. Because the branch is not separate from the parent, the parent's liability extends to the branch's activities.
Project Office
A project office is for a specific contract. The Master Direction says general permission is available where the foreign company has secured a contract from an Indian company to execute a project in India, and the project is funded in specified ways, such as inward remittance, a bilateral or multilateral agency, or a term loan from a public financial institution or bank in India. The office winds up when the project finishes. For one-off contracts, it is the simplest tool. For a continuing business, it is not.
Wholly Owned Subsidiary
A subsidiary is a company incorporated in India that happens to be owned by the foreign parent. It can generally carry out any lawful business that falls within its objects, in sectors where foreign investment is permitted. It can hire staff, sign contracts, own property in its own name, apply for licences, and apply for local incentives, and its liability is limited to its own assets. If you are planning to build a team, this is usually where the conversation ends up.
FEMA and RBI Approval: Automatic Route vs Approval Route
In the branch office vs liaison office vs subsidiary India comparison, "approval route" means different things for offices and for subsidiaries, which is a common source of confusion.
For Branch and Liaison Offices
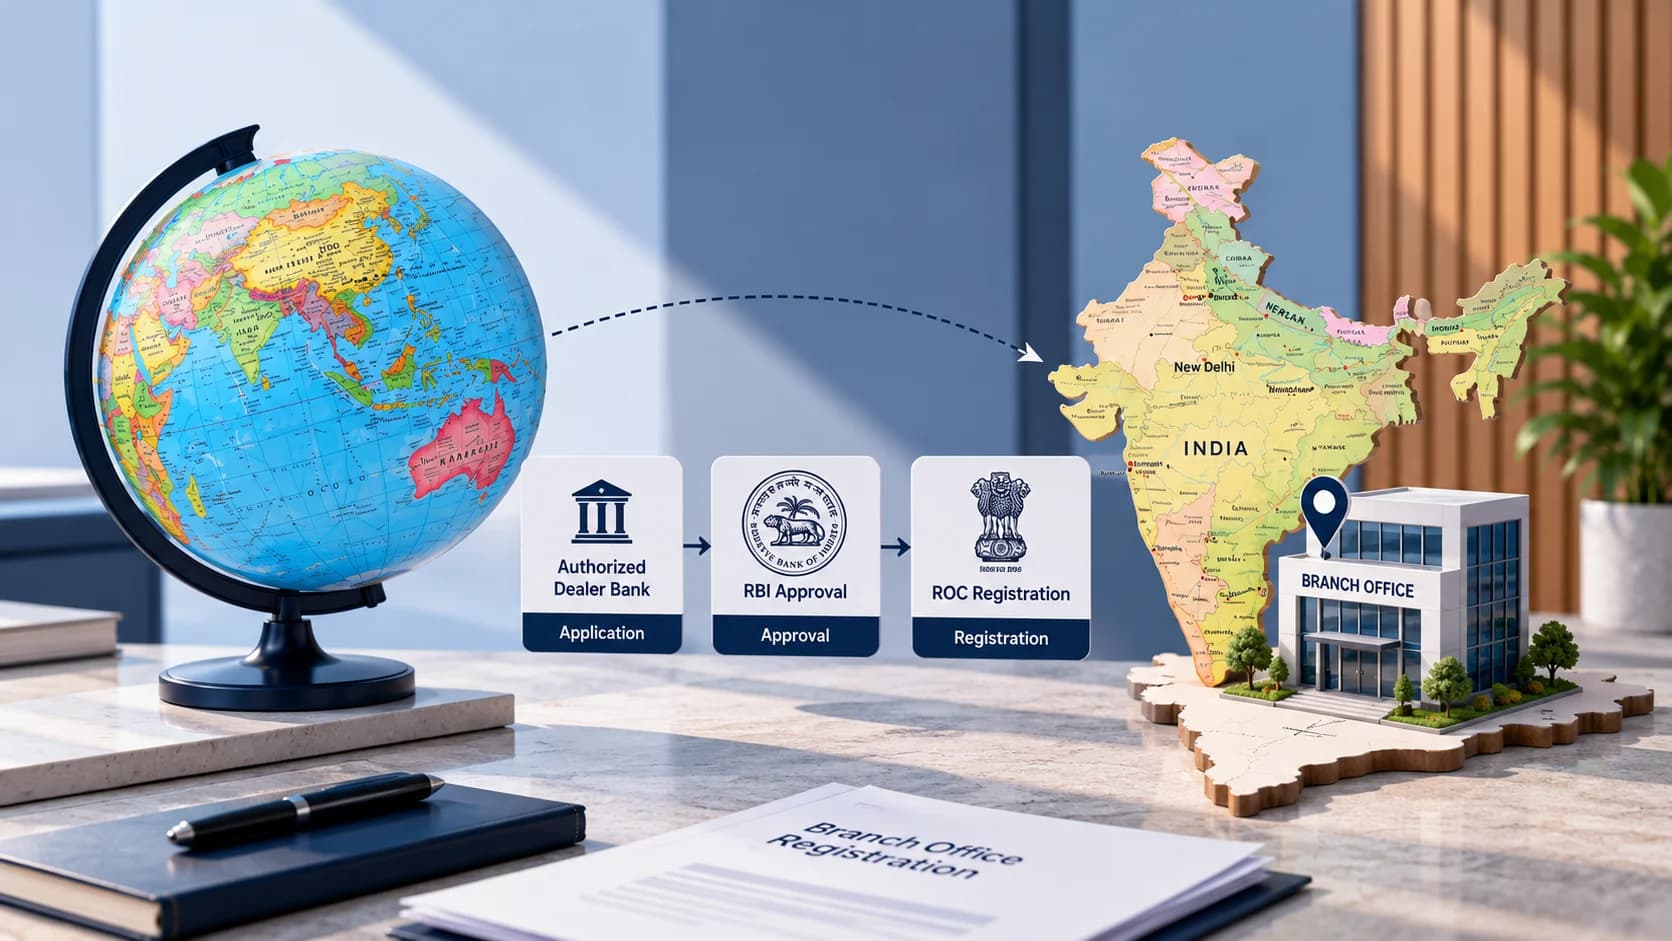
Under RBI's Master Direction, branch and liaison offices are generally approved by an authorised dealer (AD) Category-I bank after due diligence, and the bank forwards details to RBI to allot a Unique Identification Number.
Prior RBI approval applies to specific cases, including applicants from Pakistan, applicants who are citizens or entities of Bangladesh, Sri Lanka, Afghanistan, Iran, China, Hong Kong, or Macau, entities in sectors such as defence, telecom, private security, and information and broadcasting, and NGOs or non-profits. Where the principal business is in a sector that does not allow 100% FDI under the automatic route, the Master Direction routes the application through the government with Ministry of Finance consultation.
Under the 2016 framework, eligibility criteria also apply:
- Branch office: a profit-making track record for the immediately preceding five financial years in the home country, and net worth of at least USD 100,000
- Liaison office: a three-year profit-making track record and net worth of at least USD 50,000
- A subsidiary that is not financially sound can offer a letter of comfort from a parent that meets the criteria
A Rule Change to Watch
RBI published the draft Foreign Exchange Management (Establishment in India of a Branch or Office) Regulations, 2025 in October 2025. The draft proposes to remove the net worth and profit track record requirements, drop the validity cap on liaison offices, and let one project office handle multiple projects. As of the last reports we reviewed in May 2026, the draft had not been notified and the 2016 framework remained in force. If notified, it would change the branch office vs liaison office vs subsidiary India calculation for smaller or newer foreign companies, so check the RBI website for the current position before you plan around either version.
For a Wholly Owned Subsidiary
For a subsidiary, the question is whether your sector sits under the automatic route or the government route. The FDI policy says FDI up to 100% is permitted under the automatic route in most sectors, which means no prior approval from RBI or the Central Government, subject to applicable laws. Some sectors have caps or conditions. Under Press Note 3 of 2020, an entity of a country that shares a land border with India, or whose beneficial owner is situated in or is a citizen of such a country, can invest only through the government route.
In the foreign-company setups we support, the most common surprise is not the sector but the ownership chain. Founders describe the immediate parent correctly, but a beneficial owner further up the chain can change the route, so map the full ownership structure before you decide.
Taxation Differences in General Terms
Tax is where the branch office vs liaison office vs subsidiary India choice has a measurable effect on cash. These are general descriptions only, and the right answer depends on your treaty position, transfer pricing, and the facts of your business.
| Point | Branch office | Subsidiary |
|---|---|---|
| Treated as | Foreign company | Domestic company |
| Base rate | 35% | 22%, 25% or 30% by regime |
| Surcharge and cess | 2% or 5% by income, 4% cess | 10% under 115BAA, otherwise by income, 4% cess |
| MAT | May apply at 15% of book profit | Not applicable under 115BAA |
The Income Tax Department's portal shows the 35% rate for foreign companies for assessment year 2026-27, with surcharge of 2% for taxable income above Rs 1 crore up to Rs 10 crore and 5% above that, plus 4% health and education cess. For domestic companies, it shows 22% for companies opting for section 115BAA, 25% or 30% under other conditions, and a 10% surcharge for 115BAA companies, with those companies exempt from MAT. Parts of Indian tax law are being restructured, so confirm which provisions and rates apply to your year.
Why the Headline Rate Is Only Part of the Story
A lower headline rate for a subsidiary does not automatically make it cheaper overall. Dividend payments to the foreign parent attract their own tax treatment, and a branch's profits can be remitted without a dividend step. Transfer pricing between the parent and an Indian subsidiary is a bigger practical issue than most founders expect, and a liaison office can still create tax questions if its activities drift beyond what is permitted. Model the whole chain, not just the first rate in the table, when you weigh branch office vs liaison office vs subsidiary India.
Liaison Offices and Tax
A liaison office earns no income, so it does not pay tax on business profits, but it still needs a PAN, and RBI expects the office to report on its activities each year. If the activities start to look commercial, the office is operating outside its approval, which is a larger risk than any tax rate.
Compliance Load: What You Sign Up For
Compliance is the cost you pay every year, so for each branch office vs liaison office vs subsidiary India option, compare the calendars, not just the setup steps.
Liaison Office Compliance
The main recurring obligation is the Annual Activity Certificate, signed by a chartered accountant, confirming that the office carried out only permitted activities and complied with the approval terms. The certificate must include the PAN and Unique Identification Number. RBI's FAQs note that authorised dealer banks must report adverse auditor findings or failures to submit these certificates. The LO also needs to keep its approval valid, which is generally granted for three years, with possible extensions.
Branch Office Compliance
A branch is a foreign company with a place of business in India, so it has Companies Act obligations too. A foreign company must deliver documents to the Registrar of Companies within 30 days of establishing its place of business, using Form FC-1, and the application is supported by the RBI approval or a declaration that none is needed. It then files annual accounts and an annual return through the foreign company forms, and files Indian income tax returns, along with RBI reporting through its authorised dealer bank.
Subsidiary Compliance
A subsidiary has the fullest calendar, because it is a company in its own right. A private company needs at least two directors, and at least one director must have stayed in India for at least 182 days in the financial year. The company must keep statutory records, hold board and shareholder meetings, get its accounts audited, and file annual forms with the Registrar. Foreign investment into the company is also reported to RBI as prescribed.
Our team supports this through annual compliance for private limited companies, ROC annual filing, and DIR-3 KYC filing for directors. For a branch, our branch office registration support covers RBI coordination, ROC registration, and the ongoing filings that follow.
Repatriating Profits From Each Structure
For most foreign companies, the end goal of the branch office vs liaison office vs subsidiary India decision is moving money back home, so repatriation deserves its own look.
- Branch office: profits are freely remittable subject to payment of applicable taxes, according to RBI's Master Direction. Expect to provide audited accounts and a chartered accountant certificate.
- Subsidiary: profits are normally distributed as dividends, subject to company law and to tax deducted at source on payments to a non-resident, which a tax treaty may reduce.
- Liaison office: no income, so no profit to remit. Funds flow in to cover expenses, not out.
- Project office: the Master Direction permits intermittent remittances if sufficient provision is made for liabilities and completion of the project is not affected, and winding up follows the Direction's conditions.
Outward payments from India also involve paperwork. If you pay your parent for services, royalties, or dividends, a certificate from a chartered accountant and a declaration to the tax department are usually part of the process, which our Form 15CA and 15CB filing service handles.
When Each Structure Fits
There is no universally best answer to branch office vs liaison office vs subsidiary India. These rules of thumb help narrow the field.
- Testing the market, no revenue yet: a liaison office, or a small subsidiary if you prefer to start with a full entity
- Delivering services as the parent company: a branch office, if your activities fit the permitted list and the parent meets the criteria
- A single defined contract: a project office
- Hiring, selling, and growing in India: a wholly owned subsidiary
- Sensitive sector or land border ownership: start with the FDI policy, because the route may decide the structure
Questions That Settle Most Cases
Before settling branch office vs liaison office vs subsidiary India, work through these questions:
- Will the Indian operation invoice customers or only represent the parent
- Does the parent meet the profit and net worth criteria, or has the rule changed
- Will you hire a team and expect the Indian operation to hold contracts and assets
- How important is limited liability for the parent
- How does the group plan to take profits out
If you plan to build a real business, the subsidiary is typically where companies end up. If you are choosing among Indian entity types for that subsidiary, our guides on how to register a private limited company in India and private limited vs LLP vs OPC explain the options.
Common Mistakes When Choosing a Structure
These are patterns we see when foreign companies settle the branch office vs liaison office vs subsidiary India question, offered as observations rather than statistics.
- Opening a liaison office and then letting staff negotiate prices or take orders
- Assuming a branch can manufacture or trade at retail because the parent does
- Overlooking beneficial ownership when checking the FDI route
- Forgetting the annual activity certificate or RBI reporting until a bank asks
- Treating the structure as permanent when the business plan changes within two years
- Ignoring tax on the way out, such as dividends or service payments to the parent
Key Takeaways
- The branch office vs liaison office vs subsidiary India choice turns on income, tax, and compliance, not setup speed
- A liaison office cannot earn income, while a branch can carry out listed activities but not manufacturing or retail trading
- A subsidiary is a separate Indian company, usually under the automatic route, with full Companies Act obligations
- Branch profits face a 35% base rate, while domestic company rates start at 22% under section 115BAA
- RBI's 2025 draft regulations could remove net worth and track record rules, so check whether they are in force
- Verify every figure on the RBI, MCA, and Income Tax Department sites before you commit
Talk to Livida
Choosing between a branch office vs liaison office vs subsidiary India is easier with someone who has seen the filings that follow. Livida's accounting and bookkeeping team supports foreign companies with branch office registration, subsidiary compliance, tax returns, and outward remittance paperwork in India. Visit our contact page, email info@livida.in, or call +91 94860 33194. This article is general information, not professional advice, and nothing here guarantees any approval or timeline.
Related Reading
- How to Register a Private Limited Company in India, for the subsidiary incorporation process
- Private Limited vs LLP vs OPC in India, for choosing the Indian entity type
- Singapore Private Limited Company for Foreigners, for the Singapore side of an Asia entry plan
- Digital Signature and e-KYC vs Company Incorporation, for the digital steps behind incorporation
References
- RBI Master Direction: Establishment of Branch, Liaison and Project Offices in India
- RBI Master Direction, updated May 2021
- RBI FAQs on Liaison, Branch and Project Offices of foreign entities
- Income Tax Department: Foreign company, tax rates for AY 2026-27
- Income Tax Department: Domestic company, tax rates for AY 2026-27
- DPIIT: Consolidated FDI Policy Circular 2020
- MCA: Form FC-1, information by foreign company