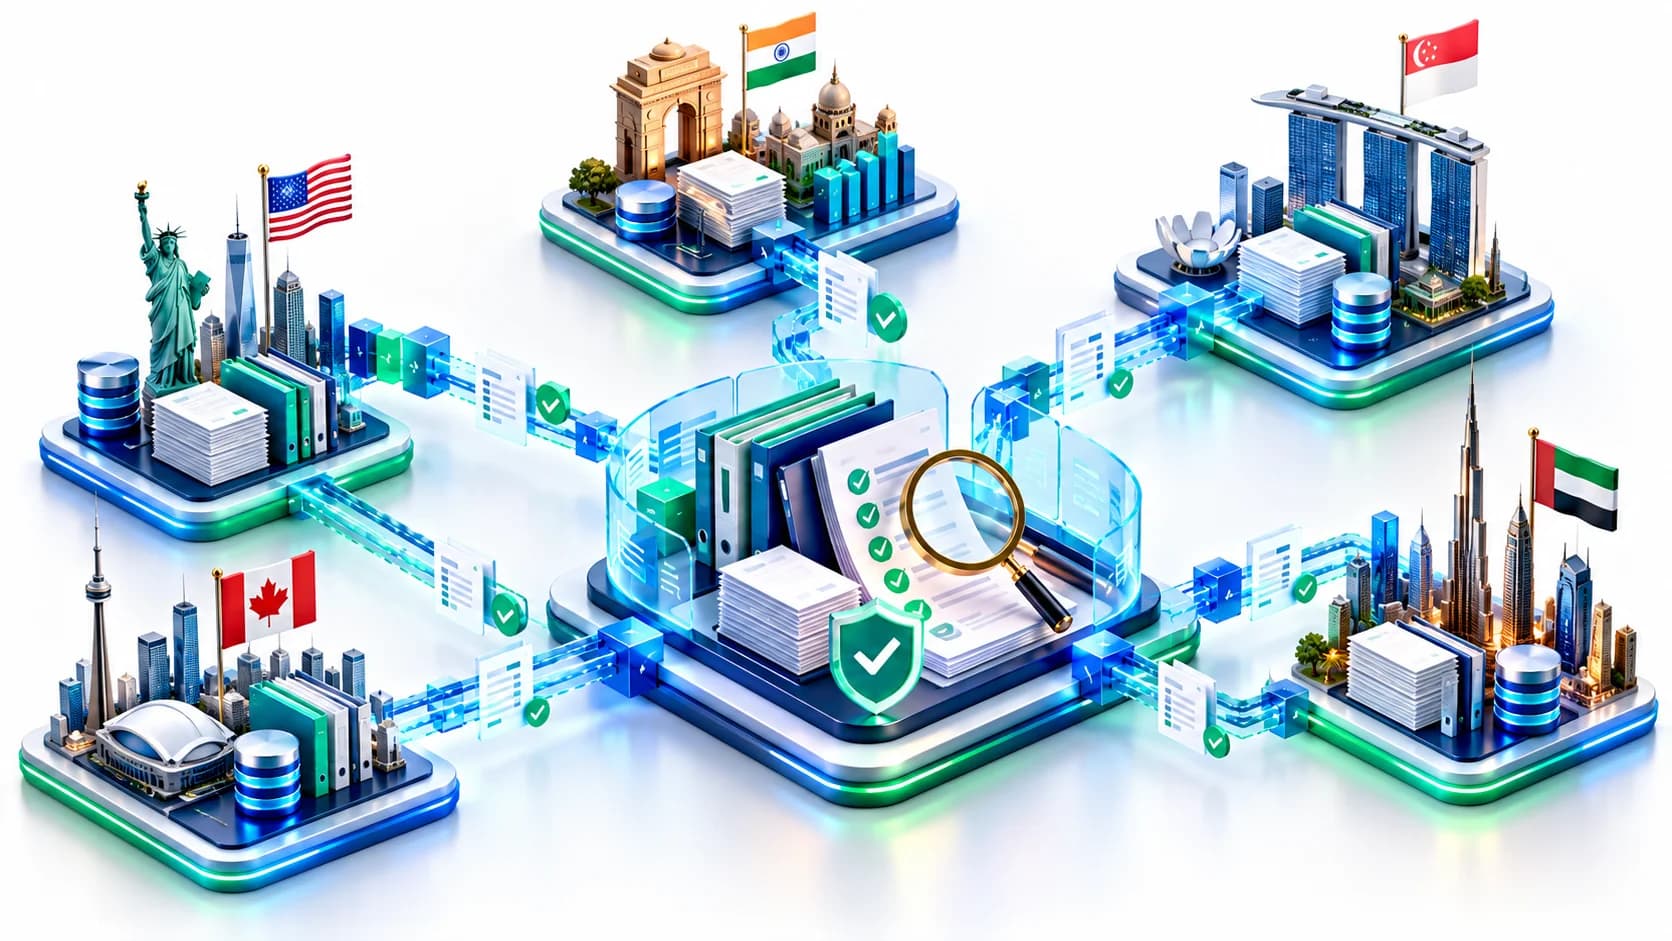
A statutory audit tends to go smoothly or badly depending almost entirely on how prepared the underlying books and documentation are before the auditor ever starts fieldwork. A statutory audit readiness review looks at your records in advance, the same way an external auditor would, so that reconciliation gaps, missing documentation, or inconsistent entries get caught and resolved ahead of time rather than surfacing as findings during the actual audit. Livida offers this review across every region we serve, India, Singapore, UAE, the USA, and Canada.
Why Readiness Reviews Matter
An auditor's job is to test whether financial statements are accurate and supported by proper documentation, and every gap they find, an unreconciled account, a transaction without adequate support, an inconsistency between the statements and the underlying ledger, turns into a query that slows the audit down and can affect the auditor's findings. A business that walks into its audit with clean, well-documented books moves through the process faster and with fewer surprises than one that hasn't reviewed its records beforehand.
What a Statutory Audit Readiness Review Actually Covers
The review examines the same areas a statutory auditor typically focuses on: bank and account reconciliations, supporting documentation for significant or unusual transactions, consistency between the financial statements and the underlying bookkeeping records, and any entries that would reasonably draw a follow-up question. Where gaps are found, whether missing documentation, an unreconciled balance, or an entry that needs correction, they're flagged and addressed before the actual audit fieldwork begins.
A typical review checks:
- Bank, loan, and intercompany account reconciliations against supporting statements
- Documentation for significant, unusual, or related-party transactions
- Consistency between the draft financial statements and the underlying ledgers
- Fixed asset registers and depreciation schedules against physical or contractual records
- Prior-year audit findings, to confirm they were actually resolved rather than just noted
In India, this review is scoped against the documentation standards the Institute of Chartered Accountants of India expects statutory auditors to test for, so the gaps we flag are the same ones a practicing auditor would raise.
How Requirements Differ by Region
Statutory audit obligations vary considerably across the regions Livida serves, Companies Act audit requirements and thresholds in India, ACRA audit exemption criteria for small companies in Singapore, corporate tax and audit expectations in the UAE, and the audit standards that apply to US and Canadian businesses depending on their structure and stakeholders. Livida scopes each readiness review against the specific framework that applies rather than using one generic checklist across every region.
Livida's Process
We review your books and supporting documentation against what an external auditor would typically test, flag gaps or inconsistencies as they're found, and work with your team to resolve them ahead of the audit start date. For clients already using Livida for bookkeeping or year-end accounting in any of our five regions, this review draws directly on records we're already maintaining, making it a natural extension of that relationship. Outside India, this review is delivered remotely by Livida's India-based team, coordinated with your local statutory auditor.
For India-based companies, this readiness review is frequently timed just ahead of ROC annual filing, since accurate, audit-tested financial statements are what that filing ultimately depends on. For Singapore-based clients, it's coordinated with ACRA annual return filing, since the annual return can only be filed once financial statements have been properly presented and, where required, audited. Businesses comparing audit-compilation software against a professionally managed process may also find our post on audit compilation software versus professional audit compilation useful background.
Why This Isn't the Audit Itself
It's worth being clear that a readiness review is preparatory, it is not the independent statutory audit and does not produce an audit opinion, which must come from an appropriately licensed, independent auditor under the framework that applies in your region. What it does is reduce the number of findings and adjustments that come up once that audit begins, saving time and reducing the back-and-forth for everyone involved. If your statutory audit is coming up and you want your records reviewed beforehand, Livida's team can support this across any region we serve.
Statutory Audit Readiness Review at a Glance
| Item | What to expect |
|---|---|
| Who it suits | Businesses facing a statutory or lender-required audit |
| What we review | Reconciliations, supporting documents, ledgers against draft statements |
| Typical documents | Bank statements, asset registers, loan statements, prior-year findings |
| What happens next | We flag gaps, help you resolve them, then coordinate with your auditor |
Key Takeaways
- A statutory audit readiness review checks your records the way an external auditor would, before fieldwork starts.
- Clean reconciliations and supported transactions mean fewer queries and adjustments during the audit.
- The review is preparatory work and does not produce an audit opinion.
- Livida scopes each review against the audit framework that applies in your region.
- Prior-year findings are checked to confirm they were resolved, not just noted.
Conclusion
A statutory audit readiness review is a low-drama way to find problems while there is still time to fix them. Reviewing your records early keeps the audit itself shorter and calmer for your team and your auditor.
References
This page is general information, not professional advice, and audit rules and thresholds change, so confirm the current requirement with the regulator or your auditor. We opened or confirmed the following official pages while preparing it:
- ACRA: audit exemptions and the small company concept, for Singapore audit exemption criteria.
- Ministry of Corporate Affairs: the Companies Act, for the Indian framework that governs company accounts and audit.
- UAE Federal Tax Authority, for UAE tax guidance and services.
- Canada Revenue Agency, for Canadian tax programs and guidance.
Talk to Livida
In the engagements we handle, the most common delay before an audit is a balance that has not been reconciled to its supporting statement, so we start there. For a statutory audit readiness review, or to talk through tax audit support or virtual CFO advisory, visit our contact page, email info@livida.in or call +91 94860 33194. In our experience, an early conversation saves the most time.