Canada GST/HST registration is the step that lets a business charge sales tax, claim back the tax it pays on purchases and stay on the right side of the Canada Revenue Agency (CRA). This guide is for owners of Canadian small businesses and newly incorporated companies who want to know whether they must register, when, and how.
By the end you will know the small supplier threshold, how voluntary registration works, the six steps to register, how often you file, and the mistakes that cost new registrants money. This is general information, not professional advice, and the rules change, so confirm every figure on canada.ca before you act.
Key Takeaways
- Canada GST/HST registration is required once taxable revenue passes $30,000 over four consecutive calendar quarters, or in a single quarter.
- Below that small supplier threshold, voluntary GST/HST registration is allowed if you make taxable supplies in Canada.
- Register through Business Registration Online to receive your Business Number and RT account in one session.
- Your filing frequency is set by revenue, and returns are due one month after a monthly or quarterly period.
- Claim GST/HST input tax credits only with proper invoices, and keep records for six years.
In This Article
- What Canada GST/HST Registration Means
- Who Must Register: The Small Supplier Threshold
- Voluntary GST/HST Registration
- Illustrative Example: Two New Businesses
- Canada GST/HST Registration in 6 Steps
- Your Business Number and RT Account
- Filing Frequency and Deadlines
- Collecting and Remitting GST/HST
- GST/HST Input Tax Credits
- HST vs GST vs PST at a Glance
- Common Mistakes to Avoid
- Summary
- Conclusion
What Canada GST/HST Registration Means
Canada GST/HST registration is the process of enrolling your business with the CRA for the goods and services tax and harmonized sales tax. Once your Canada GST/HST registration is active, you charge the tax on taxable sales, file returns and send the CRA the net amount. You also gain the right to claim back tax paid on business costs.
The CRA runs the GST/HST for most of Canada. Quebec is the main exception for the provincial part, because Revenu Quebec deals with the Quebec sales tax.
Key Terms in Plain Words
A small supplier is a business whose taxable revenue stays at or below the CRA limit. An input tax credit (ITC) recovers GST/HST paid on business purchases. Registration is separate from incorporation, as our guide on federal vs provincial incorporation in Canada explains.
Who Must Register: The Small Supplier Threshold
Canada GST/HST registration is mandatory once a business stops being a small supplier. The CRA says you are a small supplier if your taxable revenue does not exceed $30,000 over four consecutive calendar quarters. Pass that line and you must register for GST/HST and start charging it.
The small supplier threshold counts taxable sales, including zero-rated sales, and the taxable sales of your associates. It leaves out financial services, sales of capital property and goodwill. The CRA's page on when to register for and start charging the GST/HST is the source for the current figure.
The Single Quarter Rule
If you go over $30,000 in a single calendar quarter, the CRA says you stop being a small supplier on the sale that pushed you over. You must charge GST/HST on that sale and every sale after it. This catches businesses that land one large contract in a quiet quarter.
The Four Quarter Rule
If your total passes $30,000 across the previous four quarters but not in any one quarter, the CRA says you stop being a small supplier at the end of the month after that quarter. Your effective date of registration is no later than your first sale after that point. The CRA's examples allow 29 days from the effective date to register.
Who Must Register Whatever Their Revenue
Some businesses cannot rely on the small supplier rule at all. The CRA lists these cases:
- Self-employed taxi operators and commercial ride-sharing drivers, from the day they start supplying passenger transportation.
- Non-residents who sponsor a convention in Canada where more than 25% of attendees are Canadian residents.
- Non-residents who make taxable admission sales for events held in Canada.
Charities and public service bodies use different tests.
Voluntary GST/HST Registration
Voluntary GST/HST registration lets a small supplier register before it has to. The CRA allows it if you make taxable supplies in Canada. The main benefit is the right to claim input tax credits, and the main cost is that you take on every filing duty of a mandatory registrant.
The effective date is usually the day you request the account, or up to 30 days before. The CRA also notes that you may need to stay registered for at least one year before you can cancel. That makes the choice a real commitment, not a trial.
When Voluntary Registration Tends to Help
Early Canada GST/HST registration can suit a business that:
- Spends heavily on start-up costs, equipment or software and wants the tax back.
- Sells mostly to GST/HST-registered businesses, so charging tax does not hurt its prices.
- Sells zero-rated goods or services, such as exports, and pays tax on its own purchases.
Illustrative Example: Two New Businesses
The example below is a made-up scenario to show how the rules work. It is not a real client, and the figures are round numbers chosen for clarity.
Consider two Ontario corporations formed this year. Company A is a web design agency that has billed $6,000, $7,000 and $8,000 in three quarters, then signs a $12,000 project that will be billed in one quarter. Company B is a consultant who has billed $18,000 in total, but who buys a lot of software and equipment for client work.
Company A: Mandatory Registration
Company A is at $21,000 over three quarters, and the new project will carry it past $30,000 over four quarters. It stops being a small supplier at the end of the month after that quarter, so it should register before then and have its account ready before the contract is signed.
Company B: A Voluntary Choice
Company B is below $30,000, so registration is not required. Its clients are other businesses that can recover the tax, and its purchases carry real tax. Voluntary registration could let it claim input tax credits on that spending, but it must accept returns and the possible one-year minimum.
Canada GST/HST Registration in 6 Steps
Canada GST/HST registration follows six steps: test your revenue, decide on voluntary registration, gather your details, register online, set up charging and records, then file on your assigned schedule. Work through them in order.
Step 1: Test Your Revenue Before Canada GST/HST Registration
Add up taxable sales by calendar quarter, including zero-rated sales and your associates' taxable sales. Compare the last four quarters with $30,000 and each single quarter with $30,000. Keep a dated schedule, because the effective date of registration depends on the quarter in which you crossed the line.
Step 2: Decide on Early Registration
If you are below the limit, compare the input tax credits you would recover with the extra admin and the possible one-year minimum.
Step 3: Gather Your Details
The CRA asks for information about the person applying and about the business:
- Your name, SIN, date of birth and home postal code.
- The business name, Business Number if you have one, and business type.
- The names and SINs of all owners.
- Physical and mailing addresses.
- A description of the major business activity.
- Your fiscal year and total annual revenue, where a new business can give a reasonable estimate.
Step 4: Register Through Business Registration Online
Business Registration Online (BRO) is the CRA's online service for new registrations. You need a CRA account to use it. In one session you can register for a Business Number, a GST/HST account and certain other program accounts, such as payroll deductions.
The CRA says the session times out after 10 minutes of inactivity and you cannot save partway through. Have your details ready before you start. Owners with a temporary SIN that starts with 9 must use BRO.
Step 5: Set Up Charging, Invoices and Records
Before your first taxable sale after the effective date, update your invoices, price lists and accounting software, and set up a way to capture supplier invoices. Our GST/HST filing service covers this setup and the returns that follow.
Step 6: File and Remit on Schedule
Canada GST/HST registration does not end when you get your number. Put your first due date in the diary on the day you register. Then file each return and pay any net tax by the deadline. The CRA says all registrants must file electronically, except charities and selected listed financial institutions, for periods ending in 2024 and later.
Your Business Number and RT Account
A Business Number (BN) is the 9-digit number that identifies your business with the CRA. A GST/HST account is a program account attached to it. The CRA says its program identifier for GST/HST is RT, so your account number looks like 123456789 RT 0001.
You can have only one BN per business. Each program account you add, such as GST/HST or payroll, is added to that same number. This is why the Business Number RT account pairing matters: one number holds your whole CRA relationship, and your returns are filed against the RT part.
Save Your Numbers and Reuse Existing Ones
The CRA says you must save or print your BN and GST/HST account number at the end of a BRO session, because it will not be sent to you. If your corporation already has a BN, you add the GST/HST program account to it. Our Business Number registration service covers both cases, and the federal incorporation and provincial incorporation services sit upstream of it.
Filing Frequency and Deadlines
The CRA assigns your reporting period by revenue. Up to $1,500,000 of annual taxable supplies you are assigned annual filing, up to $6,000,000 quarterly, and above that monthly. Monthly and quarterly returns are due one month after the period ends, and annual returns three months after year end.
| Annual taxable supplies | Assigned period | Optional periods |
|---|---|---|
| Up to $1,500,000 | Annual | Monthly or quarterly |
| Over $1,500,000 to $6,000,000 | Quarterly | Monthly |
| Over $6,000,000 | Monthly | None |
Due Dates in Practice
A quarter ending 31 March is due 30 April, for example. Most annual filers, including corporations, file and pay within three months of the fiscal year end. Sole proprietors with a 31 December year end and business income file by 15 June but pay by 30 April. A due date on a weekend or holiday moves to the next business day.
Changing Your Reporting Period
An annual or quarterly filer can elect a more frequent period by signing in to the CRA account. Many small businesses choose quarterly or monthly filing, because it speeds up refunds when credits exceed tax collected.
Late Filing and Payment
The CRA says interest starts from the payment due date, and penalties may apply. It may cancel or waive certain penalties and interest in extraordinary circumstances, but that relief is not automatic.
Collecting and Remitting GST/HST
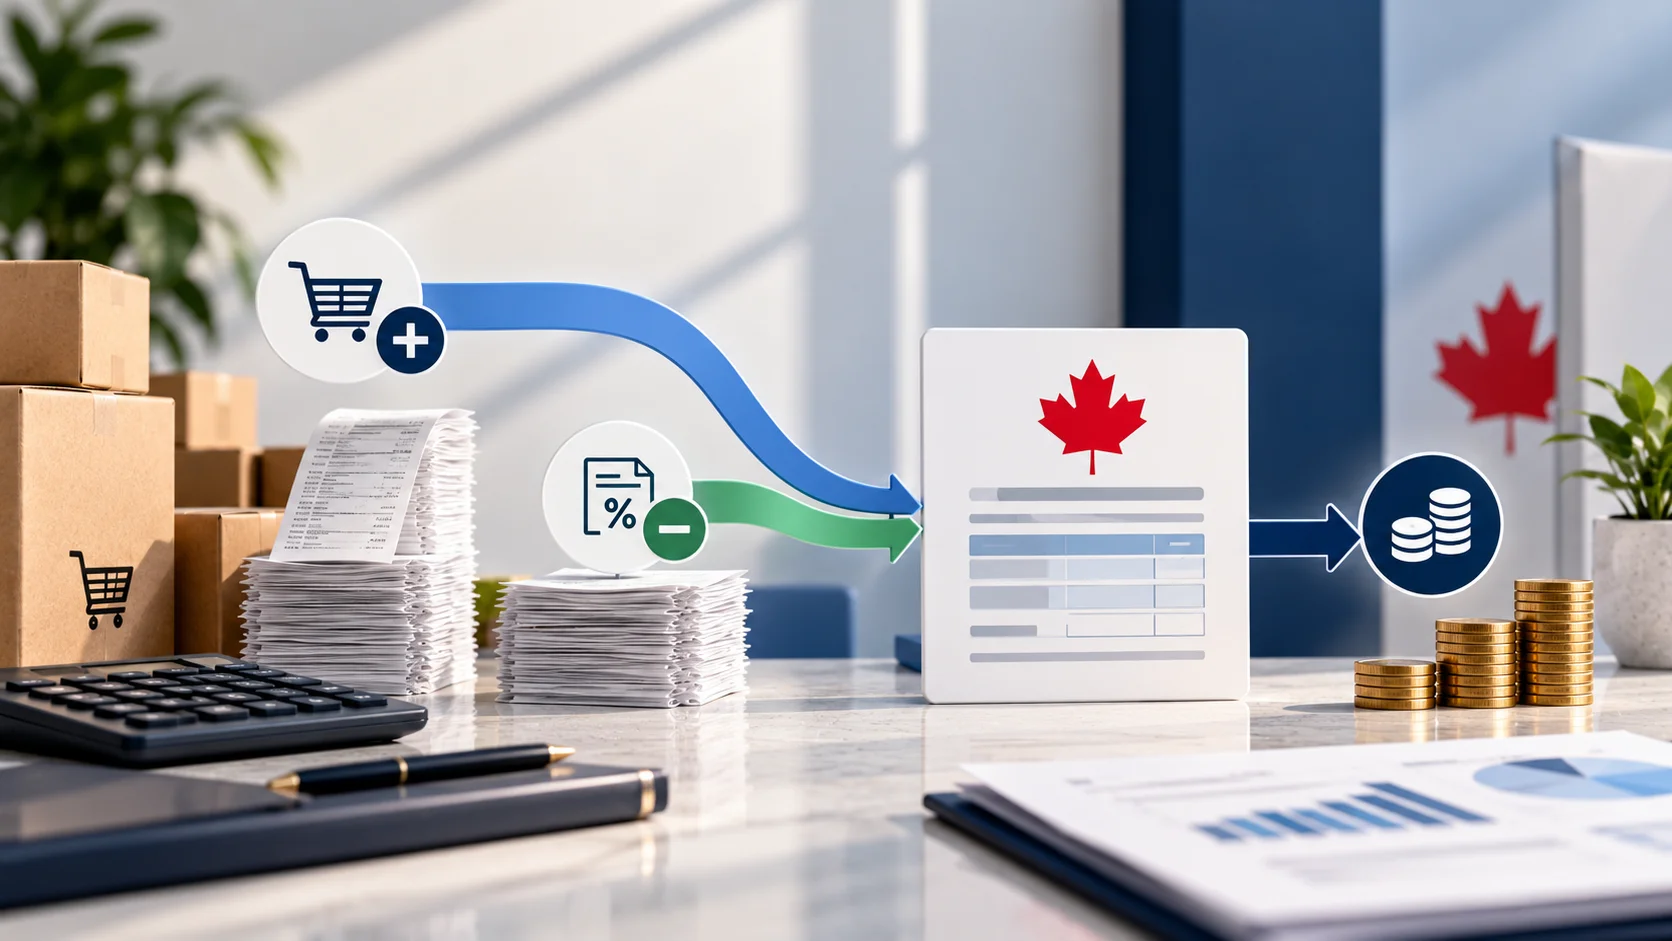
A registrant must charge and collect GST/HST on taxable supplies, other than those taxed at 0%. You then report what you collected, subtract your input tax credits, and send the CRA the difference. If credits exceed tax collected, the return shows a refund.
Zero-rated supplies are taxable at 0%, so you charge nothing but still claim input tax credits. Exempt supplies carry no tax and generally give no credits.
Which Rate Applies
The rate depends on the place of supply, which is the province or territory where the CRA treats the sale as made. The CRA gives this example: a store in Vancouver delivers a mattress to Toronto, so the place of supply is Ontario and the rate is 13% HST. Delivery location often decides the rate.
A Simple Remittance Walkthrough
Use this walkthrough to see how a return works. It uses a made-up quarter with round numbers.
- You sell $20,000 of taxable services in Ontario and charge 13% HST, so you collect $2,600.
- You pay $4,000 for taxable business costs and $520 of that is HST.
- You claim the $520 as an input tax credit.
- Your net tax is $2,600 minus $520, which is $2,080.
- You file and pay $2,080 by the due date.
GST/HST Input Tax Credits
GST/HST input tax credits are how a registrant recovers tax paid on purchases and expenses used in its commercial activities. You claim them on line 106 of your return. To claim, you must be registered, hold proper documents, and claim within the time limit.
The CRA also says the expense must be reasonable in quality, nature and cost for your business. Commonly eligible costs include start-up costs, professional fees, rent, utilities, office expenses, telephone and travel. Commonly ineligible items include recreation club memberships, personal-use items, and inputs used to make exempt supplies.
What Your Invoices Must Show
The CRA sets documentation by invoice size. Every invoice needs the supplier name, date and total. From $100 you also need the tax amount and the supplier's GST/HST number. From $500 you need the buyer's name, a description and the payment terms.
Time Limits and the Quick Method
Most registrants have four years to claim. Businesses on the quick method of accounting cannot claim credits on operating expenses, though they may claim on certain capital purchases.
HST vs GST vs PST at a Glance
GST is the 5% federal tax. HST is a single tax in participating provinces that merges the federal and provincial parts. PST is a separate provincial tax that the CRA does not collect as part of GST/HST. Knowing which one applies to a sale is the heart of correct invoicing.
| Tax | What it is | Where it applies |
|---|---|---|
| GST | 5% federal tax | Rest of Canada outside HST provinces |
| HST | Combined federal and provincial tax, set by province | NB, NL, NS, ON and PEI |
| PST | Separate provincial tax, calculated apart from GST | Provinces that charge it, such as Manitoba |
Examples of Rates and Special Cases
The CRA gives Ontario at 13% HST. Nova Scotia's provincial part fell from 10% to 9% on 1 April 2025, so its HST is 14%. In a CRA example, Manitoba is 5% GST plus 7% PST. Where PST applies, calculate GST on the price without PST. For the Quebec sales tax, the CRA points users to Revenu Quebec. Rates change, so use the CRA's GST/HST calculator.
Common Mistakes to Avoid
Most registration problems come from timing and paperwork, not from the law itself. These are the mistakes we see most often in Canada GST/HST registration:
- Watching only the annual total. The single quarter rule can end small supplier status in the middle of a year.
- Using the wrong rate. Place of supply drives the rate, so the supplier's office is not the test.
- Claiming credits without invoices. Missing supplier numbers on larger invoices put credits at risk.
- Claiming credits without invoices. Missing supplier numbers on larger invoices put credits at risk.
- Missing the first return. A new registrant who files late can face interest and penalties.
In the filings we handle, the most common delay is an unclear revenue picture, because the threshold question depends on dated sales by quarter. We recommend gathering that schedule before you apply.
Record-Keeping Slip-Ups
The CRA says to keep records for six years after the end of the last tax year they relate to, at your place of business or residence in Canada unless the CRA gives written permission otherwise.
Summary
Canada GST/HST registration is required when taxable revenue passes the $30,000 small supplier threshold, and optional below it if you make taxable supplies. You register through Business Registration Online and receive a Business Number and RT account. Your revenue sets your filing frequency. Keep invoices to claim input tax credits and records for six years. Rates depend on the place of supply, so check each sale.
Conclusion
Canada GST/HST registration works best when you decide on it early, with dated sales figures in hand and a clear view of your costs. Complete it before you pass the threshold if you can, and set up invoicing and records before your first taxable sale. If you want help, Livida can assess your position, manage the application and continue into GST/HST registration support and ongoing filing. Once you have an account, your T2 corporate tax filing and annual return filing fit into the same calendar. Book a call before the threshold arrives.
Talk to Livida
If you are unsure whether Canada GST/HST registration applies to your business yet, or you want help with the application and your first returns, we can talk it through. Use our contact page, email info@livida.in, or call +91 94860 33194. Livida supports Canada-based clients remotely from India and does not guarantee approvals or timelines, which rest with the CRA.
References
- Canada Revenue Agency: When to register for and start charging the GST/HST
- Canada Revenue Agency: Register for a GST/HST account
- Canada Revenue Agency: Business number and CRA program accounts
- Canada Revenue Agency: General information for GST/HST registrants (RC4022)
- Canada Revenue Agency: When to file your GST/HST return
- Canada Revenue Agency: Input tax credits
- Canada Revenue Agency: Which rate to charge and collect
- Canada Revenue Agency: Where to keep your records and for how long
Reviewed for accuracy in November 2026.
Related Reading
- Federal vs Provincial Incorporation Canada: 5 Simple Steps, No Stress, on choosing the structure before you register
- Year-End Accounting Technology Trends for Canadian Businesses, on the records behind your year-end filings
- Notice to Reader Compliance Canada: Automation vs. Standards, on compliance standards for Canadian financial statements