Singapore GST registration is a decision, not an automatic step, and a new company can get it wrong in two directions. It can register too early and take on duties it did not need, or register too late and owe GST on sales it never charged. This guide is for founders and finance leads of newly incorporated Singapore companies who want to decide whether and when to register, then complete the process cleanly.
By the end you will know the threshold, how voluntary registration works, the six steps to apply on the myTax Portal, how often you file, and what invoicing and record-keeping the Inland Revenue Authority of Singapore (IRAS) expects. This is general information, not professional advice, and the rules change, so confirm every figure and date on the IRAS website before you act.
Key Takeaways
- Singapore GST registration is compulsory above S$1 million of taxable turnover, tested at calendar year end and by forecast.
- A smaller company can choose voluntary GST registration in Singapore, but IRAS requires a two-year minimum.
- Apply through the IRAS myTax Portal GST service, then check the approval letter for your number and effective date.
- Singapore GST filing is due one month after each accounting period, even when you have nothing to report.
- Keep tax invoices and records for at least five years.
In This Article
- What Singapore GST Registration Means
- Do You Need to Register? The S$1 Million Test
- Voluntary GST Registration in Singapore
- Illustrative Example: Two New Companies
- Singapore GST Registration in 6 Steps
- Invoicing Rules After You Register
- Singapore GST Filing: Frequency and Deadlines
- Records, Changes and Wider Compliance
- Common Mistakes to Avoid
- Summary
- Conclusion
What Singapore GST Registration Means
Singapore GST registration is the process of enrolling your business with IRAS so that you charge Goods and Services Tax on taxable sales and claim back GST on business purchases. Once registered, you become a GST collecting agent and must file regular returns, so Singapore GST registration is also an ongoing commitment. IRAS gives the prevailing rate as 9%.
GST is a tax on the supply of goods and services in Singapore. You collect it from customers, subtract the GST you paid to suppliers (subject to the input tax conditions), and pay the difference to IRAS. If your input tax is higher, you may receive a refund.
What Changes After Singapore GST Registration
Singapore GST registration brings duties that start on the effective date. IRAS lists them as charging GST, filing and paying on time, issuing proper invoices, keeping records for at least five years, and reporting business changes within 30 days.
What You Must Not Do Early
IRAS states that you must not charge or collect GST before your effective date. Your approval letter gives that date, so check it before you change your invoice template.
Do You Need to Register? The S$1 Million Test
The compulsory GST threshold in Singapore is S$1 million of taxable turnover. IRAS tests it two ways: looking back at the calendar year, and looking forward over the next 12 months. If either test is met, Singapore GST registration is mandatory, and the table below sets out how each one works.
| Test | Trigger | When to apply | Effective date |
|---|---|---|---|
| Retrospective | Taxable turnover above S$1 million at the end of a calendar year | 1 to 30 January of the next year | 1 March of that year |
| Prospective | Reasonably expected turnover above S$1 million in the next 12 months | Within 30 days of the forecast | Two months after the forecast date (from 1 July 2025) |
| Voluntary | Below the threshold, with a qualifying reason | When you choose | Within two weeks of the approval letter |
Retrospective Test for Singapore GST Registration
Look at your taxable turnover for the calendar year, 1 January to 31 December. IRAS says that if it exceeded S$1 million, you must apply between 1 and 30 January of the following year, and you are then registered from 1 March. A company that started trading mid-year still uses the calendar year, so diarise this date in your first year.
Prospective Test for Singapore GST Registration
At any point, if you can reasonably expect taxable turnover above S$1 million in the next 12 months, you must apply within 30 days of the date of your forecast. IRAS says the forecast should be supported by documents such as signed contracts. A view based only on a business plan or sales target does not by itself create the obligation.
Exemption From Singapore GST Registration
If your sales are wholly or mainly zero-rated, such as exports, you may apply to the Comptroller of GST for exemption from registration, even when you pass the threshold. Exemption is by application, not automatic.
Voluntary GST Registration in Singapore
Voluntary GST registration in Singapore lets a business below S$1 million choose Singapore GST registration, provided it meets a condition IRAS lists. It can help you claim GST on purchases, but this type of Singapore GST registration carries a two-year minimum commitment and the full set of compliance duties, so IRAS asks you to consider it carefully.
IRAS says you must meet its conditions both before and after you register, and its e-Tax guide on voluntary registration conditions sets them out.
Who Qualifies
According to IRAS, you can apply if you meet at least one of these:
- Your business makes taxable supplies.
- Your business makes only out-of-scope supplies, mainly sales of goods that did not enter Singapore or goods in transit.
- Your business makes exempt supplies of financial services that are also international services.
- Your business buys services from overseas or imports low-value goods, and would not get full input tax credit even if registered.
If you have not started trading, IRAS says you can still apply, but you must show that you are carrying on a business and have firm plans to do so.
Benefits and Costs
IRAS sets out the trade-off for voluntary GST registration in Singapore:
- Benefit: you can claim GST on purchases, subject to the conditions for claiming input tax.
- Benefit: if turnover is near but below S$1 million, you stop tracking the GST threshold in Singapore every month.
- Cost: you become a GST collecting agent, with returns, invoicing rules and record-keeping.
- Cost: if your customers are not GST-registered, you may have to absorb the GST and lose margin.
IRAS adds that mainly zero-rated businesses can see profit improve, because they claim GST on purchases without charging GST on sales.
Extra Requirements for Voluntary Applicants
A voluntary applicant has more to prepare than a compulsory one. IRAS says the company director, sole proprietor, partner, trustee or GST return preparer should complete the Overview of GST e-learning and pass the quiz, unless an exemption applies. Examples include experience managing a GST-registered business or using an Accredited Tax Advisor or Practitioner.
Voluntary applicants should also apply for GIRO. Under the GST InvoiceNow requirement, IRAS says businesses applying for voluntary registration on or after 1 April 2026 must transmit invoice data through InvoiceNow-Ready Solutions. Check your accounting software before you apply.
Illustrative Example: Two New Companies
The example below is a made-up scenario, not a real client, and the figures are round numbers chosen for clarity.
Consider two Singapore private limited companies incorporated this year. Company A is a software reseller that signs a 12-month contract with a local customer, and the signed contract shows expected taxable sales of S$1.3 million over the next year. Company B is a design studio that sells services to overseas customers and expects S$400,000 of sales.
Company A: Compulsory, Prospective Test
Company A can reasonably expect taxable turnover above S$1 million in the next 12 months, with a signed contract as support. It must apply for Singapore GST registration within 30 days of its forecast, and registration takes effect two months after the forecast date.
Company B: A Voluntary Choice
Company B is well below S$1 million, so registration is not compulsory. Its sales are mainly to overseas customers, which may be zero-rated, while it pays GST on local software and equipment. Voluntary registration could let it claim that input GST, but the two-year commitment still needs weighing.
What the Example Shows
The same threshold gives two answers. Company A has a deadline, and Company B has a cost-benefit decision. Both need the same facts: contracts, a sales forecast, customers by GST status, and the GST paid on purchases.
Singapore GST Registration in 6 Steps
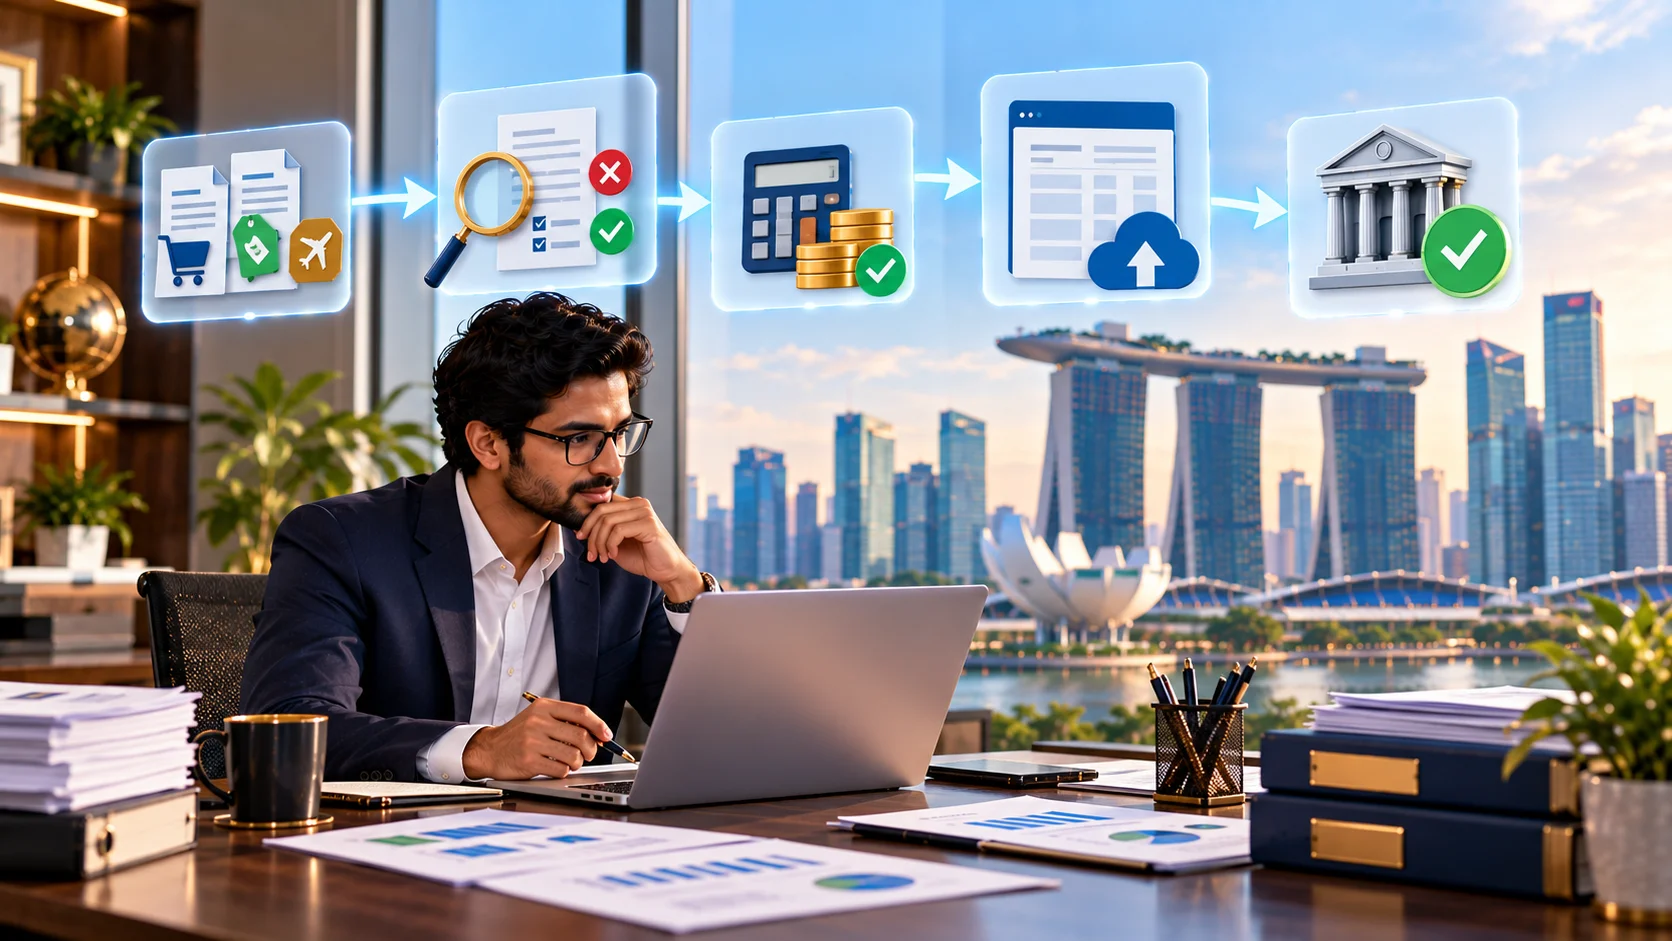
The Singapore GST registration process has six steps, based on IRAS's application guidance: confirm the registration type, calculate your turnover, prepare documents, apply on the myTax Portal, answer IRAS queries, then set up invoicing and a filing calendar. These apply to every Singapore GST registration, whether compulsory or voluntary.
- Confirm the type. Decide whether you are compulsory (retrospective or prospective) or voluntary.
- Calculate turnover and date. Use actual sales or documented forecasts, and note when your obligation arose.
- Prepare documents and tools. Have softcopies ready, plus e-learning, GIRO and InvoiceNow software if voluntary.
- Apply on the myTax Portal. Log in at mytax.iras.gov.sg and submit the online form, because incomplete applications are not processed.
- Answer queries and collect the letter. The approval letter shows your GST number and effective date under Notices/Letters.
- Set up invoicing and a calendar. Update templates from the effective date and diarise the first return.
How Long Singapore GST Registration Takes
IRAS says 60% of applications are processed within 10 working days, and the rest within 30 days. Voluntary registration takes effect within two weeks of the approval letter and is not backdated. A late Singapore GST registration is backdated to the date you should have registered.
Who Should Prepare the Application
In the Singapore filings we support, the most common delay is a turnover forecast with no supporting paper behind it. Our team reviews turnover and prepares the application through our Singapore GST registration service, delivered remotely from India.
Invoicing Rules After You Register
After Singapore GST registration, each sale needs the right document. A tax invoice supports your customer's input tax claim, so IRAS sets out what it must contain. You must issue one to a GST-registered customer within 30 days of the time of supply.
IRAS says the document must be titled "Tax Invoice" and show:
- Your name, address and GST registration number.
- The invoice date and a unique number.
- The customer's name and address.
- A description of the goods or services.
- The GST rate and the amounts excluding GST, the GST itself, and the total.
Simplified Tax Invoices and Receipts
A simplified tax invoice, with fewer details, is allowed when the total including GST does not exceed S$1,000. For customers who are not GST-registered, a receipt can be used, which IRAS says must be serially numbered, with a duplicate kept. Your GST registration number must appear on all three documents.
Credit Notes and Rounding
Use a credit note to correct an invoice, and show the original invoice number and date. IRAS allows 9% to be applied item by item or on the subtotal, but use one method consistently.
InvoiceNow
IRAS says GST-registered businesses must send invoice data through InvoiceNow-Ready Solutions, in phases. It lists 1 April 2026 for new voluntary applicants and 1 April 2028 for new compulsory applicants. Confirm your date on the IRAS page.
Singapore GST Filing: Frequency and Deadlines
Singapore GST filing means submitting a GST return through the IRAS myTax Portal GST service for every accounting period and paying any tax due. The return and payment are due one month after the period ends. The standard period is quarterly, and a nil return is still required.
| Item | What IRAS says |
|---|---|
| Standard period | Quarterly, set by your financial year end |
| Monthly option | Request through myTax Mail, subject to IRAS approval |
| Due date | One month after the period ends, return and payment |
| Notice for a change | At least 30 days before the new period starts |
| Nil return | Required even with no activity |
Quarterly Periods
For a company with a 31 December year end, the quarters are January to March, April to June, July to September and October to December. A return for January to March is due on 30 April, according to IRAS. A year end in another month shifts the quarters, for example February to April.
Monthly Filing and Special Periods
You can ask IRAS to approve monthly filing, and you can apply for special accounting periods if your financial periods do not follow calendar months. The request goes through myTax Mail under GST (Filing and Applications), at least 30 days before the first new period. Our Singapore GST filing service handles the quarterly cycle from preparation to submission.
Late Filing and Late Payment
For a late return, IRAS imposes a S$200 penalty immediately after the due date, and a further S$200 for each completed month it stays outstanding, up to S$10,000 per return. Failure to file is also an offence, with a fine of up to S$5,000. For late payment, a 5% penalty applies to unpaid GST, and a further 2% per month may apply after 60 days, capped at 50% of the outstanding tax.
Records, Changes and Wider Compliance
IRAS says you must keep business and accounting records for at least five years from the end of the accounting period, and that this applies even if you cease business or deregister. That covers the tax invoices you issue and receive, so a shared folder with clear naming saves time after Singapore GST registration.
Keep Your Details Current
IRAS requires you to notify it within 30 days of changes such as a new mailing address, a change in ownership or partners, or a change of business constitution. A change of financial year end can also move your GST accounting periods.
Where GST Fits With Other Obligations
GST is one filing among several. A new company also deals with incorporation formalities, annual returns and corporate income tax. If you are still setting up, see our Singapore company incorporation service and our guide to a Singapore private limited company for foreigners.
Income tax is a separate return, covered by our Singapore corporate tax filing service. The financial statements that support both are explained in XBRL automation vs professional XBRL filing.
Common Mistakes to Avoid
Most problems with Singapore GST registration come from timing and assumptions rather than complexity. We recommend a calendar and a short checklist to avoid each of these.
- Missing the January window. The retrospective test has a fixed application window of 1 to 30 January.
- Ignoring the forward test. A signed contract can make you liable within 30 days of your forecast, long before the calendar year ends.
- Charging GST before the effective date. IRAS says you must not collect GST until registered.
- Registering voluntarily without reading the two-year rule. You cannot easily undo the decision.
- Forgetting nil returns. A quiet quarter still needs a filed return.
- Treating invoices as a formality. Missing details can block your customer's claim.
- Assuming late registration will be forgiven. IRAS says backdated GST remains payable even when it waives the fine.
If you are unsure which side of the line you are on, a review before Singapore GST registration is cheaper than a backdated one.
Summary
Singapore GST registration is mandatory when taxable turnover passes S$1 million on either IRAS test, and optional below that through voluntary GST registration in Singapore with a two-year minimum. You apply on the IRAS myTax Portal, then issue compliant tax invoices and keep records for five years. Singapore GST filing follows a quarterly cycle unless IRAS approves monthly filing, with returns due one month after each period.
Conclusion
The right time for Singapore GST registration is the point where the numbers, not the calendar, say so. Test turnover on both IRAS bases, weigh the GST threshold in Singapore against your own forecast, and set up invoicing and Singapore GST filing before the effective date. A clean first quarter makes every later one easier. If you want a second opinion before you apply, book a short GST review with Livida.
Talk to Livida
If you are unsure whether Singapore GST registration applies to your company yet, or you want help with the application and your first returns, we can talk it through. Use our contact page, email info@livida.in, or call +91 94860 33194. Livida supports Singapore GST registration and Singapore GST filing remotely from India and does not guarantee approvals or timelines, which rest with IRAS.
References
- IRAS: Do I Need to Register for GST
- IRAS: Applying for GST Registration
- IRAS: Factors to Consider Before Registering Voluntarily for GST
- IRAS: GST InvoiceNow Requirement
- IRAS: GST Filing Due Dates and Requests for Extension
- IRAS: Changing GST Accounting Periods
- IRAS: Invoicing Customers
- IRAS: Responsibilities of a GST-Registered Business
Reviewed for accuracy in November 2026.
Related Reading
- Singapore Private Limited Company for Foreigners: 9 Essential Steps, on setting up the company before Singapore GST registration
- XBRL Automation vs Professional XBRL Filing, on the financial statements behind your annual filings
- Corporate Tax Technology Trends Every Singapore Business Should Watch, on IRAS digital services and e-filing