Big data financial analysis has become one of the more talked-about shifts in how businesses evaluate their own performance, promising a far richer picture than a quarterly spreadsheet ever could. Where traditional financial analysis methods lean on a handful of statements produced periodically, big data financial analysis pulls together transaction-level detail, operational metrics, and external signals to build a more continuous view of what is actually happening inside a business. The question for most growing companies is not whether one approach is universally better, but which combination of the two actually improves the decisions being made.

| Dimension | Big data financial analysis | Traditional financial analysis |
|---|---|---|
| Frequency | Continuous or near real time | Periodic, monthly to annual |
| Data sources | Accounting records plus operational and external data | Accounting records and financial statements |
| Interpretability | Harder to trace and explain | Easy to audit back to two or three line items |
| Best fit | Early warning signals, forward-looking questions | Compliance, external reporting, peer comparison |
Key Takeaways
- Big data financial analysis adds speed and scope, but it is only as reliable as the bookkeeping that feeds it.
- Traditional financial analysis stays the right tool for compliance, lenders and period-over-period comparison.
- Predictive models are one input to a decision, not a verdict, and they need a human reviewer.
- Reconcile the analytics layer against the general ledger so everyone works from the same numbers.
- Build in order: clean books first, traditional ratios second, advanced analytics third.
What Big Data Financial Analysis Actually Involves
At its core, big data financial analysis means applying analytical techniques to volumes and varieties of data that go well beyond a standard general ledger export. Instead of looking only at monthly totals, it might combine point-of-sale transaction detail, customer behavior data, supply chain timing, and macroeconomic indicators alongside the accounting records themselves. The goal is to find patterns and relationships that would be invisible in a summarized financial statement, because those patterns only show up when the underlying detail is examined at scale.
This is not a single tool or product; it is an approach that draws on a mix of financial analytics tools, statistical methods, and increasingly machine learning models trained to spot anomalies or correlations across large datasets. A retailer might use it to see how weather patterns affect same-day sales in specific regions. A subscription business might use it to correlate churn with support ticket volume weeks before the churn shows up in revenue. The common thread is scale and speed: more data, examined more frequently, often close to real time.
Where the Data Actually Comes From
The raw material for this kind of analysis usually comes from several places at once: the accounting system, point-of-sale or e-commerce platforms, CRM records, website analytics, and sometimes third-party datasets covering things like industry pricing trends or regional economic indicators. None of this is useful on its own. It has to be cleaned, reconciled, and connected before any analysis can produce something reliable, which is exactly why the quality of a business's underlying bookkeeping and financial records still matters enormously even in a big data context.
How Traditional Financial Analysis Methods Work
Traditional financial analysis methods are built around the standard financial statements: the income statement, balance sheet, and cash flow statement, usually reviewed monthly, quarterly, or annually. Analysts calculate ratios such as gross margin, current ratio, and return on assets, then compare them against prior periods or industry benchmarks. This approach has been refined over generations of accounting practice and remains the backbone of how lenders, investors, and boards evaluate a company's financial health.
The strength of traditional financial analysis lies in its consistency and interpretability. A current ratio or a debt-to-equity figure means roughly the same thing across industries and geographies, which makes it easy to compare a business against its peers or its own history. These methods are also less dependent on large volumes of clean supplementary data; they can be produced reliably from a well-maintained set of books alone, which is one reason accurate monthly or annual financial statement preparation remains a foundational service for businesses of every size.
The Limits of a Periodic View
The main limitation of traditional methods is timing. A monthly or quarterly review tells you what already happened, often weeks after the fact, which leaves little room to adjust course before a small problem compounds into a larger one. Ratios calculated from summarized statements also flatten out a lot of useful detail; two businesses can post an identical gross margin while having very different underlying cost structures or customer concentration risks that only granular data would reveal.
Big Data Financial Analysis vs. Traditional: Key Differences
Comparing big data financial analysis against traditional financial analysis methods really comes down to three practical differences: frequency, scope, and the type of judgment each one supports.
Speed and Frequency
Traditional analysis is inherently periodic. Statements are closed, reviewed, and reported on a cycle, which is appropriate for compliance and external reporting but slow for day-to-day operating decisions. Big data approaches, by contrast, are often built to update continuously or near-continuously, which is why they pair naturally with real-time dashboards and automated alerts rather than a static report delivered once a month.
Data Sources and Scope
Traditional financial analysis draws almost entirely from the accounting records themselves. Big data financial analysis pulls in a much wider set of inputs, some financial and some purely operational, and tries to find relationships across all of them. This broader scope can surface earlier warning signs, but it also introduces more opportunities for noisy or inconsistent data to distort the picture if it is not carefully managed.
Accuracy, Bias, and Interpretability
A traditional ratio is easy to audit and explain; you can trace it back to two or three line items on a financial statement. A predictive model built on dozens of variables is harder to interpret, and its outputs can reflect biases baked into the historical data it was trained on. This does not make big data analysis unreliable, but it does mean the results deserve more scrutiny before they are treated as fact, particularly when they are being used to justify a significant business decision.
The Rise of Predictive Financial Analysis
One of the more practical applications of big data techniques is predictive financial analysis: using historical and current data to model likely future outcomes rather than simply describing the past. This might mean forecasting cash flow under several different sales scenarios, estimating the probability that a customer segment will churn, or modeling how a change in supplier pricing would ripple through margins over the following two quarters.
Predictive financial analysis is genuinely useful for planning, but it is worth being honest about its limits. A model is only as good as the historical data and assumptions built into it, and unusual events, whether a new competitor, a supply disruption, or a shift in customer behavior, can make past patterns a poor guide to what happens next. Businesses that use predictive tools well tend to treat the output as one input among several rather than a definitive answer, running the numbers alongside conversations with people who actually understand the operational context.
Where This Fits Alongside Budgeting
Predictive analysis works best when it sits on top of, rather than replaces, disciplined budgeting and cash flow planning. A model can suggest that a seasonal dip is likely in six weeks, but it still takes a solid budget and cash flow plan to decide what to actually do about it: adjust spending, renegotiate a payment schedule, or draw down a line of credit ahead of time.
Why Data-Driven Decision Making Still Depends on Clean Books
Data-driven decision making sounds appealingly modern, but it rests on something quite unglamorous: consistently accurate underlying data. If transactions are miscategorized, if bank feeds are unreconciled, or if financial statements lag by weeks, then any analysis layered on top of that data, however sophisticated the tools, will produce misleading conclusions dressed up in confident-looking charts. This is true whether the analysis is a simple monthly variance report or a machine learning model processing millions of data points.
This is where general accounting services, regular bookkeeping, and accounting system reviews earn their keep. A business that reconciles its accounts consistently, keeps its chart of accounts clean, and produces accurate cash management reporting gives any downstream analysis, big data or traditional, a foundation it can actually trust. Skipping that step to jump straight to advanced analytics tools is a bit like building a sophisticated dashboard on top of a spreadsheet nobody has checked in months; the presentation improves, but the substance underneath does not.
Financial Analysis Still Needs a Human Reviewer
Whichever method is used, someone still needs to interpret the output in light of what is actually happening in the business. A financial analysis that flags an unusual pattern is only useful if a person with context can determine whether it reflects a real problem, a one-off event, or simply a data entry error further upstream. This is why financial analysis, prepared properly and reviewed by someone who understands both the numbers and the business, remains valuable regardless of how the underlying data was gathered.
Choosing the Right Financial Analytics Tools for Your Business
Not every business needs an enterprise-grade big data platform to benefit from better analysis. Many financial analytics tools built for small and mid-sized businesses now offer meaningful dashboards and trend analysis by connecting directly to standard cloud accounting software, without requiring a dedicated data science function, a trend we cover in more depth in the rise of API-connected accounting stacks. The more important question is usually not which tool to buy, but whether the data feeding it is accurate and current enough to make the output trustworthy.
Before investing in more advanced analytics, it is worth confirming that the basics are solid: monthly bookkeeping is up to date, cash management reporting is accurate, and financial statements reflect what actually happened rather than a rough approximation. Only once that foundation is in place does adding predictive or big data layers on top actually add value rather than just adding complexity.
Signs a Business Is Ready for More Advanced Analysis
A useful signal that a business is ready to move beyond purely traditional financial analysis is when decision-makers keep asking questions that monthly statements cannot answer quickly enough, such as which customer segments are actually profitable or how a pricing change would flow through cash flow over the following quarter. At that point, layering financial analytics tools on top of an already well-maintained set of books tends to produce genuinely useful insight rather than just more dashboards to check.
Where Traditional Methods Still Matter
Despite the appeal of newer analytical techniques, traditional financial analysis methods are not going away, and for good reason. Lenders, auditors, and regulators still expect financial statements prepared according to established standards, and comparability across periods and against industry norms remains genuinely valuable for external stakeholders. Organizations such as the IFRS Foundation continue to set the accounting standards that make these statements comparable across borders, and that consistency is not something big data techniques are designed to replace. More information is available directly from the IFRS Foundation.
Traditional analysis also tends to be more transparent about its own limitations. A gross margin trend calculated from three years of audited statements is easy to trust because the method behind it is well understood and widely accepted. That kind of clarity has real value, particularly when a business is presenting its financial position to a bank, an investor, or a board that expects familiar, well-documented metrics rather than a proprietary model's output.
Common Mistakes When Adopting Big Data Financial Analysis
Businesses moving toward big data financial analysis for the first time tend to run into a handful of predictable problems. The most common is treating volume as a substitute for quality: pulling in dozens of data sources without first checking whether any of them are accurate, consistently formatted, or even measuring what the business thinks they are measuring. A dashboard built on inconsistent inputs will look impressive and still mislead the people relying on it, which is arguably worse than having no dashboard at all, since a false sense of confidence is harder to correct than an acknowledged gap.
A second common mistake in any big data financial analysis rollout is skipping the reconciliation step between the analytics layer and the accounting records. When a predictive model or a big data dashboard shows a revenue or margin figure that does not match the general ledger, it undermines trust in the whole system, even if the discrepancy is just a timing difference or a definitional mismatch. Keeping analytics tools tightly connected to, and reconciled against, the actual books avoids this kind of confusion and keeps everyone working from the same numbers.
In the books we review, the most common reason a dashboard disagrees with the ledger is a timing or definition mismatch rather than a genuine error, so our team reconciles the two before anyone acts on the output.
Overcomplicating What Started as a Simple Question
It is also easy to overbuild. A business that just wants to know whether a marketing campaign improved margin does not necessarily need a full predictive model; a well-structured comparison using traditional financial analysis methods, informed by a bit more granular data than usual, might answer the question just as well with far less setup and maintenance. Big data financial analysis earns its complexity when the underlying question genuinely requires it, not by default. For a broader view of how human judgment fits alongside automated tools, see AI versus human judgment in accounting.
Practical Steps for Combining Both Approaches
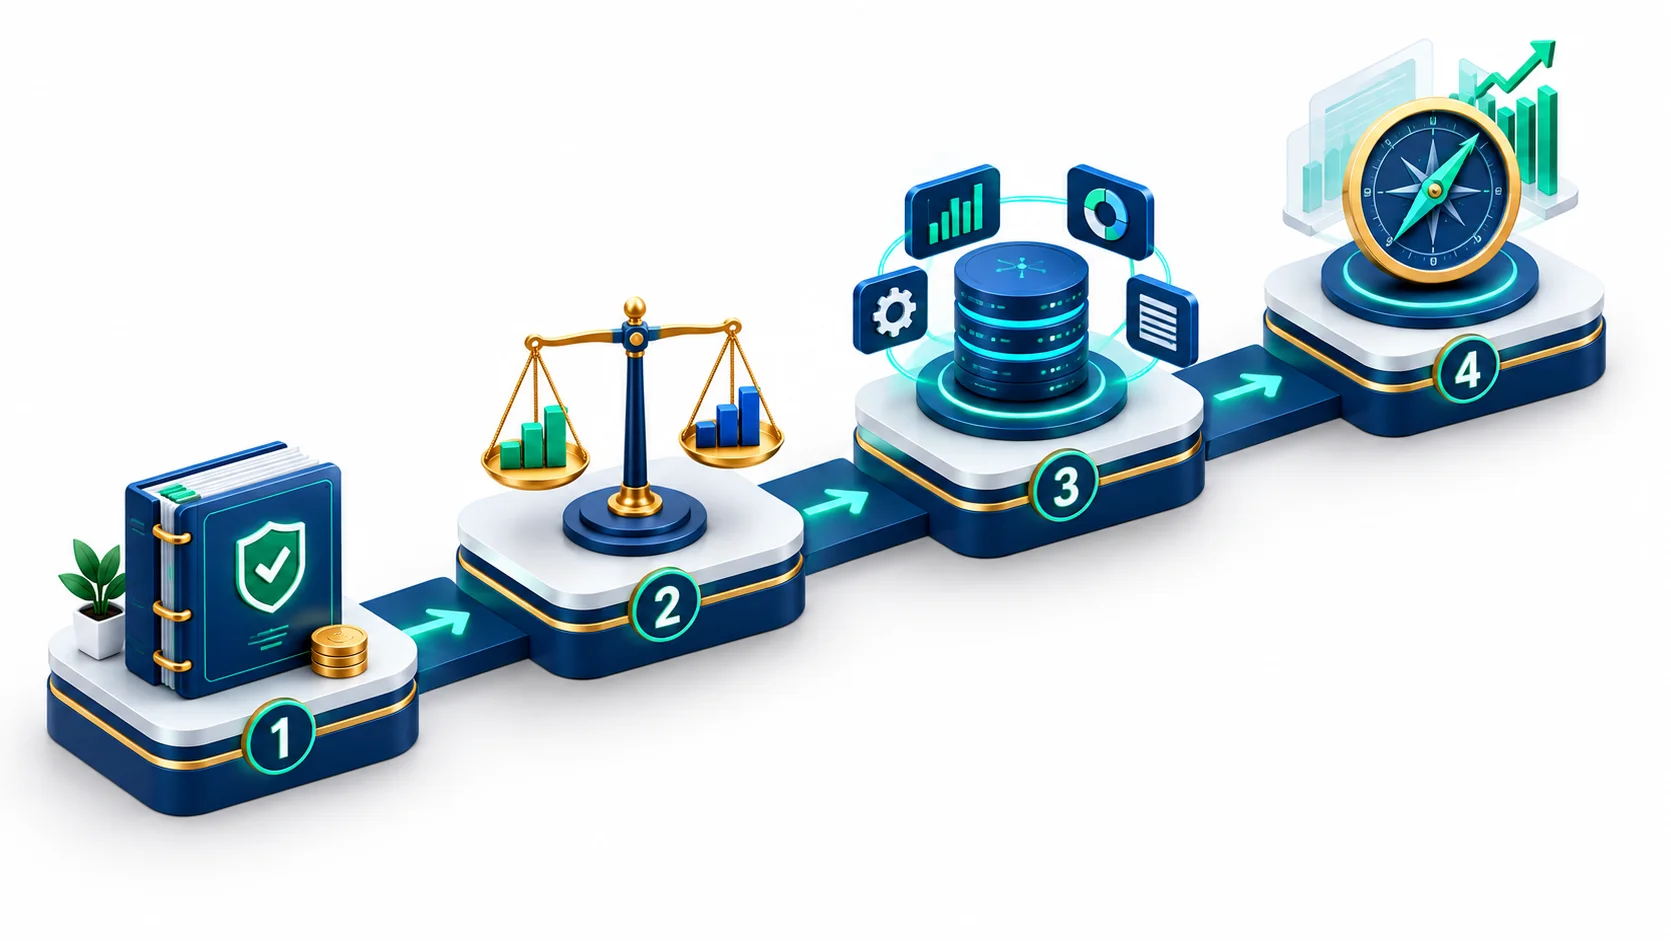
For a growing business trying to get more value out of its financial data without overhauling everything at once, a staged approach tends to work better than an all-or-nothing switch to advanced analytics:
- Confirm the core bookkeeping, chart of accounts, and monthly close process are accurate and consistent
- Layer on traditional financial analysis, tracking standard ratios and trends period over period
- Add financial analytics tools that pull in operational data alongside the accounting figures
- Revisit budgeting and cash flow planning once the underlying data is timely enough to support it, and see predictive analytics vs. traditional cash flow planning for how the two fit together
The first step is almost always the same regardless of ambition level: confirm that the core bookkeeping, chart of accounts, and monthly close process are accurate and consistent, since every later step depends on that foundation holding up. This staged approach mirrors the connectivity rollout described in our overview of the API economy in financial services.
From there, businesses can layer on traditional financial analysis, tracking standard ratios and trends period over period, before introducing any predictive or big data elements. This ordering matters because it is far easier to spot a data quality problem in a simple ratio calculation than buried inside a multivariate model. Once the basics are reliably in place, adding financial analytics tools that pull in operational data alongside the accounting figures becomes a genuine enhancement rather than a distraction from unresolved data issues.
Setting Realistic Expectations With Stakeholders
It also helps to be candid with stakeholders, whether that is a leadership team, a board, or outside investors, about what each type of analysis can and cannot tell them. Traditional financial analysis answers questions about what has already happened with a high degree of confidence. Predictive financial analysis offers informed estimates about what might happen next, with appropriately lower confidence attached. Presenting both honestly, rather than blending them into a single number that implies more certainty than either method can support on its own, tends to build more durable trust in the numbers over time.
The Role of Standards and External Benchmarks
As big data techniques become more common in financial analysis, the underlying accounting standards that make financial statements comparable have not gone anywhere, and if anything they matter more, not less. A predictive model or an analytics dashboard is only useful if the historical financial data feeding it was prepared consistently according to recognized standards. Professional bodies such as AICPA & CIMA continue to publish guidance on how accounting and financial reporting should be performed, and that guidance remains directly relevant even as the tools used to analyze the resulting data evolve. You can find their published resources at AICPA & CIMA.
Benchmarking against industry standards, whether through traditional ratio analysis or a more data-intensive comparison, only works when the inputs on both sides were prepared the same way. This is one more reason that consistent, standards-based bookkeeping and financial statement preparation underpins good analysis of any kind, rather than being a separate concern from the more visible dashboards and forecasts that sit on top of it.
Bringing the Two Approaches Together
The most practical path for most growing businesses is not choosing one method over the other but using each where it fits best. Traditional financial analysis remains the right tool for compliance, external reporting, and clear period-over-period comparison. Big data and predictive techniques add value on top of that foundation, surfacing patterns and early signals that a periodic review would miss, provided the underlying financial data is accurate enough to support the analysis in the first place.
None of this works without disciplined bookkeeping, accurate cash management reporting, and financial statements that reflect reality rather than an approximation of it. Livida's general accounting, bookkeeping, and financial analysis services are built to provide exactly that foundation, so that whichever analytical approach a business chooses, the numbers underneath it can actually be trusted. If your business is exploring how better financial data could support smarter decisions, it is worth starting with a conversation about the state of your books today.
Conclusion
Big data financial analysis and traditional financial analysis are partners rather than rivals. Use the traditional methods for compliance and comparison, use the data-heavy methods for early signals, and keep both anchored to books that are accurate and current. Where a business wants senior help interpreting the results, Livida's virtual CFO advisory service builds on exactly that foundation. This article is general information, not professional advice, and accounting standards and tax rules change, so confirm the position for your own business before acting.
Talk to Livida
If you want to review the state of your books before adding analytics, get in touch through our contact page, email info@livida.in, or call +91 94860 33194. We work with businesses across India, Singapore, the UAE, the USA and Canada on bookkeeping, compliance and reporting.
References
- IFRS Foundation: the body that develops IFRS accounting standards
- AICPA & CIMA: guidance on accounting and financial reporting practice
- IRS recordkeeping guidance for businesses: the IRS on keeping records that clearly show income and expenses