Earned wage access payroll tools have moved from a niche benefit offered by a handful of large retailers to a feature that employees across many industries now expect to see alongside their regular pay stub. The pitch is simple: instead of waiting two weeks or a month for a paycheck, employees can draw down a portion of wages they have already earned, whenever they need it. For employers, though, the appeal of a modern convenience has to be weighed against what is still, underneath the app, a payroll obligation that must be calculated, withheld, and reported correctly every single cycle.
Neither model is inherently right or wrong. The right answer depends on payroll cadence, workforce composition, the jurisdictions an employer operates in, and, just as importantly, whether the organization has a payroll process disciplined enough to absorb the extra reconciliation work an earned wage access program inevitably creates. This piece looks at how the technology works, where it genuinely helps employees, and where a traditional, well-run payroll cycle, supported by a managed payroll partner, still carries weight that no app alone can replace.

| Earned Wage Access | Traditional Payroll Cycle | |
|---|---|---|
| What it does | Advances a portion of already-earned wages early | Calculates, withholds, and reports full pay on schedule |
| Statutory compliance | Not designed to handle filings or payslips | Built around defined pay periods and reporting deadlines |
| Reconciliation risk | High if not tightly integrated with payroll | Lower, with predictable, well-established processes |
| Best used as | An added convenience layered on top | The compliance backbone underneath |
Key Takeaways
- Earned wage access payroll tools advance wages that are already earned. They do not replace the payroll run, statutory withholding or payslips.
- Most problems start with reconciliation between the advance provider and the payroll system of record.
- Fee models differ by provider, so confirm who pays before anything is rolled out.
- Any advance still outstanding must be recovered in the full and final settlement.
- Regulatory treatment varies by jurisdiction, so check the local rules first.
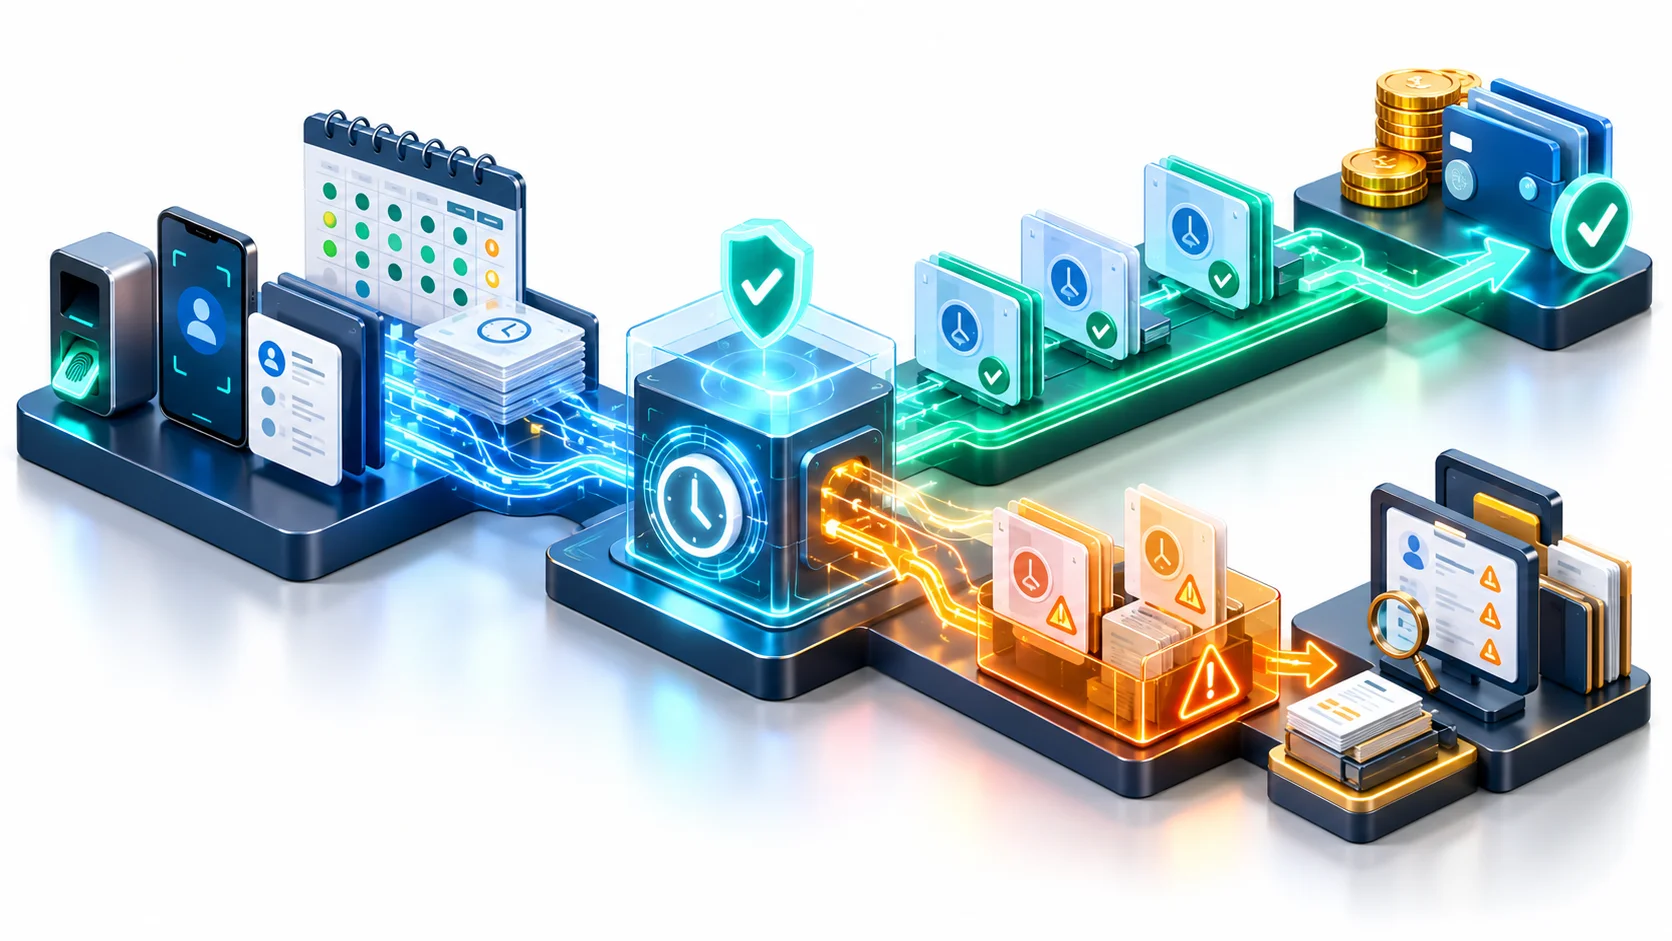
5 Essential Checks for Earned Wage Access Payroll
Before switching on an earned wage access payroll feature, work through these five checks:
- Confirm that every advance is recorded against the employee's payroll record on the day it is paid.
- Reconcile advances to the pay run before it closes, not after it has been paid.
- Make sure attendance and leave data are accurate before anyone can draw against them.
- Agree how an outstanding advance is recovered in a full and final settlement.
- Confirm in writing who bears the fees, and how the provider is regulated where your employees work.
In our experience, the most common delay in these programs is an advance report that reaches the payroll team after the pay run has already been prepared. We recommend agreeing a fixed cut-off time with the provider so the two never get out of step.
What Earned Wage Access Actually Does
At its core, an earned wage access platform tracks hours an employee has worked and, based on that accrued but unpaid wage, allows a partial withdrawal before the formal pay date. The app does not invent money. It fronts a portion of wages the employer already owes, then recoups that amount from the employee's paycheck on the next scheduled run. Some models route the advance directly through the employer's payroll system, while others operate as a third-party service that fronts the cash itself and later collects repayment, sometimes independent of the employer entirely.
The distinction between these two models matters more than most employers realize at first. An employer-integrated model touches the same payroll data pipeline used for tax withholding and statutory reporting, so errors in that integration ripple straight into compliance. A standalone consumer-finance model sits outside payroll entirely and simply reconciles later, which reduces integration risk but can create confusion for employees who don't understand where the advance came from or how it will be repaid.
Why the Earned Wage Access Payroll Model Appeals to Employers
Beyond employee goodwill, employers are drawn to earned wage access payroll tools for retention reasons. Hourly and shift-based workforces, in particular, cite pay timing as a real source of financial stress, and offering flexible access to already-earned wages is a relatively low-cost way to address it compared to raising base pay. Some employers also see it as a differentiator in competitive hourly labor markets, where a modest number of prospective hires may choose one employer over another based on pay flexibility alone.
How Fee Models Differ Across Providers
Earned wage access providers monetize their service in a few different ways, and the model chosen has a direct effect on how the benefit is perceived by employees. Some providers charge a flat per-transaction fee each time an employee draws an advance, which is transparent but can add up for employees who use the feature frequently. Others charge a monthly subscription regardless of how many advances are taken. That favors frequent users but may feel like an unnecessary cost to someone who only dips in occasionally.
A smaller group of providers bill the employer directly and offer the benefit to employees at no cost. This tends to produce the highest adoption and the most goodwill. It also carries a direct cost to the business that has to be budgeted for.
Employers evaluating providers should model out what a representative slice of their workforce would actually pay under each fee structure, rather than taking a vendor's marketing materials at face value. A benefit that looks attractive on a sales call can turn into a source of employee frustration if the real-world fees erode a meaningful share of the wages being advanced.
Financial Wellness, Not Just Convenience
It is worth acknowledging that earned wage access exists partly as a response to genuine financial precarity among hourly and shift-based workers, many of whom face unpredictable expenses that don't align neatly with a biweekly or monthly pay date. Framed well, an earned wage access program can reduce reliance on higher-cost short-term credit options.
Framed poorly, or implemented without guardrails, frequent early withdrawals can also mask a deeper issue. Employees repeatedly drawing down most of their pay early are often signaling that base compensation or pay frequency itself needs a second look. Employers who monitor usage patterns thoughtfully, rather than just enabling the feature and moving on, tend to get more genuine value out of the program.
Where the Traditional Payroll Cycle Still Wins
A traditional, fixed payroll cycle exists for reasons that predate any app. Regular, predictable pay dates make it far easier to calculate accurate tax withholding, run statutory deductions consistently, and produce payslips that match what regulators and auditors expect to see. When wages move outside that rhythm through frequent partial advances, the underlying bookkeeping has to work harder to keep every number reconciled, and any employer running payroll manually or through a lightly configured system can quickly lose track of what has already been paid out.
There is also a structural reason fixed cycles remain the backbone of nearly every payroll operation worldwide: statutory contributions, tax withholding tables, and reporting deadlines are all built around defined pay periods. An earned wage access advance does not change when tax is calculated or reported; it only changes when cash reaches the employee's account. Employers who assume the advance itself needs separate tax treatment often end up correcting errors after the fact.
Reconciliation Is Where Problems Start
The single most common failure point employers encounter with earned wage access payroll programs is reconciliation drift. If ten employees each take two or three advances in a pay period, and the payroll team is manually cross-referencing those advances against the final pay run, small errors accumulate. An employee might be short-changed on a final paycheck, or an advance might be deducted twice because two systems each believed they were responsible for recording the repayment. None of this is a flaw in the concept of earned wage access; it is a symptom of treating a payroll-adjacent tool as if it operates independently of the payroll system of record.
The Compliance Layer Earned Wage Access Payroll Apps Skip
Earned wage access payroll apps are, by design, narrow tools. They are built to solve one problem well: getting a portion of earned wages into an employee's account quickly. They are not built to manage payroll tax filing, produce compliant payslips, or reconcile leave and attendance records against hours paid. That means whatever earned wage access provider an employer chooses, the company still needs a payroll function, whether in-house or outsourced, that is responsible for the parts of payroll the app was never meant to touch.
This is precisely where a managed payroll service adds distinct value. Livida's payroll processing and salary disbursement service is built to sit underneath tools like earned wage access, absorbing the reconciliation work so an advance taken mid-cycle is properly reflected in the final payslip, statutory withholdings are calculated on the correct gross figure, and leave and attendance reconciliation still ties out against actual hours worked. A human accountant catching a mismatch between an advance ledger and a payroll run before it becomes a payslip error is the kind of exception-handling no earned wage access app is designed to perform on its own.
Statutory Compliance Doesn't Pause for Advances
Statutory compliance obligations, whatever the jurisdiction, are calculated against full earned wages for a defined period, not against the timing of when an employee chose to access part of that pay early. Payroll tax filing deadlines, social contribution schedules, and payslip generation requirements all continue on their normal cadence regardless of how many earned wage access transactions occurred in between.
In India, for example, EPF contribution schedules remain tied to the standard pay period regardless of any advance an employee has drawn. An employer that treats the app as a replacement for disciplined payroll administration, rather than a feature layered on top of it, risks discovering compliance gaps only when a regulator or auditor asks for records that don't quite add up.
Leave and Attendance Reconciliation Adds Another Layer
Earned wage access is typically calculated against hours already recorded as worked, which means the accuracy of leave and attendance records becomes directly tied to how much an employee can legitimately draw down early. If attendance data is entered manually, updated infrequently, or reconciled only at the end of a pay period, an employee could be permitted to advance against hours that are later found to be inaccurate, whether through a timesheet correction, an approved leave adjustment, or a dispute over overtime. Untangling that after the fact, once cash has already left the business, is considerably harder than preventing the mismatch in the first place.
This is one of the less visible risks employers take on when adopting earned wage access without first tightening up how attendance and leave are tracked and reconciled. A payroll partner that treats leave and attendance reconciliation as a standing part of every pay cycle, rather than an afterthought, closes much of this gap before it becomes a problem for either the employer or the employee.
Full and Final Settlement Complications
Full and final settlement is one of the more delicate moments in the employment relationship, and it becomes noticeably more complex when an employee has outstanding earned wage access advances at the time they leave. The settlement calculation needs to account for wages earned, any statutory dues, leave encashment where applicable, and now also the repayment of any advance that has not yet been recovered through a normal pay cycle. Getting this wrong, whether by under-deducting an outstanding advance or by miscalculating what remains owed to the employee, creates disputes that are avoidable with careful process design.
A managed payroll partner handling full and final settlement as a matter of course is far better positioned to catch this kind of edge case than an internal team juggling it occasionally, or an earned wage access provider whose systems were never designed to model settlement scenarios in the first place. This is less about the technology being flawed and more about matching the right tool to the right part of the process.
Building a Vendor Evaluation Checklist
Employers who move forward with an earned wage access payroll program benefit from treating vendor selection with the same rigor applied to any other payroll-adjacent system. A useful evaluation checklist covers several areas at once: how the provider's reporting integrates with the existing payroll system, how quickly and reliably reconciliation data flows back into payroll before a pay run closes, what happens operationally when an employee with an outstanding advance resigns or is terminated, and how the provider handles disputes when an employee believes an advance or repayment was calculated incorrectly.
It is equally important to ask how the provider supports audit requests. If a regulator or internal auditor asks for a full ledger of advances taken, repaid, and outstanding across a given period, the provider should be able to produce that data quickly and in a format that reconciles cleanly against payroll records. A provider that cannot answer this clearly during the sales process is unlikely to perform better once the relationship is live.
A vendor evaluation checklist typically covers:
- How reporting integrates with the existing payroll system
- How quickly reconciliation data flows back before a pay run closes
- What happens when an employee with an outstanding advance resigns or is terminated
- How disputes over an advance or repayment amount are handled
- Whether the provider can produce a full audit ledger on request
For related reading on similar automation-versus-oversight trade-offs in payroll, see our comparisons of cloud HR suites versus payroll tax filing support, multi-country payroll platforms versus local expertise, and biometric attendance technology versus payroll accuracy.
Piloting Before a Full Rollout
Rather than rolling out an earned wage access payroll program company-wide on day one, many employers get better results by piloting the program with a single location, department, or shift group first. A pilot surfaces integration issues, fee-structure concerns, and reconciliation gaps on a manageable scale before they multiply across an entire workforce. It also gives the payroll team, whether internal or outsourced, a realistic sense of how much additional reconciliation work the feature actually creates once it is in daily use, rather than relying on a vendor's estimate.
Weighing Adoption Realistically
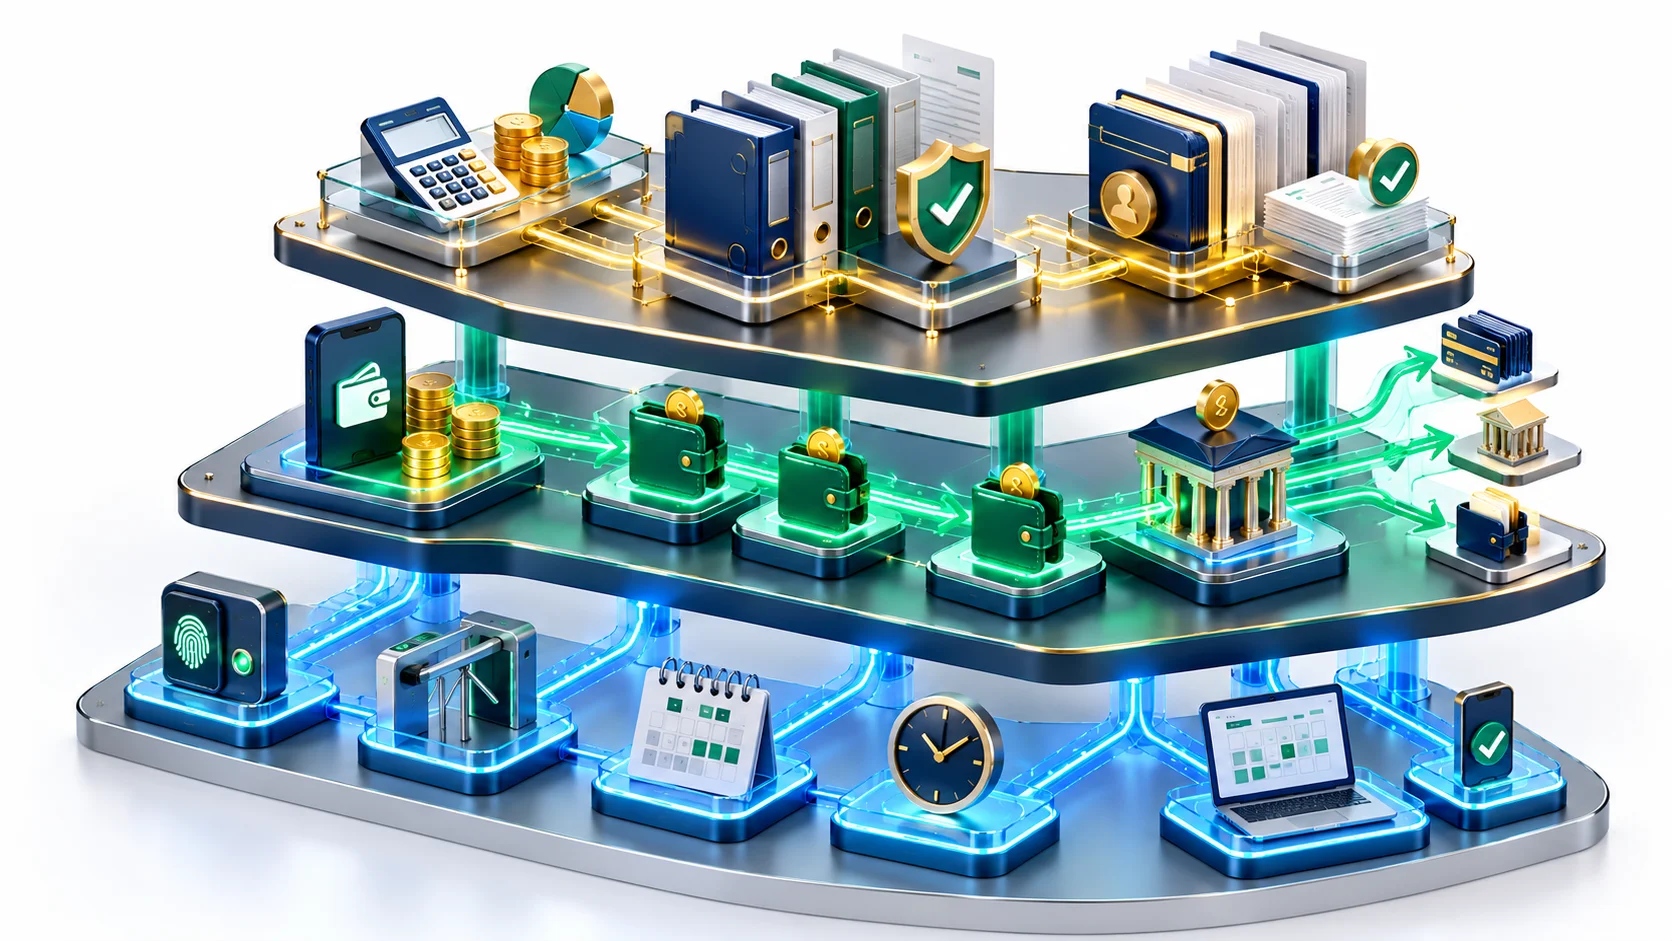
None of this argues against earned wage access payroll tools as a concept. For many employers, particularly those with large hourly or shift-based workforces, offering employees a modest, well-governed way to access earned pay early is a reasonable and often welcomed benefit. The technology behind these apps has matured considerably, and integrations with mainstream payroll platforms have become more reliable than they were a few years ago.
The more useful question for an employer to ask isn't whether earned wage access is a good idea, but whether the payroll operation underneath it is solid enough to absorb the additional reconciliation work without introducing errors. A fixed payroll cycle run by a careful, accountable team, whether internal or outsourced, gives an employer the foundation to layer a feature like earned wage access on top without compromising the accuracy of tax withholding, statutory filings, or final settlements.
Keeping an Eye on the Regulatory Landscape
Regulatory treatment of earned wage access payroll tools is still evolving in a number of jurisdictions, with some regulators debating whether particular fee structures effectively function as short-term lending and should be licensed and disclosed accordingly. Employers do not need to become experts in consumer finance law, but they do need to confirm that whichever provider they choose is operating within the current rules of the jurisdictions where their employees are based, and that the provider is prepared to adjust its model if those rules change. A provider that treats regulatory compliance as someone else's problem is not a provider worth building a long-term payroll relationship around.
Questions Worth Asking Before Rollout
Employers considering an earned wage access payroll program should ask their provider precisely how advances are reported back to payroll, how frequently reconciliation happens, and what happens in edge cases like an employee taking leave, being terminated, or having wages garnished. These are not edge cases in practice; they happen regularly across any workforce of meaningful size, and a provider that cannot answer clearly is signaling a gap the employer will eventually have to fill themselves.
It is also worth asking whether the earned wage access provider's reporting format is compatible with the employer's existing payroll and bookkeeping systems, or whether manual re-entry will be required. Manual re-entry is where most reconciliation errors originate, and it is exactly the kind of repetitive, detail-sensitive work that a dedicated bookkeeping and payroll team is set up to handle accurately and consistently.
Conclusion
Earned wage access payroll tools solve a real problem for employees who need more flexibility than a fixed pay date allows, and there is nothing inherently risky about offering the benefit. What matters is recognizing that the app handles only the advance itself, while every other part of payroll, from statutory withholding to payslip generation to full and final settlement, still needs a disciplined, accurate process behind it. Employers who pair a well-chosen earned wage access provider with a payroll partner capable of reconciling those advances against actual pay runs get the benefit of employee flexibility without inheriting the compliance risk that comes from treating the app as a substitute for real payroll administration.
If your organization is exploring earned wage access or already offering it and wants a second set of eyes on how advances are being reconciled against payroll, Livida's payroll team is glad to walk through what a clean process looks like for your specific payroll cycle.
Talk to Livida
Livida's payroll and bookkeeping teams work with employers who want advances reconciled cleanly against each pay run. You can use our contact page, email info@livida.in or call +91 94860 33194. For more on how we handle pay cycles, see our payroll service and bookkeeping service.
For related reading, see self-service payroll apps versus full-service payroll and real-time payroll versus year-end accounting.
This article is general information, not professional advice. Payroll, labour and lending rules change, so check the current position for your jurisdiction before acting.
References
- EPFO: Online ECR and challan submission, the official page on how employers file the monthly provident fund return and payment in India.
- Reserve Bank of India: Digital Lending Directions, 2025, the regulator's rules for digital lending by banks and NBFCs. Whether a given wage advance model falls within them depends on how it is structured.
- Reserve Bank of India, for current circulars and notifications on payments and lending.